



 Chat with AI
Exam 21: International Corporate Finance

Exam 1: Introduction to Corporate Finance71 Questions
Exam 2: Financial Statements, Taxes, and Cash Flow81 Questions
Exam 3: Working With Financial Statements96 Questions
Exam 4: Long-Term Financial Planning and Growth80 Questions
Exam 5: Introduction to Valuation: The Time Value of Money68 Questions
Exam 6: Discounted Cash Flow Valuation132 Questions
Exam 7: Interest Rates and Bond Valuation129 Questions
Exam 8: Stock Valuation119 Questions
Exam 9: Net Present Value and Other Investment Criteria115 Questions
Exam 10: Making Capital Investment Decisions108 Questions
Exam 11: Project Analysis and Evaluation106 Questions
Exam 12: Some Lessons From Capital Market History98 Questions
Exam 13: Return, Risk, and the Security Market Line109 Questions
Exam 14: Cost of Capital100 Questions
Exam 15: Raising Capital93 Questions
Exam 16: Financial Leverage and Capital Structure Policy98 Questions
Exam 17: Dividends and Payout Policy103 Questions
Exam 18: Short-Term Finance and Planning109 Questions
Exam 19: Cash and Liquidity Management101 Questions
Exam 20: Credit and Inventory Management97 Questions
Exam 21: International Corporate Finance99 Questions
Exam 22: Behavioral Finance: Implications for Financial Management45 Questions
Exam 23: Enterprise Risk Management68 Questions
Exam 24: Options and Corporate Finance106 Questions
Exam 25: Option Valuation79 Questions
Exam 26: Mergers and Acquisitions89 Questions
Exam 27: Leasing72 Questions
Select questions type


You are analyzing a project with an initial cost of £48,000.The project is expected to return £11,000 the first year,£36,000 the second year and £38,000 the third and final year.There is no salvage value.The current spot rate is £0.6211.The nominal return relevant to the project is 12 percent in the U.S.The nominal risk-free rate in the U.S.is 4 percent while it is 5 percent in the U.K.Assume that uncovered interest rate parity exists.What is the net present value of this project in U.S.dollars?

Free
(Multiple Choice)
4.8/5  (80)
(80) Correct Answer: Verified
B
A basic interest rate swap generally involves trading a:
Free
(Multiple Choice)
4.8/5 (78)
(78) Correct Answer:Verified
VerifiedD
Which one of the following states that the expected percentage change in the exchange rate between two countries is equal to the difference in the countries' interest rates?
Free
(Multiple Choice)
5.0/5 (73)
(73) Correct Answer:Verified
VerifiedB
You would like to purchase a security that is issued by the British government.Which one of the following should you purchase?
(Multiple Choice)
4.9/5 (79)
(79) Which one of the following is the risk that a firm faces when it opens a facility in a foreign country,given that the exchange rate between the firm's home country and this foreign country fluctuates over time?
(Multiple Choice)
4.9/5 (88)
(88) Assume that $1 is equal to ¥98 and also equal to C$1.21.Based on this,you could say that C$1 is equal to: C$1(¥98/C$1.21)= ¥80.99.The exchange rate of C$1 = ¥80.99 is referred to as the:
(Multiple Choice)
4.7/5 (79)
(79) Assume you can buy 52 British pounds with 100 Canadian dollars.How much profit can you earn on a triangle arbitrage given the following rates if you start out with 100 U.S.dollars? 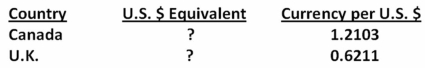
(Multiple Choice)
5.0/5 (82)
(82) Assume the spot rate for the British pound currently is £0.6211 per $1.Also assume the one-year forward rate is £0.6347 per $1.A risk-free asset in the U.S.is currently earning 3.4 percent.If interest rate parity holds,what rate can you earn on a one-year risk-free British security?
(Multiple Choice)
4.7/5 (70)
(70) Which one of the following states that the current forward rate is an unbiased predictor of the future spot exchange rate?
(Multiple Choice)
4.9/5 (95)
(95) What conditions are necessary for absolute purchasing power parity (PPP)to exist?
Is it realistic to believe PPP can exist within a country let alone across national borders?
(Essay)
4.8/5 (78)
(78) A trader has just agreed to exchange $2 million U.S.dollars for $1.55 million Euros six months from today.This exchange is an example of a:
(Multiple Choice)
4.8/5 (66)
(66) Assume the spot rate for the Japanese yen currently is ¥99.31 per $1 and the one-year forward rate is ¥97.62 per $1.A risk-free asset in Japan is currently earning 2.5 percent.If interest rate parity holds,approximately what rate can you earn on a one-year risk-free U.S.security?
(Multiple Choice)
4.7/5 (64)
(64) Which of the following statements are correct?
I.The usage of forward rates increases the short-run exposure to exchange rate risk.
II.Accounting translation gains and losses are recorded in the equity section of the balance sheet.
III.The long-run exchange rate risk faced by an international firm can be reduced if a firm borrows money in the foreign country where the firm has operations.
IV.Unexpected changes in economic conditions are classified as short-run exposure to exchange rate risk.
(Multiple Choice)
4.9/5 (76)
(76) You are expecting a payment of 450,000PLN three years from now.The risk-free rate of return is 3 percent in the U.S.and 4 percent in Poland.The inflation rate is 2.5percent in the U.S.and 3 percent in Poland.Currently,you can buy 277PLN for 100USD.How much will the payment three years from now be worth in U.S.dollars?
(Multiple Choice)
4.9/5 (83)
(83) How many Euros can you get for $2,200 if one euro is worth $1.2762?
(Multiple Choice)
4.9/5 (85)
(85) The type of exchange rate risk known as translation exposure is best described as:
(Multiple Choice)
4.8/5 (88)
(88) Which one of the following supports the idea that real interest rates are equal across countries?
(Multiple Choice)
4.8/5 (69)
(69) Party A has agreed to exchange $1 million U.S.dollars for $1.21 million Canadian dollars.What is this agreement called?
(Multiple Choice)
4.8/5 (91)
(91) You are planning a trip to Australia.Your hotel will cost you A$145 per night for seven nights.You expect to spend another A$2,800 for meals,tours,souvenirs,and so forth.How much will this trip cost you in U.S.dollars given the following exchange rates? 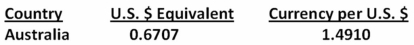
(Multiple Choice)
4.9/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)