



 Chat with AI
Exam 18: Related-Party Disclosures

Exam 1: An Overview of the International External Reporting Environment58 Questions
Exam 2: The Conceptual Framework of Accounting and Its Relevance to Financial Reporting69 Questions
Exam 3: Theories of Financial Accounting76 Questions
Exam 4: An Overview of Accounting for Assets75 Questions
Exam 5: Depreciation of Property, Plant and Equipment63 Questions
Exam 6: Revaluations and Impairment Testing of Non-Current Assets52 Questions
Exam 7: Inventory63 Questions
Exam 8: Accounting for Intangibles55 Questions
Exam 9: An Overview of Accounting for Liabilities58 Questions
Exam 10: Accounting for Leases64 Questions
Exam 11: Share Capital, Reserves and Share Options Employee Bonus Schemes62 Questions
Exam 12: Accounting for Financial Instruments70 Questions
Exam 13: Revenue Recognition Issues61 Questions
Exam 14: The Statement of Comprehensive Income and Statement of Changes in Equity65 Questions
Exam 15: Accounting for Income Taxes97 Questions
Exam 16: The Statement of Cash Flows69 Questions
Exam 17: Events Occurring After the Reporting Date66 Questions
Exam 18: Related-Party Disclosures63 Questions
Exam 19: Earnings Per Share61 Questions
Exam 21: Further Consolidation Issues I: Accounting for Intragroup Transactions46 Questions
Exam 22: Further Consolidation Issues II: Accounting for Non-Controlling Interests30 Questions
Exam 23: Further Consolidation Issues III: Accounting for Indirect Ownership Interest46 Questions
Exam 24: Accounting for Foreign Currency Transactions55 Questions
Exam 25: Translating the Financial Statements of Foreign Operations33 Questions
Exam 26: Accounting for Corporate Social Responsibility52 Questions
Select questions type


The following diagram shows five companies and their associated equity ownership percentages.Which of the companies shown would most likely be considered related entities? 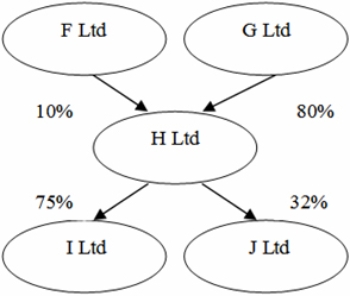
(Multiple Choice)
4.8/5  (80)
(80) The definition of related parties relies on three key terms.These are:
(Multiple Choice)
4.8/5 (80)
(80) In IAS 24 Related Party Disclosures,two entities having a director in common are assumed related parties.
(True/False)
5.0/5 (76)
(76) The disclosure requirements of IAS 24 are grouped in part by:
(Multiple Choice)
4.7/5 (76)
(76) Related-party transactions pose serious risks to the reporting entity and generate no benefits.
(True/False)
5.0/5 (83)
(83) In accordance with IAS 24,the categories of compensation to key management personnel required to be disclosed include:
(Multiple Choice)
4.9/5 (89)
(89) IAS 24 requires a standard,detailed set of disclosure requirements for all related-party transactions.
(True/False)
4.7/5 (77)
(77) Discuss the current debate regarding the setting and disclosure of executive compensation.
(Essay)
4.9/5 (85)
(85) IAS 24 Related Party Disclosures,requires relationships between parents and subsidiaries be disclosed irrespective of whether there have been transactions between those related parties.
(True/False)
4.8/5 (63)
(63) Which of the following transactions is usually not considered a 'related party' in IAS 24?
(Multiple Choice)
5.0/5 (87)
(87) Reasons for the requirement to disclose related-party transactions include:
(Multiple Choice)
4.8/5 (86)
(86) The definition of control adopted in IAS 24 relies on the power to:
(Multiple Choice)
4.8/5 (75)
(75) Reasons for the requirement to disclose related-party transactions include:
(Multiple Choice)
4.8/5 (79)
(79) Which of the following is usually not a related party as referred to in IAS 24 Related Party Disclosures?
(Multiple Choice)
4.8/5 (85)
(85) The definition of related parties under IAS 24 excludes entities (other than those specified earlier in the relevant paragraph)where the related-party relationship:
(Multiple Choice)
4.9/5 (76)
(76) IAS 24 reflects the view that transactions carried out by related parties cannot be presumed to be at arm's length.
(True/False)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)