



 Chat with AI
Exam 8: Accounting for Intangibles

Exam 1: An Overview of the International External Reporting Environment58 Questions
Exam 2: The Conceptual Framework of Accounting and Its Relevance to Financial Reporting69 Questions
Exam 3: Theories of Financial Accounting76 Questions
Exam 4: An Overview of Accounting for Assets75 Questions
Exam 5: Depreciation of Property, Plant and Equipment63 Questions
Exam 6: Revaluations and Impairment Testing of Non-Current Assets52 Questions
Exam 7: Inventory63 Questions
Exam 8: Accounting for Intangibles55 Questions
Exam 9: An Overview of Accounting for Liabilities58 Questions
Exam 10: Accounting for Leases64 Questions
Exam 11: Share Capital, Reserves and Share Options Employee Bonus Schemes62 Questions
Exam 12: Accounting for Financial Instruments70 Questions
Exam 13: Revenue Recognition Issues61 Questions
Exam 14: The Statement of Comprehensive Income and Statement of Changes in Equity65 Questions
Exam 15: Accounting for Income Taxes97 Questions
Exam 16: The Statement of Cash Flows69 Questions
Exam 17: Events Occurring After the Reporting Date66 Questions
Exam 18: Related-Party Disclosures63 Questions
Exam 19: Earnings Per Share61 Questions
Exam 21: Further Consolidation Issues I: Accounting for Intragroup Transactions46 Questions
Exam 22: Further Consolidation Issues II: Accounting for Non-Controlling Interests30 Questions
Exam 23: Further Consolidation Issues III: Accounting for Indirect Ownership Interest46 Questions
Exam 24: Accounting for Foreign Currency Transactions55 Questions
Exam 25: Translating the Financial Statements of Foreign Operations33 Questions
Exam 26: Accounting for Corporate Social Responsibility52 Questions
Select questions type


Brighton Shores Plc has a cash generating unit (CGU)and has been assessed for impairment and it has determined an impairment loss of £100 000. The following information relates to the assets as at 30 June 2012. Carrying amount Recoverable amount Buildings 800000 900000 Equipment 200000 150000 Goodwill 50000 In accordance with IAS 36 Impairment of Assets what should be the carrying amount of equipment as at 30 June 2014?

Free
(Multiple Choice)
5.0/5  (64)
(64) Correct Answer: Verified
C
If the fair value of a revalued intangible asset can no longer be determined by reference to an active market,IAS 36 requires the use of the cost model.
Free
(True/False)
4.7/5 (72)
(72) Correct Answer:Verified
VerifiedFalse
In order to determine whether or not expenditure should be treated as an intangible asset,the relevant test to apply is:
Free
(Multiple Choice)
4.7/5 (86)
(86) Correct Answer:Verified
VerifiedD
Prior to the introduction of impairment testing companies had attempted to manipulate their financial statements through amortisation:
(Multiple Choice)
4.9/5 (96)
(96) Which of the following statements is correct with respect to intangible assets?
(Multiple Choice)
4.8/5 (73)
(73) Outline the requirements of IAS 38 on recognition and measurement of research and development activities.
(Essay)
4.8/5 (68)
(68) The revaluation model requires all intangible assets in the same class to have a fair value determined by reference to an active market.
(True/False)
4.9/5 (76)
(76) After initial recognition,the acquirer shall recognise goodwill at:
(Multiple Choice)
4.9/5 (72)
(72) The release of IAS 38 has had what impact on the methods of amortising goodwill?
(Multiple Choice)
4.7/5 (78)
(78) Castle Co Ltd is working on three research projects.Project Jonah is government-sponsored research on synthesising currently available research results on the possible triggers of asthma attacks.Project Beta involves researching the genetic tags associated with heart disease based on the genome project.A test to identify the predisposition to heart disease in children has been developed and will be on the market in 2013.Since 2011 research and development expenditures on this project are applied development costs only.Project Sigma is cutting edge research being conducted to try and discover a means of 'disassembling' molecules and then 'reassembling' them in their original form.The company hopes that this work will lay the basis for future dreams of teleportation as a method of transport.Details of expenditures and recoverable amounts expected beyond a reasonable doubt at this time are: 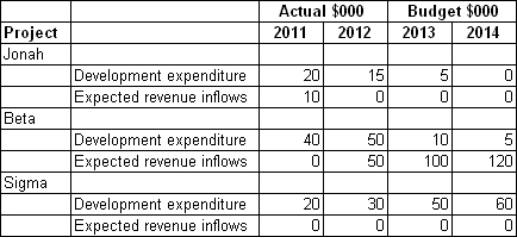 What is the total research and development deferral for each project as at the end of the year 2012?
 (Multiple Choice)
4.7/5 (75)
(75) Broadbeach Plc is a manufacturing company with three subsidiaries.The following information relates to the goodwill account of Broadbeach Plc for the year ended 30 June 2013. Goodwill Accumulated impairment loss Carrying amount of CGU Recoverable amount of CGU Mantra Ltd 50000 10000 250000 270000 Oceania Ltd 40000 Nil 310000 250000 Wave Ltd 60000 Nil 450000 600000 In accordance with IAS 36,what is the net effect of above goodwill accounts on the statement of comprehensive income and statement of financial position of Broadbeach Plc?
(Multiple Choice)
4.9/5 (87)
(87) Which of the following statement(s)in regard to goodwill is/are correct in accordance with IAS 36 Impairment of Assets?
(Multiple Choice)
4.8/5 (84)
(84) IAS 38 prohibits the recognition of intangible assets using the revaluation model.
(True/False)
4.9/5 (88)
(88) Broadbeach Plc is a manufacturing company with three subsidiaries.The following information relates to the goodwill account of Broadbeach Plc for the year ended 30 June 2013: (in dollars) Goodwill Accumulated impairment loss Carrying amount of CGU Recoverable amount of CGU Mantra Ltd 50000 10000 250000 270000 Oceania Ltd 40000 Nil 310000 250000 Wave Ltd 60000 Nil 450000 600000 What is the carrying amount of goodwill as at 30 June 2013 consistent with IAS 36 Impairment of Assets?
(Multiple Choice)
4.8/5 (83)
(83) During 2001 the Financial Accounting Standards Board in the United States indicated they would look to change a requirement for the treatment of goodwill.That change is:
(Multiple Choice)
4.9/5 (75)
(75) As part of adopting IFRS,goodwill acquired in a business combination is no longer amortised.Instead,the acquirer shall test goodwill for impairment (IFRS 3 Business Combinations).When is goodwill considered to be impaired?
(Multiple Choice)
5.0/5 (86)
(86) There is a concern that research and development may be reduced as a result of the new requirements in IAS 38 because:
(Multiple Choice)
4.9/5 (86)
(86) Examples of elements of a business that commonly make up goodwill are:
(Multiple Choice)
4.9/5 (96)
(96) Big Ltd has purchased 100% of Little Ltd for a cash payment of $800 000.The additional costs to Big Ltd to complete the purchase were $3000.An extract from the statement of financial position for Little Ltd at the date of acquisition shows: 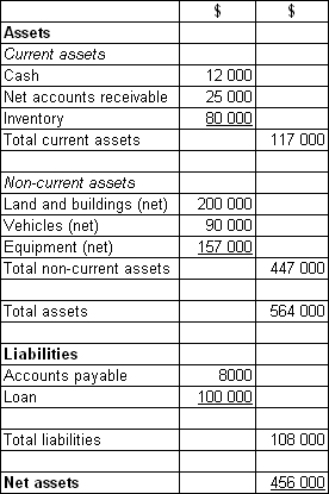 Additional information:
The assets and liabilities of Little Ltd are stated at fair value except that:
Land and buildings have a fair value of $300 000
Accounts receivable have a fair value of $20 000.
Little owns a licence that has not been recorded in the financial statements.Its fair value is $150 000.
What is the amount of purchased goodwill that has been acquired by Big Ltd?
Additional information:
The assets and liabilities of Little Ltd are stated at fair value except that:
Land and buildings have a fair value of $300 000
Accounts receivable have a fair value of $20 000.
Little owns a licence that has not been recorded in the financial statements.Its fair value is $150 000.
What is the amount of purchased goodwill that has been acquired by Big Ltd? (Multiple Choice)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)