



 Chat with AI
Exam 18: Options and Contingent Claims

Exam 1: Introduction44 Questions
Exam 2: Consumption, Investment and the Capital Market56 Questions
Exam 3: The Time Value of Money: An Introduction to Financial Mathematics62 Questions
Exam 4: Applying the Time Value of Money to Security Valuation62 Questions
Exam 5: Project Evaluation: Principles and Methods65 Questions
Exam 6: The Application of Project Evaluation Methods64 Questions
Exam 7: Risk and Return76 Questions
Exam 8: The Capital Market64 Questions
Exam 9: Sources of Finance: Equity51 Questions
Exam 10: Sources of Finance: Debt87 Questions
Exam 11: Payout Policy53 Questions
Exam 12: Principles of Capital Structure57 Questions
Exam 13: Capital Structure Decisions51 Questions
Exam 14: The Cost of Capital and Taxation Issues in Project Evaluation47 Questions
Exam 15: Leasing and Other Equipment Finance49 Questions
Exam 16: Capital Market Efficiency55 Questions
Exam 17: Futures Contracts66 Questions
Exam 18: Options and Contingent Claims59 Questions
Exam 19: Analysis of Takeovers55 Questions
Exam 20: International Financial Management58 Questions
Exam 21: Management of Short-Term Assets: Inventory52 Questions
Exam 22: Management of Short-Term Assets: Liquid Assets and Accounts Receivable28 Questions
Select questions type


Calculate the price of a two-month European put option given the following information: the exercise price is $19,the current share price is $15 and the risk-free interest rate is 12% p.a.Furthermore,the share price may go up by 10 per cent or down by 10 per cent at the end of each month.Assume a risk-neutral world and time periods of one month each.
(Multiple Choice)
4.7/5  (73)
(73) A payoff structure resembling that of a short futures position can be created by:
(Multiple Choice)
4.8/5 (76)
(76) Which of the following statements regarding call options is true?
(Multiple Choice)
4.8/5 (81)
(81) Ratio of the change in an option price that results from a change in the price of the underlying assets is known as the option's:
(Multiple Choice)
4.9/5 (74)
(74) Using the Black-Scholes formula,calculate the price of a put option from the following information: exercise price $3.00;current share price $3.30;term to expiry three months;standard deviation 0.30 p.a. ;and risk-free interest rate 10% p.a.continuously compounded.
(Multiple Choice)
4.8/5 (76)
(76) A call option can have a negative payoff,however the payoff on a put option is always positive.
(True/False)
4.8/5 (77)
(77) Calculate the price of a European call option if the price of the equivalent European put option is $5 and the share price,exercise price and risk-free rate (continuously compounded)are $31,$28 and 12% p.a. ,respectively.The options have three months to expiry.
(Multiple Choice)
4.7/5 (75)
(75) An option creates the obligation for delivery of the underlying asset at a pre-determined point of time in the future.
(True/False)
4.8/5 (78)
(78) All things being equal,the more ________________ is the underlying share price,call prices should be higher.
(Short Answer)
4.9/5 (81)
(81) Which of the following is a potential disadvantage of privately negotiated options?
(Multiple Choice)
4.8/5 (69)
(69) For each of the options shown in the following table,use the cost of underlying share price at expiration along with the other information to determine the amount of profit or loss an investor would have had,ignoring transaction/brokerage costs.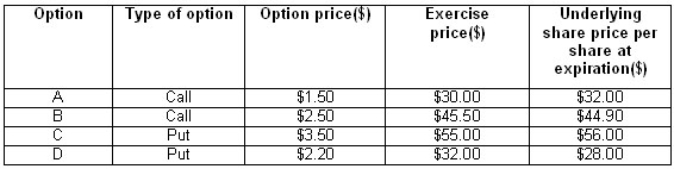
(Not Answered)
This question doesn't have any answer yet
Calculate the price of a two-month European call option given the following information: the exercise price is $19,the current share price is $20 and the risk-free interest rate is 15% p.a.Furthermore,the share price may go up by 15 per cent or down by 15 per cent at the end of each month.Assume a risk-neutral world and time periods of one month each.
(Multiple Choice)
4.8/5 (82)
(82) The price of an option is affected by the risk-free interest rate.
(True/False)
4.7/5 (92)
(92) The Black-Scholes model of call option pricing is only valid for American type call options.
(True/False)
4.9/5 (93)
(93) A _______________ call option can only be exercised on maturity.
(Short Answer)
4.9/5 (94)
(94) If the share price at the expiry of a call option is less than the exercise price,the call is worth:
(Multiple Choice)
4.9/5 (84)
(84) In most instances an American call option should not be exercised early.
(True/False)
4.9/5 (83)
(83) The value of an option in excess of its intrinsic value is known as:
(Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)