



 Chat with AI
Exam 11: The Firm: Production and Costs

Exam 1: The Role and Method of Economics198 Questions
Exam 2: Economics: Eight Powerful Ideas197 Questions
Exam 3: Scarcity, Trade-Offs, and Production Possibilities189 Questions
Exam 4: Demand, Supply, and Market Equilibrium240 Questions
Exam 5: Markets in Motion and Price Controls228 Questions
Exam 6: Elasticities206 Questions
Exam 7: Market Efficiency and Welfare136 Questions
Exam 8: Market Failure215 Questions
Exam 9: Public Finance and Public Choice64 Questions
Exam 10: Consumer Choice Theory149 Questions
Exam 11: The Firm: Production and Costs198 Questions
Exam 12: Firms in Perfectly Competitive Markets207 Questions
Exam 13: Monopoly and Antitrust189 Questions
Exam 14: Monopolistic Competition and Product Differentiation159 Questions
Exam 15: Oligopoly and Strategic Behavior146 Questions
Exam 16: The Markets for Labor, Capital, and Land177 Questions
Exam 17: Income, Poverty, and Health Care138 Questions
Exam 18: Introduction to Macroeconomics: Unemployment, Inflation, and Economic Fluctuations171 Questions
Exam 19: Measuring Economic Performance147 Questions
Exam 20: Economic Growth in the Global Economy127 Questions
Exam 21: Financial Markets, Saving, and Investment65 Questions
Exam 22: Aggregate Demand and Aggregate Supply163 Questions
Exam 23: The Aggregate Expenditure Model69 Questions
Exam 25: Monetary Institutions182 Questions
Exam 26: The Federal Reserve System and Monetary Policy147 Questions
Exam 27: Issues in Macroeconomic Theory and Policy130 Questions
Exam 28: International Trade182 Questions
Exam 29: International Finance138 Questions
Select questions type


Exhibit 11-10 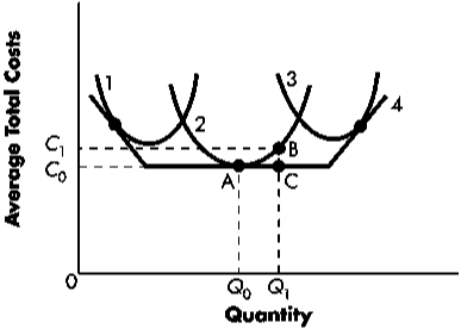 Refer to Exhibit 11-10.In the long run the firm can move from
 (Multiple Choice)
4.8/5  (73)
(73) Which of the following is most likely to be a fixed cost for a business?
(Multiple Choice)
4.8/5 (95)
(95) One would expect to observe a diminishing marginal product of labor when crowded office space reduces the productivity of new workers.
(True/False)
4.8/5 (76)
(76) Exhibit 11-1  Refer to Exhibit 11-1.The marginal product of labor begins to diminish with the addition of the ____ picker.
 (Multiple Choice)
4.8/5 (70)
(70) The total fixed cost of operating a lumberyard equals $12,000 this year.The average fixed cost of the lumberyard will not be affected by the quantity of lumber that is sold.
(True/False)
4.7/5 (65)
(65) An economic profit of zero indicates a satisfactory situation for the firm.
(True/False)
4.8/5 (78)
(78) Exhibit 11-8 The table below shows how total cost varies with output in a factory producing watches:
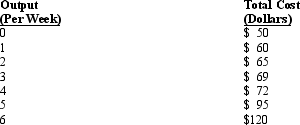 Refer to Exhibit 11-8.If the output equals four watches per week,then the average total cost of producing a watch equals:
 (Multiple Choice)
4.9/5 (80)
(80) Why is the long-run average total cost (LRATC)curve called the planning curve?
(Essay)
4.8/5 (81)
(81) In the table below,diminishing marginal product is first evident with the addition of the ____ worker. 
(Multiple Choice)
4.8/5 (84)
(84) Diminishing marginal product first sets in at the minimum point of the
(Multiple Choice)
4.8/5 (91)
(91) Assume that you know the following cost information about Fred's widget company: Its fixed cost is $9,and its total variable cost is $6 for 1 unit; $11 for 2; $ 15 for 3; 20 for 4; and 26 for 5.Given the above information,
(Multiple Choice)
4.8/5 (68)
(68) When economies of scale exist,an increase in the level of output will lead to:
(Multiple Choice)
4.8/5 (88)
(88) Explain the cost advantage of a firm operating at constant returns to scale.
(Essay)
4.9/5 (82)
(82) A firm can produce 840 gallons of paint per day with 6 workers,or 910 gallons per day with 7 workers.The marginal product of labor over this range of output,stated in gallons per worker per day,is
(Multiple Choice)
4.7/5 (75)
(75) Which of the following factors of production is not variable in the long run?
(Multiple Choice)
4.8/5 (82)
(82) Which of the following is true at the output level where diminishing marginal product first set in?
(Multiple Choice)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)