



 Chat with AI
Exam 16: Option Valuation

Exam 1: A Brief History of Risk and Return104 Questions
Exam 2: The Investment Process100 Questions
Exam 3: Overview of Security Types94 Questions
Exam 4: Mutual Funds and Other Investment Companies107 Questions
Exam 5: The Stock Market107 Questions
Exam 6: Common Stock Valuation111 Questions
Exam 7: Stock Price Behavior and Market Efficiency83 Questions
Exam 8: Behavioral Finance and the Psychology of Investing84 Questions
Exam 9: Interest Rates103 Questions
Exam 10: Bond Prices and Yields100 Questions
Exam 11: Diversification and Risky Asset Allocation88 Questions
Exam 12: Return,Risk,and the Security Market Line88 Questions
Exam 13: Performance Evaluation and Risk Management96 Questions
Exam 14: Futures Contracts100 Questions
Exam 15: Stock Options104 Questions
Exam 16: Option Valuation74 Questions
Exam 17: Projecting Cash Flow and Earnings105 Questions
Exam 18: Corporate and Government Bonds112 Questions
Exam 19: Global Economic Activity and Industry Analysis73 Questions
Exam 20: Mortgage-Backed Securities92 Questions
Select questions type


A stock is currently priced at $44 a share while the $45 call option is priced at $1.22.The call option delta is 0.86.What is the approximate call price if the stock increases in value to $45?
(Multiple Choice)
4.9/5  (96)
(96) Which two of the following are key to making SPX options an easy choice as a hedge against an equity portfolio?
I.European style
II.American style
III.trade in whole or partial contracts
IV.cash settlement
(Multiple Choice)
5.0/5 (84)
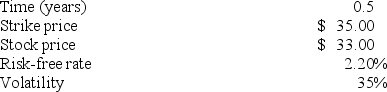
(84) What is the put option premium given the following information?
(Multiple Choice)
4.7/5 (80)
(80) An increase in which two of the following will have a negative effect on the value of a put option?
I.risk-free interest rate
II.time to option maturity
III.underlying stock price
IV.option strike price
(Multiple Choice)
4.9/5 (80)
(80) Which one of the following inputs for the Black-Scholes model is NOT directly observable?
(Multiple Choice)
4.9/5 (81)
(81) Given a set of variables,the Black-Scholes option pricing formula has a put option delta of -0.154.What is the call delta given these same variables?
(Multiple Choice)
4.8/5 (72)
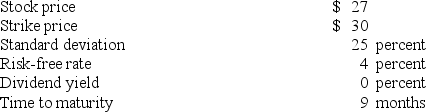
(72) What is the put option premium given the following information?
(Multiple Choice)
4.8/5 (96)
(96) A stock with a current price of $37 will either move up by a factor of 1.20 or down by a factor of 0.80 each period over the next two periods.The risk-free rate of interest is 4 percent.What is the current value of a call option with a strike price of $40?
(Multiple Choice)
4.9/5 (74)
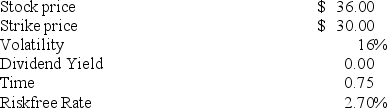
(74) What is the call option premium given the following information?
(Multiple Choice)
4.8/5 (81)
(81) Which one of the following best describes the graphical relationship between stock prices and option prices?
(Multiple Choice)
4.8/5 (84)
(84) You own 5,000 shares of Miller stock which is currently valued at $37 a share.The $40 put has a premium of $2.30 and a put delta of -0.25.What position should you take in $40 put contracts to hedge your stock against a $1 decrease in price?
(Multiple Choice)
4.8/5 (73)
(73) A stock is currently priced at $35 a share while the $40 put option is priced at $5.22.The put option delta is -0.14.What is the approximate put price if the stock increases in value to $38?
(Multiple Choice)
4.7/5 (84)
(84) Which one of the following terms is used as a shortcut means of saying "time to maturity"?
(Multiple Choice)
4.8/5 (81)
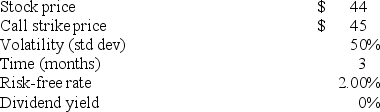
(81) What is the call option premium given the following information?
(Multiple Choice)
4.8/5 (78)
(78) Which one of the following inputs is included in the Black-Scholes-Merton model but not in the Black-Scholes model?
(Multiple Choice)
4.7/5 (82)
(82) Which one of the following is defined as an estimate of stock price volatility obtained from an option price?
(Multiple Choice)
4.8/5 (67)
(67) Which one of the following is another term for implied volatility?
(Multiple Choice)
4.9/5 (80)
(80) Employee stock options grant an employee which one of the following rights?
(Multiple Choice)
4.9/5 (81)
(81) A stock with a current price of $25 will either move up to $32 or down to $20 over the next period.The risk-free rate of interest is 3.5 percent.What is the value of a call option with a strike price of $30?
(Multiple Choice)
5.0/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)