



 Chat with AI
Exam 13: Performance Evaluation and Risk Management

Exam 1: A Brief History of Risk and Return104 Questions
Exam 2: The Investment Process100 Questions
Exam 3: Overview of Security Types94 Questions
Exam 4: Mutual Funds and Other Investment Companies107 Questions
Exam 5: The Stock Market107 Questions
Exam 6: Common Stock Valuation111 Questions
Exam 7: Stock Price Behavior and Market Efficiency83 Questions
Exam 8: Behavioral Finance and the Psychology of Investing84 Questions
Exam 9: Interest Rates103 Questions
Exam 10: Bond Prices and Yields100 Questions
Exam 11: Diversification and Risky Asset Allocation88 Questions
Exam 12: Return,Risk,and the Security Market Line88 Questions
Exam 13: Performance Evaluation and Risk Management96 Questions
Exam 14: Futures Contracts100 Questions
Exam 15: Stock Options104 Questions
Exam 16: Option Valuation74 Questions
Exam 17: Projecting Cash Flow and Earnings105 Questions
Exam 18: Corporate and Government Bonds112 Questions
Exam 19: Global Economic Activity and Industry Analysis73 Questions
Exam 20: Mortgage-Backed Securities92 Questions
Select questions type


Which one of the following is the best indication that a security is correctly priced according to the Capital Asset Pricing Model?

Free
(Multiple Choice)
4.8/5  (82)
(82) Correct Answer: Verified
C
Your portfolio has a standard deviation of 12.3 percent and an average return of 9.6 percent.You have a 5 percent probability of losing ________ percent or more in any given year. 
Free
(Multiple Choice)
4.7/5 (79)
(79) Correct Answer:Verified
VerifiedD
Which one of the following concerns a money manager's control over investment risks,particularly potential short-run losses?
Free
(Multiple Choice)
4.9/5 (74)
(74) Correct Answer:Verified
VerifiedC
Mike's portfolio has a two-year expected return of 21.70 percent.What is the expected return for one year?
(Multiple Choice)
4.9/5 (76)
(76) The U.S.Treasury bill is yielding 2.5 percent and the market has an expected return of 9.0 percent.What is the Sharpe ratio of a portfolio that has a beta of 1.25 and a variance of 0.0218?
(Multiple Choice)
4.8/5 (81)
(81) A portfolio consists of the following two funds. 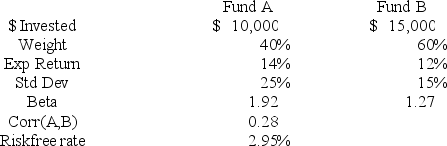 What is the Sharpe ratio of the portfolio?
 (Multiple Choice)
4.9/5 (79)
(79) What is the Treynor ratio of a portfolio comprised of 40 percent portfolio A,25 percent portfolio B,and The risk-free rate is 2.5 percent and the market risk premium is 8.4 percent. 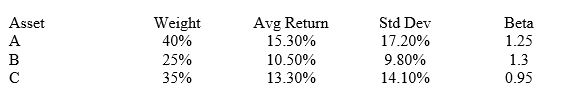
(Multiple Choice)
4.9/5 (82)
(82) You have a portfolio which has an average return of 10.3 percent.In any given year,you have a 2.5 percent probability of earning either a zero or a negative annual return.What is the approximate standard deviation of your portfolio?

(Multiple Choice)
4.9/5 (82)
(82) A portfolio has an average return of 9.7 percent,a standard deviation of 8.6 percent,and a beta of 0.72.The risk-free rate is 2.1 percent.What is the Treynor ratio?
(Multiple Choice)
4.7/5 (72)
(72) A portfolio has a beta of 1.25 and an actual return of 13.0 percent.The risk-free rate is 4.50 percent and the market risk premium is 8.2 percent.What is the value of Jensen's alpha?
(Multiple Choice)
4.9/5 (73)
(73) The risk premium of a portfolio divided by the portfolio's standard deviation defines which one of the following performance measures?
(Multiple Choice)
4.8/5 (89)
(89) Your portfolio has an expected annual return of 11.6 percent.What is the two-year expected return?
(Multiple Choice)
4.9/5 (78)
(78) What is Jensen's alpha of a portfolio comprised of 45 percent portfolio A and 55 percent of portfolio B?
 The risk-free rate is 3.1 percent and the market risk premium is 6.8 percent.
 (Multiple Choice)
4.8/5 (79)
(79) Which one of the following correctly states the VaR for a 3-year period with a 2.5 percent probability?
(Multiple Choice)
4.9/5 (83)
(83) Your portfolio has a standard deviation of 11.7 percent.What is the two-year standard deviation?
(Multiple Choice)
4.9/5 (80)
(80) Your portfolio actually earned 6.2 percent for the year.You were expecting to earn 8.6 percent based on the CAPM formula.What is Jensen's alpha if the portfolio standard deviation is 12.1 percent and the beta is 0.93?
(Multiple Choice)
4.9/5 (81)
(81) A portfolio consists of the following two funds.  What is the Sharpe ratio of the portfolio?
 (Multiple Choice)
5.0/5 (78)
(78) A portfolio has a variance of 0.04050,a beta of 1.60,and an expected return of 14.3 percent.What is the Treynor ratio if the expected risk-free rate is 5.5 percent?
(Multiple Choice)
4.9/5 (73)
(73) You are comparing three assets which have differing Treynor ratios.Given this,which one of the following must be true?
(Multiple Choice)
4.8/5 (83)
(83) What is the Treynor ratio of a portfolio comprised of 40 percent portfolio A,25 percent portfolio B,and 35 percent portfolio C?
 The risk-free rate is 2.9 percent and the market risk premium is 8.6 percent.
 (Multiple Choice)
4.9/5 (97)
(97) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)