



 Chat with AI
Exam 16: Option Valuation

Exam 1: A Brief History of Risk and Return104 Questions
Exam 2: The Investment Process100 Questions
Exam 3: Overview of Security Types94 Questions
Exam 4: Mutual Funds and Other Investment Companies107 Questions
Exam 5: The Stock Market107 Questions
Exam 6: Common Stock Valuation111 Questions
Exam 7: Stock Price Behavior and Market Efficiency83 Questions
Exam 8: Behavioral Finance and the Psychology of Investing84 Questions
Exam 9: Interest Rates103 Questions
Exam 10: Bond Prices and Yields100 Questions
Exam 11: Diversification and Risky Asset Allocation88 Questions
Exam 12: Return,Risk,and the Security Market Line88 Questions
Exam 13: Performance Evaluation and Risk Management96 Questions
Exam 14: Futures Contracts100 Questions
Exam 15: Stock Options104 Questions
Exam 16: Option Valuation74 Questions
Exam 17: Projecting Cash Flow and Earnings105 Questions
Exam 18: Corporate and Government Bonds112 Questions
Exam 19: Global Economic Activity and Industry Analysis73 Questions
Exam 20: Mortgage-Backed Securities92 Questions
Select questions type


The VIX is a measure of which one of the following?

Free
(Multiple Choice)
5.0/5  (77)
(77) Correct Answer: Verified
B
Which one of the following statements concerning option prices is correct?
Free
(Multiple Choice)
4.9/5 (85)
(85) Correct Answer:Verified
VerifiedA
You have been granted stock options on 300 shares of your employer's stock.The stock is currently selling for $37.80 and has a standard deviation of 30 percent.The option's strike price is $35 and the time to maturity is 10 years.What is the value of each option given a risk-free rate of 3.0 percent? Assume that no dividends are paid.
Free
(Multiple Choice)
4.8/5 (60)
(60) Correct Answer:Verified
VerifiedD
Which one of the following situations will produce the highest put price,all else constant? Assume the options are all in-the-money.
(Multiple Choice)
5.0/5 (95)
(95) Which one of the following situations will produce the highest call price,all else constant?
(Multiple Choice)
4.9/5 (93)
(93) You own 800 shares of Bradley Co.stock that is currently priced at $33 a share.Given this price,the option delta for a $35 call option on this stock is 0.66.How many $35 call options do you need to hedge against a -$1 change in the price of the stock?
(Multiple Choice)
4.8/5 (85)
(85) Which one of the following statements concerning the relationship between time to option maturity and call and put prices is correct?
(Multiple Choice)
4.8/5 (73)
(73) Which two of the following have the greatest effect on stock option prices?
I.volatility of underlying stock price
II.time to option maturity
III.underlying stock price
IV.option strike price
(Multiple Choice)
4.7/5 (72)
(72) VIX represents the volatility index on which one of the following?
(Multiple Choice)
5.0/5 (92)
(92) Delta measures the dollar impact of a change in which one of the following on the value of a stock option?
(Multiple Choice)
4.8/5 (79)
(79) How frequently should you consider rebalancing the options hedge on a large equity portfolio if you wish to maintain an effective hedge?
(Multiple Choice)
4.9/5 (80)
(80) Which one of the following statements concerning the relationship between the volatility of the underlying stock price,as measured by sigma (σ),and call and put prices is correct?
(Multiple Choice)
4.9/5 (78)
(78) Laura has an equity portfolio valued at $11.25 million that has a beta of 1.27.She has decided to hedge this portfolio using SPX call option contracts.The S&P 500 index is currently 1502.The option delta is 0.543.How many option contracts must Laura write to effectively hedge her portfolio?
(Multiple Choice)
4.8/5 (85)
(85) You know that a call will finish in-the-money.Based on that single piece of information,you also know which one of the following?
(Multiple Choice)
4.9/5 (76)
(76) Which option price(s)will increase when the interest rate increases?
(Multiple Choice)
4.9/5 (87)
(87) An increase in which one of the following will have a negative effect on the price of a call option?
(Multiple Choice)
4.9/5 (87)
(87) Which of the following are typical characteristics of employee stock options?
I.originally issued with 10-year life
II.right to purchase stock at a designated price
III.exchange-traded
IV.vesting period
(Multiple Choice)
4.7/5 (76)
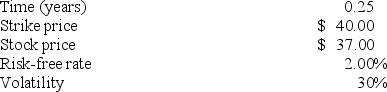
(76) What is the put option premium given the following information?
(Multiple Choice)
4.7/5 (82)
(82) You have an equity portfolio valued at $1.55 million that has a beta of 1.21.You have decided to hedge this portfolio using SPX call option contracts.The S&P 500 index is currently 1457.The option delta is 0.6435.How many option contracts must you write to effectively hedge your portfolio?
(Multiple Choice)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)