



 Chat with AI
Exam 5: Extreme Markets I: Perfect Competition

Exam 1: Reasoning With Economics: Models and Information75 Questions
Exam 2: Transactions and Institutions: the Building Blocks80 Questions
Exam 3: Markets76 Questions
Exam 4: Cost and Production67 Questions
Exam 5: Extreme Markets I: Perfect Competition68 Questions
Exam 6: Extreme Markets II: Monopoly69 Questions
Exam 7: Between the Extremes: Interaction and Strategy66 Questions
Exam 8: Competition and Strategy70 Questions
Exam 9: Beyond Markets; Property and Contracts67 Questions
Exam 10: The Economics of Contracts67 Questions
Exam 11: Risk and Information in Contracts67 Questions
Exam 12: Organizations in Concept and Practice67 Questions
Exam 13: Organizational Design64 Questions
Exam 14: Vertical Relationships66 Questions
Exam 15: Employment Relationships69 Questions
Exam 16: Time, Risk and Options73 Questions
Exam 17: Conflict, Negotiation and Group Choice68 Questions
Select questions type


Was the U.S.government able to control the world petroleum prices? Support your choice with suitable reasons.
(Essay)
4.7/5  (75)
(75) The long-run supply curve of a perfectly competitive market is a:
(Multiple Choice)
4.9/5 (78)
(78) The following table gives the average cost of production for three different categories of firms producing the same product.
Type of firme No. of firms Awerane sostper unit Equilibrium output A 350 \ 3 10 units B 400 \ 5 10 units C 550 \ 10 10 units
-Refer to Table .Suppose the price level in the market is at $6 per unit and the quantity demanded is 3,500 units.However, an increase in the fuel costs drives up the variable cost incurred by both Type A and Type B firms by $2.50 per unit.Which of the following situations will arise?
(Multiple Choice)
5.0/5 (73)
(73) The long-run supply curve of a market for eggs is perfectly inelastic.
(True/False)
4.8/5 (67)
(67) When will the long-run supply curve of a perfectly competitive market shift upward?
(Essay)
4.8/5 (88)
(88) If firms in a perfectly competitive market have dissimilar cost curves what will be the shape of the long-run supply curve?
(Essay)
4.8/5 (77)
(77) Describe the long-run adjustment to a change in demand in a perfectly competitive market where firms operate with two types of cost structures.
(Essay)
4.9/5 (80)
(80)
Given below is a perfectly competitive firm under long run equilibrium.AC and MC represent the average cost and the marginal cost incurred by the firm.P₀ is the equilibrium price level while Q₀ is the equilibrium output.
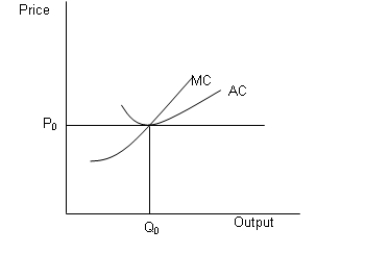 -Refer to Figure .Suppose the cost of raw materials used in production increases.Which of the following changes will be observed?
 (Multiple Choice)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)