



 Chat with AI
Exam 5: Extreme Markets I: Perfect Competition

Exam 1: Reasoning With Economics: Models and Information75 Questions
Exam 2: Transactions and Institutions: the Building Blocks80 Questions
Exam 3: Markets76 Questions
Exam 4: Cost and Production67 Questions
Exam 5: Extreme Markets I: Perfect Competition68 Questions
Exam 6: Extreme Markets II: Monopoly69 Questions
Exam 7: Between the Extremes: Interaction and Strategy66 Questions
Exam 8: Competition and Strategy70 Questions
Exam 9: Beyond Markets; Property and Contracts67 Questions
Exam 10: The Economics of Contracts67 Questions
Exam 11: Risk and Information in Contracts67 Questions
Exam 12: Organizations in Concept and Practice67 Questions
Exam 13: Organizational Design64 Questions
Exam 14: Vertical Relationships66 Questions
Exam 15: Employment Relationships69 Questions
Exam 16: Time, Risk and Options73 Questions
Exam 17: Conflict, Negotiation and Group Choice68 Questions
Select questions type


Why do economists prefer to use the model of perfect competition in most economic analysis?
(Essay)
4.9/5  (90)
(90)
In the figure given below, D₁ and D₂ represent the demand curves for land before and after the ethanol program respectively.SRS is the short-run supply curve of land.
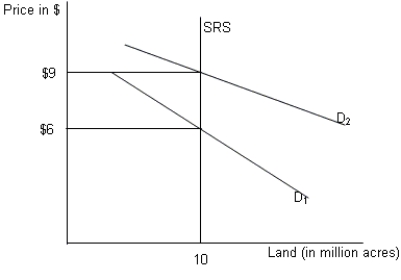 -Refer to Figure .What will be the impact of the ethanol program on the long-run equilibrium price level for land suitable for corn cultivation?
 (Multiple Choice)
4.9/5 (87)
(87) Firms in a perfectly competitive market usually enter or leave an industry in the short-run and not in the long-run.
(True/False)
4.7/5 (89)
(89) When the existing firms in a competitive industry have different operating costs:
(Multiple Choice)
4.7/5 (83)
(83)
In the figure given below MC denotes the marginal cost and AC denotes the average cost of a firm under perfect competition.
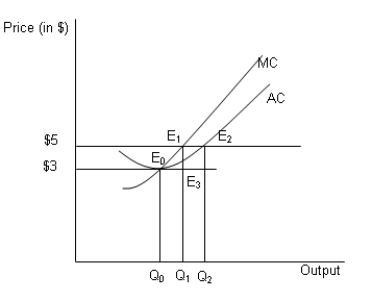 -Refer to Figure .When the demand increases to Q₁, in the short run the firm will be:
 (Multiple Choice)
4.8/5 (81)
(81) When a perfectly competitive firm is in long-run equilibrium, it and all other firms are on the lowest point of their average cost curves.
(True/False)
4.8/5 (79)
(79) In the market for oranges, availability of substitutes limits a single seller's power over price.
(True/False)
4.9/5 (76)
(76)
In the figure given below MC denotes the marginal cost and AC denotes the average cost of a firm under perfect competition.
-Refer to Figure .What will be the effect of the increase in demand (from Q₀ to Q₁) on the short run supply curve?
-Refer to Figure .What will be the effect of the increase in demand (from Q₀ to Q₁) on the short run supply curve? (Multiple Choice)
5.0/5 (78)
(78) Which of the following conditions define the short-run for any industry?
(Multiple Choice)
4.9/5 (100)
(100)
In the figure given below MC denotes the marginal cost and AC denotes the average cost of a firm under perfect competition.
-Refer to Figure .What will be the long run effect of the increase in demand (from Q₀ to Q₁) in this market?
-Refer to Figure .What will be the long run effect of the increase in demand (from Q₀ to Q₁) in this market? (Multiple Choice)
4.9/5 (94)
(94)
In the figure given below MC denotes the marginal cost and AC denotes the average cost of a firm under perfect competition.
-Refer to Figure .Suppose the demand for the commodity increases to Q₁, what will be the effect on the price level in the short run?
-Refer to Figure .Suppose the demand for the commodity increases to Q₁, what will be the effect on the price level in the short run? (Multiple Choice)
4.7/5 (83)
(83)
In the figure given below, D₁ and D₂ represent the demand curves for land before and after the ethanol program respectively.SRS is the short-run supply curve of land.
-Refer to Figure .What will be the shape of the long-run supply curve of land suitable for corn farming?
-Refer to Figure .What will be the shape of the long-run supply curve of land suitable for corn farming? (Multiple Choice)
4.8/5 (75)
(75) How is the short-run supply curve of a perfectly competitive market different from the long-run supply curve?
(Essay)
4.9/5 (93)
(93) If the cost of production of the firms in a perfectly competitive market differs the resulting long-run supply curve will be an upward rising step function.
(True/False)
4.8/5 (84)
(84) Assume that buyers are aware of the similarities between the products sold by two dairy farms.The dairy producers can still practice price discrimination through advertisement and salesmanship.
(True/False)
4.8/5 (86)
(86) The following table gives the average cost of production for three different categories of firms producing the same product.
Type of firme No. of firms Awerane sostper unit Equilibrium output A 350 \ 3 10 units B 400 \ 5 10 units C 550 \ 10 10 units
-Refer to Table .Suppose the demand for the commodity rises from 3,200 units to 3,500 units and the market price increases to $5.Which of the following situations will be observed?
(Multiple Choice)
4.7/5 (64)
(64) In the long run, producers do not incur any fixed cost as all inputs are variable.
(True/False)
4.9/5 (79)
(79) State two characteristics of the long-run equilibrium under perfect competition.
(Essay)
4.9/5 (72)
(72) Suppose a legislation passed by the government encourages domestic oil exploration thereby reducing petroleum imports substantially.If the cost of production is uniform for all producers, which of the following will be observed in the petroleum market?
(Multiple Choice)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)