



 Chat with AI
Exam 5: Extreme Markets I: Perfect Competition

Exam 1: Reasoning With Economics: Models and Information75 Questions
Exam 2: Transactions and Institutions: the Building Blocks80 Questions
Exam 3: Markets76 Questions
Exam 4: Cost and Production67 Questions
Exam 5: Extreme Markets I: Perfect Competition68 Questions
Exam 6: Extreme Markets II: Monopoly69 Questions
Exam 7: Between the Extremes: Interaction and Strategy66 Questions
Exam 8: Competition and Strategy70 Questions
Exam 9: Beyond Markets; Property and Contracts67 Questions
Exam 10: The Economics of Contracts67 Questions
Exam 11: Risk and Information in Contracts67 Questions
Exam 12: Organizations in Concept and Practice67 Questions
Exam 13: Organizational Design64 Questions
Exam 14: Vertical Relationships66 Questions
Exam 15: Employment Relationships69 Questions
Exam 16: Time, Risk and Options73 Questions
Exam 17: Conflict, Negotiation and Group Choice68 Questions
Select questions type


The following table gives the average cost of production for three different categories of firms producing the same product.
Type of firme No. of firms Awerane sostper unit Equilibrium output A 350 \ 3 10 units B 400 \ 5 10 units C 550 \ 10 10 units
-Refer to Table .Suppose initially 3,200 units are demanded at a price of $3 per unit.What will be the quantity of output supplied by each type of firm in the market?
(Multiple Choice)
4.9/5  (80)
(80) If there are only a few producers of substitutes for Good X, a merger between producers of Good X and any one of them could significantly _____ for Good X.
(Multiple Choice)
4.8/5 (90)
(90) A fall in demand for a commodity in a perfectly competitive market will shift the long-run supply curve to the right.
(True/False)
4.8/5 (83)
(83) Even when two goods are perfect substitutes one can sell at a premium over the other depending on the tastes and preferences of the consumers.
(True/False)
4.9/5 (81)
(81) Which of the following is true in a perfectly competitive market?
(Multiple Choice)
4.8/5 (69)
(69) The economists of the Federal Trade Commission suggested rejection of Coke's merger with Dr.Pepper as it could:
(Multiple Choice)
4.9/5 (68)
(68) Assume that a rise in petroleum prices increases the cost of milk transportation from the dairies to the market.We can expect the long-run supply curve in this industry to shift downward.
(True/False)
4.7/5 (87)
(87) In a perfectly competitive market, buyers are completely aware of the asking prices of sellers but sellers are unaware of the bids placed by buyers.
(True/False)
4.8/5 (84)
(84) The following table gives the average cost of production for three different categories of firms producing the same product.
Type of firme No. of firms Awerane sostper unit Equilibrium output A 350 \ 3 10 units B 400 \ 5 10 units C 550 \ 10 10 units
-Refer to Table .Suppose the price of the commodity increases to $8 per unit.Which of the following situations will be observed in the market?
(Multiple Choice)
4.8/5 (91)
(91) Assume that the government of a nation prohibits producers from extracting crude oil from some domestic oil fields.Which of the following will be witnessed in the market for crude oil?
(Multiple Choice)
4.7/5 (71)
(71) Which of the following conditions define a perfectly competitive market?
(Multiple Choice)
4.9/5 (75)
(75) Economists consider the model of perfect competition useful because:
(Multiple Choice)
4.8/5 (74)
(74) Which of the following commodities have a high short-run own-price elasticity of supply?
(Multiple Choice)
4.9/5 (81)
(81)
Given below is a perfectly competitive firm under long run equilibrium.AC and MC represent the average cost and the marginal cost incurred by the firm.P₀ is the equilibrium price level while Q₀ is the equilibrium output.
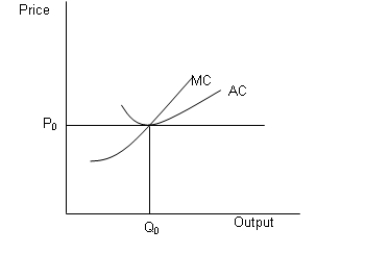 -Refer to Figure 5-2.What will be the impact of the rise in raw materials cost on the long-run supply curve of this industry?
 (Multiple Choice)
4.9/5 (89)
(89) Suppose the cost of raw materials used by the cotton industry rises to a larger extent compared to the increase in demand in the market.Which of the following situations will arise?
(Multiple Choice)
4.8/5 (84)
(84) Which of the following situations resulted from the North American Free Trade Agreement (NAFTA)?
(Multiple Choice)
4.8/5 (79)
(79) A(n) _____ perceives the demand for its own output as horizontal at the market price, so it can produce as much or as little as it wants without affecting that price.
(Multiple Choice)
4.7/5 (68)
(68) In a perfectly competitive market, the demand curve faced by each firm is:
(Multiple Choice)
4.8/5 (84)
(84) What is the short-run breakeven point of operation in a perfectly competitive market?
(Essay)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)