



 Chat with AI
Exam 8: Technology,Production,and Costs

Exam 1: Economics: Foundations and Models459 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System495 Questions
Exam 3: Where Prices Come From: The Interaction of Demand and Supply476 Questions
Exam 4: Market Efficiency and Market Failure464 Questions
Exam 5: The Economics of Health Care337 Questions
Exam 6: Firms, The Stock Market, and Corporate Governance456 Questions
Exam 7: Consumer Choice and Elasticity384 Questions
Exam 8: Technology,Production,and Costs274 Questions
Exam 9: Firms in Perfectly Competitive Markets297 Questions
Exam 10: Monopoly and Antitrust Policy279 Questions
Exam 11: Monopolistic Competition and Oligopoly410 Questions
Exam 12: GDP: Measuring Total Production and Income261 Questions
Exam 13: Unemployment and Inflation290 Questions
Exam 14: Economic Growth, The Financial System, and Business Cycles251 Questions
Exam 15: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 16: Money,Banks,and the Federal Reserve System278 Questions
Exam 17: Monetary Policy280 Questions
Exam 18: Fiscal Policy292 Questions
Exam 19: Comparative Advantage, International Trade, and Exchange Rates443 Questions
Select questions type


Table 8-6
Quantity of workers Quantity of foot massages per day Fixed cost Variable cost Total cost Average total cost Marginal cost 0 0 1 10 2 25 3 45 4 60 5 70
-Refer to Table 8-6.Alicia Gregory owns a foot massage business.She leases 4 computer-controlled massage booths,for which she pays $125 per day.She cannot increase the number machines she leases without giving the manufacturer 3 months notice.She can hire as many workers as she wants at a cost of $75 per day per worker.These are the only two inputs she uses in her business.Use this information to fill in the columns in the above table.
(Essay)
5.0/5  (77)
(77) Figure 8-3
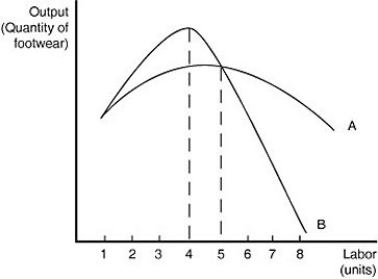 Fancy Footwear manufactures shoes. Figure 8-3 shows Fancy Footwear's marginal product of labor and average product of labor curves in the short run.
-Refer to Figure 8-3.For what quantity of labor does production start to display diminishing returns?
Fancy Footwear manufactures shoes. Figure 8-3 shows Fancy Footwear's marginal product of labor and average product of labor curves in the short run.
-Refer to Figure 8-3.For what quantity of labor does production start to display diminishing returns? (Multiple Choice)
4.9/5 (88)
(88) In the short run,marginal product of labor increases at first and then falls because
(Multiple Choice)
4.8/5 (83)
(83) If production displays diseconomies of scale,the long-run average cost curve is
(Multiple Choice)
4.9/5 (70)
(70) If marginal cost is above the average variable cost,then average variable cost is decreasing.
(True/False)
4.8/5 (76)
(76) Table 8-1
Number of Workers Mushrooms per Day (pounds) 1 12 2 30 3 45 4 50 5 54 6 56 Table 8-1 shows the technology of production at the Matsuko's Mushroom Farm for the month of May.
-Refer to Table 8-1.Diminishing marginal returns sets in when the ________ worker is hired.
(Multiple Choice)
4.9/5 (78)
(78) The processes a firm uses to turn inputs into outputs of goods and services is called
(Multiple Choice)
4.8/5 (77)
(77) Consider a manufacturing operation that uses specialized machinery and labor to produce its output.In this case,the input that is not fixed in the short run is labor.
(True/False)
4.8/5 (74)
(74) What is the difference between explicit costs and implicit costs? List three examples each of explicit costs and implicit costs that may be experienced by a small business.
(Essay)
4.8/5 (79)
(79) If the long-run average total cost curve is downward-sloping,then the firm is experiencing decreasing returns to scale.
(True/False)
4.7/5 (69)
(69) In economics,what is the difference between the short run and the long run?
(Essay)
4.9/5 (89)
(89) Figure 8-11
 Figure 8-11 illustrates the long-run average cost curve for a firm that produces picture frames. The graph also includes short-run average cost curves for three firm sizes: ATCₐ, ATCb and ATCc.
-Refer to Figure 8-11.If the firm chooses to produce and sell 25,000 frames per month by operating in the short run with a scale operation represented by ATCc
Figure 8-11 illustrates the long-run average cost curve for a firm that produces picture frames. The graph also includes short-run average cost curves for three firm sizes: ATCₐ, ATCb and ATCc.
-Refer to Figure 8-11.If the firm chooses to produce and sell 25,000 frames per month by operating in the short run with a scale operation represented by ATCc (Multiple Choice)
4.9/5 (86)
(86) If a firm experiences diminishing returns its marginal product must be negative.
(True/False)
4.7/5 (70)
(70) Table 8-7
Quantity of Lanterns Fixed Cost (dollars) Variable Cost (dollars) Total Cost (dollars) Average Total Cost (dollars) 75 200 170 370 4.93 80 200 230 430 5.36 90 200 7.67 100 200 810 11.8 115 200 12.5 117 200 1264 1464 120 200 1480 Table 8-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 8-7.What is the variable cost of production when the firm produces 115 lanterns?
(Multiple Choice)
4.8/5 (83)
(83) In the short run,if the marginal product is at its maximum,then the
(Multiple Choice)
4.9/5 (88)
(88) Figure 8-6
 Figure 8-6 contains information about the short run cost structure of a firm.
-Refer to Figure 8-6.In the figure above,which letter represents the average fixed cost curve?
Figure 8-6 contains information about the short run cost structure of a firm.
-Refer to Figure 8-6.In the figure above,which letter represents the average fixed cost curve? (Multiple Choice)
4.9/5 (85)
(85) Is it possible for technological change to be negative? If so,give an example.
(Essay)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)