



 Chat with AI
Exam 9: Firms in Perfectly Competitive Markets


Max Shreck,an accountant,quit his $80,000-a-year job and bought an existing tattoo parlor from its previous owner,Sylvia Sidney.The lease has five years remaining and requires a monthly payment of $4,000.The lease

 (86)
 Verified
A
If a perfectly competitive firm achieves productive efficiency then
(99) VerifiedD
Figure 9-18
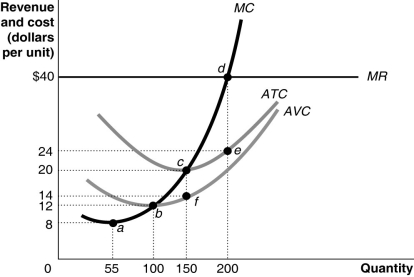 -Refer to Figure 9-18.Use the figure above to answer the following questions.
a.How can you determine that the figure represents a graph of a perfectly competitive firm? Be specific; indicate which curve gives you the information and how you use this information to arrive at your conclusion.
b.What is the market price?
c.What is the profit-maximizing output?
d.What is total revenue at the profit-maximizing output?
e.What is the total cost at the profit-maximizing output?
f.What is the profit or loss at the profit-maximizing output?
g.What is the firm's total fixed cost?
h.What is the total variable cost?
i.Identify the firm's short-run supply curve.
j.Is the industry in a long-run equilibrium?
k.If it is not in long-run equilibrium,what will happen in this industry to restore long-run equilibrium?
l.In long-run equilibrium,what is the firm's profit maximizing quantity?
-Refer to Figure 9-18.Use the figure above to answer the following questions.
a.How can you determine that the figure represents a graph of a perfectly competitive firm? Be specific; indicate which curve gives you the information and how you use this information to arrive at your conclusion.
b.What is the market price?
c.What is the profit-maximizing output?
d.What is total revenue at the profit-maximizing output?
e.What is the total cost at the profit-maximizing output?
f.What is the profit or loss at the profit-maximizing output?
g.What is the firm's total fixed cost?
h.What is the total variable cost?
i.Identify the firm's short-run supply curve.
j.Is the industry in a long-run equilibrium?
k.If it is not in long-run equilibrium,what will happen in this industry to restore long-run equilibrium?
l.In long-run equilibrium,what is the firm's profit maximizing quantity? (73) Verifieda∙The perfectly competitive firm is a price taker and therefore faces a perfectly elastic demand curve which is also the MR curve.
b∙Market price = $40
c∙Profit maximizing output = 200
d∙Total revenue = $40 × 200 = $8,000
e∙Total cost = ATC × total output = $24 × 200 = $4,800
f∙Profit = Total revenue - total cost = $8,000 - 4,800 = $3,200
g∙Total fixed cost = AFC × total output = (ATC - AVC)× 150 = $6 × 150 = $900.(Note: fixed cost has the same value at all output rates)
h∙The total variable cost at the profit maximizing output level = ($4,800 - 900)= $3,900
i∙The firm's short run supply curve is its MC curve above minimum AVC (from point b and above).
j∙No,the industry is not in a long-run equilibrium because the firm earns an economic profit.
k∙Some firms will enter the industry,causing the industry supply curve to shift rightward.This causes market price to fall.Entry stops when economic profits are eliminated and all firms break even.
l∙In the long-run equilibrium the firm's profit maximizing quantity = 150,where price will equal marginal cost.
The price a perfectly competitive firm receives for its output
(80) Of the following industries,which are perfectly competitive? For those that are not perfectly competitive,explain why.
a.Restaurants
b.Corn
c.College education
d.Local radio and television
(85) Figure 9-6
 Figure 9-6 shows the demand, marginal cost (MC) and average total cost (ATC) curves for Jason's House of Apples.
-Refer to Figure 9-6.If Jason maximizes his profit he will produce the output level indicated by point ________ and his average profit will equal ________.
Figure 9-6 shows the demand, marginal cost (MC) and average total cost (ATC) curves for Jason's House of Apples.
-Refer to Figure 9-6.If Jason maximizes his profit he will produce the output level indicated by point ________ and his average profit will equal ________. (66) Assume that firms in a perfectly competitive market are earning economic profits.Which of the following statements describes the change in market price and output as a result of the entry of new firms into this market?
(73) Which of the following describes a difference between allocative efficiency and productive efficiency in a perfectly competitive market?
(78) Refer to Table 9-3.What will Arnie's output be and how much profit will he earn if the market price of basketballs is $5.00?
(100) An increase in a firm's fixed cost will not change the firm's profit-maximizing output in the short run.
(80) Figure 9-6
Figure 9-6 shows the demand, marginal cost (MC) and average total cost (ATC) curves for Jason's House of Apples.
-Refer to Figure 9-6.Jason is currently producing 20 thousand pounds of apples.To maximize his profit Jason should
Figure 9-6 shows the demand, marginal cost (MC) and average total cost (ATC) curves for Jason's House of Apples.
-Refer to Figure 9-6.Jason is currently producing 20 thousand pounds of apples.To maximize his profit Jason should (88) Figure 9-5
 Figure 9-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 9-5.The firm's manager suggests that the firm's goal should be to maximize average profit.If the firm does this,what is the amount of profit that it will earn?
Figure 9-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 9-5.The firm's manager suggests that the firm's goal should be to maximize average profit.If the firm does this,what is the amount of profit that it will earn? (87) Figure 9-5
Figure 9-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 9-5.If the market price is $20,what is the firm's profit-maximizing output?
Figure 9-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 9-5.If the market price is $20,what is the firm's profit-maximizing output? (75) Figure 9-1
 -Refer to Figure 9-1.If the firm is producing 700 units,what is the amount of its profit or loss?
 (75) Mark Frost grows apples in a perfectly competitive market.If we drew a line in a graph that illustrates Mark's total revenue from selling apples,it would be
(82) Figure 9-5
Figure 9-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 9-5.The figure shows the cost structure of a firm in a perfectly competitive market.If the firm's fixed cost increases by $1,000 due to a new environmental regulation,what happens to its profit-maximizing output level?
Figure 9-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 9-5.The figure shows the cost structure of a firm in a perfectly competitive market.If the firm's fixed cost increases by $1,000 due to a new environmental regulation,what happens to its profit-maximizing output level? (90) If,in a perfectly competitive industry,the market price facing a firm is above its average total cost at the output where marginal revenue equals marginal cost,then
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)