



 Chat with AI
Exam 9: Inventory Costing and Capacity Analysis

Exam 1: The Manager and Management Accounting195 Questions
Exam 2: An Introduction to Cost Terms and Purposes224 Questions
Exam 3: Cost-Volume-Profit Analysis211 Questions
Exam 4: Job Costing203 Questions
Exam 5: Activity-Based Costing and Activity-Based Management176 Questions
Exam 6: Master Budget and Responsibility Accounting226 Questions
Exam 7: Flexible Budgets, Direct-Cost Variances, and Management Control181 Questions
Exam 8: Flexible Budgets, Overhead Cost Variances, and Management Control176 Questions
Exam 9: Inventory Costing and Capacity Analysis210 Questions
Exam 10: Determining How Costs Behave192 Questions
Exam 11: Decision Making and Relevant Information218 Questions
Exam 12: Strategy, Balanced Scorecard, and Strategic Profitability Analysis172 Questions
Exam 13: Pricing Decisions and Cost Management210 Questions
Exam 14: Cost Allocation, Customer-Profitability Analysis, and Sales-Variance Analysis167 Questions
Exam 15: Allocation of Support-Department Costs, Common Costs, and Revenues150 Questions
Exam 16: Cost Allocation: Joint Products and Byproducts151 Questions
Exam 17: Process Costing149 Questions
Exam 18: Spoilage, Rework, and Scrap153 Questions
Exam 19: Balanced Scorecard: Quality and Time150 Questions
Exam 20: Inventory Management, Just-in-Time, and Simplified Costing Methods150 Questions
Exam 21: Capital Budgeting and Cost Analysis151 Questions
Exam 22: Management Control Systems, Transfer Pricing, and Multinational Considerations151 Questions
Exam 23: Performance Measurement, Compensation, and Multinational Considerations150 Questions
Select questions type


When actual production is below practical capacity, there will be unused-capacity cost only in the manufacturing function while unused capacity is not a factor in nonmanufacturing links of the value chair such as in the marketing function.
(True/False)
4.8/5  (74)
(74) The contribution-margin format of the income statement is used with absorption costing.
(True/False)
5.0/5 (95)
(95) Which of the following costs is inventoried when using variable costing?
(Multiple Choice)
4.8/5 (84)
(84) Jupiter Corporation incurred fixed manufacturing costs of $19,000 during 2017. Other information for 2017 includes:
The budgeted denominator level is 2,300 units.
Units produced total 2,600 units.
Units sold total 1,700 units.
Variable cost per unit is $6
Beginning inventory is zero.
The fixed manufacturing cost rate is based on the budgeted denominator level.
Under absorption costing, the production-volume variance is ________. (Round any intermediary calculations to the nearest cent and your final answer to the nearest dollar.)
(Multiple Choice)
4.7/5 (82)
(82) To reduce the undesirable incentives to build up inventories management can institute planning, budgeting, and other controls.
(True/False)
4.9/5 (86)
(86) Kennywood Inc., a manufacturing firm, is able to produce 1,000 pairs of pants per hour, at maximum efficiency. There are three eight-hour shifts each day. Due to unavoidable operating interruptions, production averages 800 units per hour. The plant actually operates only 28 days per month. Based on the current budget, Kennywood estimates that it will be able to sell only 501,000 units due to the entry of a competitor with aggressive marketing capabilities. But the demand is unlikely to be affected in future and will be around 519,000. Assume the month has 30 days.
What is the practical capacity for the month?
(Multiple Choice)
4.7/5 (78)
(78) Throughput is a variation of which of the following systems?
(Multiple Choice)
4.7/5 (87)
(87) The production-volume variance, which relates only to fixed manufacturing overhead, exists under absorption costing but not under variable costing.
(True/False)
4.9/5 (78)
(78) Using master budget capacity as the denominator level sets the cost of capacity at the cost of supplying the capacity, regardless of the demand for the capacity.
(True/False)
4.8/5 (90)
(90) Fixed manufacturing overhead is a period cost both under variable costing and under absorption costing.
(True/False)
4.9/5 (74)
(74) Adjusted allocation-rate approach restates all amounts in the general and subsidiary ledgers by using actual rather than budgeted cost rates.
(True/False)
4.8/5 (93)
(93) Swansea Finishing produces and sells a decorative pillow for $103.00 per unit. In the first month of operation, 2,300 units were produced and 1,800 units were sold. Actual fixed costs are the same as the amount budgeted for the month. Other information for the month includes:
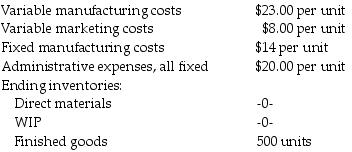 What is cost of goods sold per unit using variable costing?
 (Multiple Choice)
4.8/5 (67)
(67) Ms. Sophia Jones, the company president, has heard that there are multiple breakeven points for every product. She does not believe this and has asked you to provide the evidence of such a possibility. Some information about the company for 2017 is as follows:
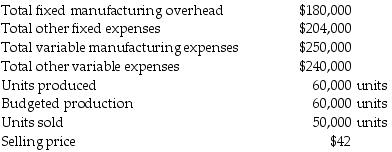 What are breakeven sales in units using absorption costing? (Round any intermediary calculations to the nearest cent and your final answer up to the next whole unit.)
 (Multiple Choice)
4.9/5 (89)
(89) ________ is the level of capacity utilization that managers expect for the current budget period, which is typically one year.
(Multiple Choice)
4.9/5 (70)
(70) The breakeven points are the same under both variable costing and absorption costing.
(True/False)
4.8/5 (71)
(71) Venus Corporation incurred fixed manufacturing costs of $6,600 during 2017. Other information for 2017 includes:
The budgeted denominator level is 1,600 units.
Units produced total 770 units.
Units sold total 600 units.
Beginning inventory was zero.
The company uses variable costing and the fixed manufacturing cost rate is based on the budgeted denominator level. Manufacturing variances are closed to cost of goods sold.
The production-volume variance totals ________.
(Multiple Choice)
4.8/5 (83)
(83) Henry Chapman Manufacturing Inc. incurred the following expenses during 2017:
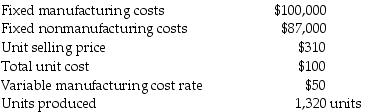 What will be the breakeven point if variable costing is used? (Round your final answer up to the next whole unit.)
 (Multiple Choice)
4.8/5 (71)
(71) ________ method includes fixed manufacturing overhead costs as inventoriable costs.
(Multiple Choice)
4.8/5 (81)
(81) Time Again, LLC produces and sells a mantel clock for $100 per unit. In 2017, 42,125 clocks were produced and 37,958 were sold. Other information for the year includes:
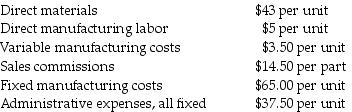 What is the inventoriable cost per unit using variable costing?
 (Multiple Choice)
4.8/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)