



 Chat with AI
Exam 23: Audit of Cash and Financial Instruments

Exam 1: The Demand for Audit and Other Assurance Services47 Questions
Exam 2: The Cpa Profession79 Questions
Exam 3: Audit Reports140 Questions
Exam 4: Professional Ethics119 Questions
Exam 5: Legal Liability115 Questions
Exam 6: Audit Responsibilities and Objectives132 Questions
Exam 7: Audit Evidence105 Questions
Exam 8: Audit Planning and Analytical Procedures102 Questions
Exam 9: Materiality and Risk113 Questions
Exam 10: Internal Control, Control Risk, and Section 404 Audits116 Questions
Exam 11: Fraud Auditing93 Questions
Exam 12: The Impact of Information Technology on the Audit Process106 Questions
Exam 13: Overall Audit Strategy and Audit Program94 Questions
Exam 14: Audit of the Sales and Collection Cycle: Tests of Controls and Substantive Tests of Transactions109 Questions
Exam 15: Audit Sampling for Tests of Controls and Substantive Tests of Transactions119 Questions
Exam 16: Completing the Tests in the Sales and Collection Cycle: Accounts Receivable101 Questions
Exam 17: Audit Sampling for Tests of Details of Balances114 Questions
Exam 18: Audit of the Acquisition and Payment Cycle: Tests of Controls, Substantive Tests of Transactions, and Accounts Payable116 Questions
Exam 19: Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts101 Questions
Exam 20: Audit of the Payroll and Personnel Cycle113 Questions
Exam 21: Audit of the Inventory and Warehousing Cycle116 Questions
Exam 22: Audit of the Capital Acquisition and Repayment Cycle91 Questions
Exam 23: Audit of Cash and Financial Instruments121 Questions
Exam 24: Completing the Audit120 Questions
Exam 25: Other Assurance Services104 Questions
Exam 26: Internal and Governmental Financial Auditing and Operational Auditing73 Questions
Select questions type


Which of the following misstatements is most likely to be uncovered during an audit of a client's bank reconciliation?
(Multiple Choice)
4.9/5  (72)
(72) A proof of cash includes a reconciliation of cash receipts deposited in the bank with the cash disbursements records for a given period.
(True/False)
4.9/5 (80)
(80) Bank reconciliation audit tests are designed to detect misstatements other than through the improper payment of cash or failure to receive cash normally would not be detected as part of the tests of the bank reconciliation.List below at least THREE misstatements that are designed to be detected by bank reconciliation.
(Essay)
4.9/5 (78)
(78) Which of the following items would not normally appear on bank reconciliations?
(Multiple Choice)
4.7/5 (79)
(79) A proof of cash receipts is not useful for uncovering the theft of cash receipts or the recording and deposit of an improper amount of cash.
(True/False)
4.7/5 (84)
(84) The direct receipt of a confirmation from every bank with which the client does business is:
(Multiple Choice)
4.9/5 (84)
(84) Completeness is an important objective for derivative financial instruments.
(True/False)
4.7/5 (80)
(80) A proof of cash involves a combination of substantive tests of transactions and tests of details of balances.
(True/False)
5.0/5 (68)
(68) The most important objectives for financial instruments are existence and consistency.
(True/False)
4.8/5 (75)
(75) Auditors will often prepare a proof of cash when the client has material internal control weaknesses in cash receipts and cash disbursements.The purpose of the proof of cash is to determine the client's accounting records for cash are reliable.List below the four requirements the proof of cash is designed to provide for the auditor.
(Essay)
4.9/5 (82)
(82) List two common tests of details of balances procedures the auditor would perform when testing for the balance-related audit objective of realizable value.
(Essay)
4.7/5 (78)
(78) The auditor must extend the audit procedures in the audit of year-end cash when there are inadequate internal controls.
(True/False)
4.8/5 (79)
(79) The audit procedure which requires the auditor to record the last check number used on the last day of the year and subsequently trace to the outstanding checks and the cash disbursements records is performed to satisfy the audit objective of:
(Multiple Choice)
4.9/5 (70)
(70) A factor that increases inherent risk for financial instruments is the complexity of the relevant accounting standards.
(True/False)
4.8/5 (63)
(63) Auditors sometimes prepare a proof of cash when the client has material internal control weaknesses in cash.List two procedures that the proof of cash determines were or were not done.
(Essay)
4.9/5 (68)
(68) Ordinarily, all deposits-in-transit listed on the year-end bank reconciliation should appear as deposits on the cutoff bank statement.
(True/False)
4.8/5 (87)
(87) Analytical procedures may be used to assess the year-end balances for financial instruments.
(True/False)
4.8/5 (86)
(86) Listing all bank transfers made a few days before and after the balance sheet date and tracing each to the accounting records for proper recording is a useful approach to test for:
(Multiple Choice)
4.7/5 (87)
(87) The following information applies to the questions below:
Listed below are four interbank cash transfers, indicated by the numbers 1, 2, 3, and 4, of a client for late December 2013 and early January 2014:
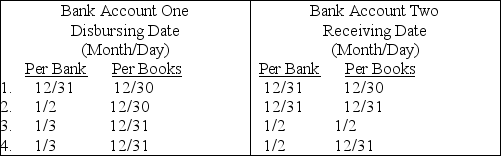 -Based on the schedule of interbank transfers above, which of the cash transfers indicates an error in cash cutoff at December 31, 2013?
 (Multiple Choice)
4.9/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)