



 Chat with AI
Exam 6: Audit Responsibilities and Objectives

Exam 1: The Demand for Audit and Other Assurance Services47 Questions
Exam 2: The Cpa Profession79 Questions
Exam 3: Audit Reports140 Questions
Exam 4: Professional Ethics119 Questions
Exam 5: Legal Liability115 Questions
Exam 6: Audit Responsibilities and Objectives132 Questions
Exam 7: Audit Evidence105 Questions
Exam 8: Audit Planning and Analytical Procedures102 Questions
Exam 9: Materiality and Risk113 Questions
Exam 10: Internal Control, Control Risk, and Section 404 Audits116 Questions
Exam 11: Fraud Auditing93 Questions
Exam 12: The Impact of Information Technology on the Audit Process106 Questions
Exam 13: Overall Audit Strategy and Audit Program94 Questions
Exam 14: Audit of the Sales and Collection Cycle: Tests of Controls and Substantive Tests of Transactions109 Questions
Exam 15: Audit Sampling for Tests of Controls and Substantive Tests of Transactions119 Questions
Exam 16: Completing the Tests in the Sales and Collection Cycle: Accounts Receivable101 Questions
Exam 17: Audit Sampling for Tests of Details of Balances114 Questions
Exam 18: Audit of the Acquisition and Payment Cycle: Tests of Controls, Substantive Tests of Transactions, and Accounts Payable116 Questions
Exam 19: Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts101 Questions
Exam 20: Audit of the Payroll and Personnel Cycle113 Questions
Exam 21: Audit of the Inventory and Warehousing Cycle116 Questions
Exam 22: Audit of the Capital Acquisition and Repayment Cycle91 Questions
Exam 23: Audit of Cash and Financial Instruments121 Questions
Exam 24: Completing the Audit120 Questions
Exam 25: Other Assurance Services104 Questions
Exam 26: Internal and Governmental Financial Auditing and Operational Auditing73 Questions
Select questions type


Below are five audit procedures, all of which are tests of balances associated with the audit of accounts receivable.Also below are the eight general balance-related audit objectives and the four management assertions.For each audit procedure, indicate (1)its audit objective, and (2)the management assertion being tested.
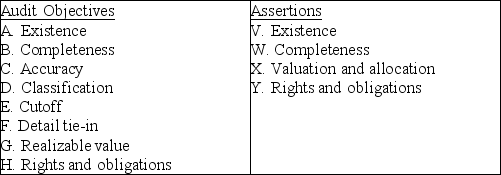 1.Obtain an aged listing of accounts receivable.For a sample of individual customers on the listing, agree the customer's name, amount, and other information with the corresponding information in the accounts receivable master file.
(1)________.
(2)________.
2.Examine details of sales for five days before and five days after year-end to determine whether sales have been recorded in the proper period.
(1)________.
(2)________.
3.Assess the reasonableness of the balance in the allowance for doubtful accounts.
(1)________.
(2)________.
4.Inquire as to whether any accounts receivable have been factored or sold during the period.
(1)________.
(2)________.
5.Inquire as to whether there are any receivables from related parties.
(1)________.
(2)________.
1.Obtain an aged listing of accounts receivable.For a sample of individual customers on the listing, agree the customer's name, amount, and other information with the corresponding information in the accounts receivable master file.
(1)________.
(2)________.
2.Examine details of sales for five days before and five days after year-end to determine whether sales have been recorded in the proper period.
(1)________.
(2)________.
3.Assess the reasonableness of the balance in the allowance for doubtful accounts.
(1)________.
(2)________.
4.Inquire as to whether any accounts receivable have been factored or sold during the period.
(1)________.
(2)________.
5.Inquire as to whether there are any receivables from related parties.
(1)________.
(2)________. (Short Answer)
4.7/5  (96)
(96) The transaction-related audit objective that deals with whether recorded transactions have actually occurred is the completeness objective.
(True/False)
4.8/5 (97)
(97) The auditor's audit objectives follow and are closely related to management assertions.
(True/False)
4.8/5 (68)
(68) The detail tie-in is part of the ________ assertion for account balances.
(Multiple Choice)
5.0/5 (73)
(73) The transaction-related audit objective of timing is related to the assertion of cutoff.
(True/False)
4.9/5 (87)
(87) Which of the following assertions is described as "this assertion addresses whether all transactions that should be included in the financial statements are in fact included"?
(Multiple Choice)
4.8/5 (74)
(74) Why does the auditor divide the financial statements into smaller segments?
(Multiple Choice)
4.8/5 (75)
(75) The detail tie-in objective is not concerned that the details in the account balance:
(Multiple Choice)
4.7/5 (87)
(87) An auditor assesses the risk of material misstatement to determine the impact on the audit plan and to determine the nature, extent, and timing of the audit procedures.
(True/False)
4.7/5 (70)
(70) When the auditor identifies or suspects noncompliance with laws and regulations, the auditor:
(Multiple Choice)
4.9/5 (88)
(88) The cutoff objective, "transactions near the balance sheet date are recorded in the proper period," is a balance-related audit objective.
(True/False)
4.9/5 (87)
(87) If management insists on financial statement disclosures that the auditor finds unacceptable, the auditor can withdraw from the engagement or:
(Multiple Choice)
4.8/5 (79)
(79) The auditor's evaluation of the likelihood of material employee fraud is normally done initially as a part of:
(Multiple Choice)
4.9/5 (84)
(84) The objective of an audit of the financial statements is an expression of an opinion on:
(Multiple Choice)
4.9/5 (74)
(74) Asking the right questions and probing further until the auditor is satisfied with the responses can help the auditor to detect a material misstatement in the financial statements.
(True/False)
5.0/5 (99)
(99) Discuss three reasons why auditors are responsible for "reasonable" but not "absolute" assurance.
(Essay)
4.8/5 (83)
(83) An auditor discovers that the company's bookkeeper unintentionally made an mistake in calculating the amount of the quarterly sales.This is an example of:
(Multiple Choice)
4.8/5 (69)
(69) General transaction-related audit objectives vary from audit to audit, depending on the nature and characteristics of the client's business and industry.
(True/False)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)