



 Chat with AI
Exam 15: Perfect Competition

Exam 1: Getting Started337 Questions
Exam 2: The Usand Global Economies201 Questions
Exam 3: The Economic Problem273 Questions
Exam 4: Demand and Supply322 Questions
Exam 5: Elasticities of Demand and Supply335 Questions
Exam 6: Efficiency and Fairness of Markets352 Questions
Exam 7: Government Actions in Markets239 Questions
Exam 8: Taxes267 Questions
Exam 9: Global Markets in Action276 Questions
Exam 10: Externalities300 Questions
Exam 11: Public Goods and Common Resources177 Questions
Exam 12: Markets With Private Information101 Questions
Exam 13: Consumer Choice and Demand287 Questions
Exam 14: Production and Cost266 Questions
Exam 15: Perfect Competition275 Questions
Exam 16: Monopoly377 Questions
Exam 17: Monopolistic Competition213 Questions
Exam 18: Oligopoly222 Questions
Exam 19: Markets for Factors of Production178 Questions
Exam 20: Economic Inequality155 Questions
Select questions type


If perfectly competitive firms are maximizing their profit and are making an economic profit, the market ________ in a short-run equilibrium and ________ in a long-run equilibrium.
(Multiple Choice)
4.7/5  (82)
(82) A market is initially in a long-run equilibrium and there is a permanent increase in demand.After the new long-run equilibrium is reached, there
(Multiple Choice)
4.8/5 (84)
(84) 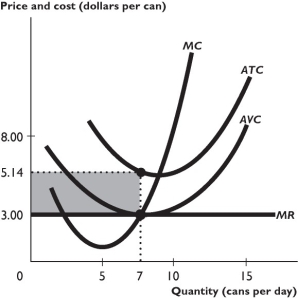 The above figure shows some a firm's cost curves and its marginal revenue curve.
-Based on the figure above, what is the price of a can?
The above figure shows some a firm's cost curves and its marginal revenue curve.
-Based on the figure above, what is the price of a can? (Multiple Choice)
4.8/5 (73)
(73) In the long run, perfectly competitive firms produce at the output level that has the minimum
(Multiple Choice)
4.9/5 (79)
(79) The firm in the figure above is ________ that is equal to ________.
(Multiple Choice)
4.8/5 (87)
(87) If a perfectly competitive firm finds that the price exceeds its ATC, then the firm
(Multiple Choice)
4.7/5 (62)
(62) Cynthia is an Oklahoma wheat farmer.The demand for her wheat is
(Multiple Choice)
4.8/5 (86)
(86) The marginal revenue curve for a perfectly competitive firm is
(Multiple Choice)
5.0/5 (84)
(84) A perfectly competitive firm will continue to operate in the short run when the market price is below its average total cost if the
(Multiple Choice)
4.8/5 (91)
(91) 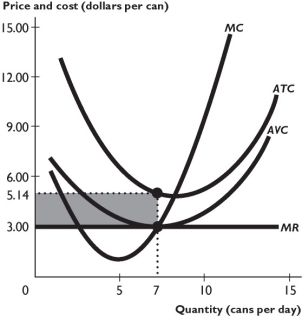 The figure above shows the cost curves and marginal revenue curve for a perfectly competitive firm.
-Based on the figure above, if the firm produces 7 cans per day, the firm ________ maximizing its profit and is ________.
The figure above shows the cost curves and marginal revenue curve for a perfectly competitive firm.
-Based on the figure above, if the firm produces 7 cans per day, the firm ________ maximizing its profit and is ________. (Multiple Choice)
4.8/5 (85)
(85) For a perfectly competitive rancher in Wyoming, if the price does not change, an economic profit could turn into an economic loss if the
(Multiple Choice)
4.8/5 (82)
(82) A perfectly competitive firm is earning an economic profit when total fixed costs increase.Assuming the firm does not shut down, in the short run the firm will
(Multiple Choice)
4.9/5 (89)
(89) Mark owns a cattle ranch near Hugo, Oklahoma.Mark is currently producing beef at an output level where marginal revenue exceeds marginal cost.In order to maximize his profit, Mark should
(Multiple Choice)
4.8/5 (72)
(72) In a perfectly competitive market, the type of decision a firm has to make is different in the short run than in the long run.Which of the following is an example of a perfectly competitive firm's short-run decision?
(Multiple Choice)
4.8/5 (82)
(82) 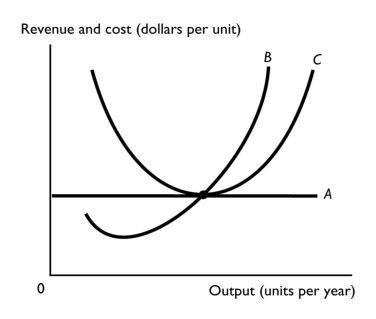 -The above figure illustrates a perfectly competitive firm.Curve B represents the
 (Multiple Choice)
4.9/5 (75)
(75) If firms in a perfectly competitive market are incurring economic losses, then as time passes firms ________ and the market ________.
(Multiple Choice)
4.9/5 (87)
(87) Can a perfectly competitive firm make an economic profit in the short run? Can it incur an economic loss?
(Essay)
4.8/5 (73)
(73) When one firm sells a good or service that has no close substitutes and a barrier blocks the entry of new firms, what type of market is this?
(Multiple Choice)
4.8/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)