



 Chat with AI
Exam 15: Perfect Competition

Exam 1: Getting Started337 Questions
Exam 2: The Usand Global Economies201 Questions
Exam 3: The Economic Problem273 Questions
Exam 4: Demand and Supply322 Questions
Exam 5: Elasticities of Demand and Supply335 Questions
Exam 6: Efficiency and Fairness of Markets352 Questions
Exam 7: Government Actions in Markets239 Questions
Exam 8: Taxes267 Questions
Exam 9: Global Markets in Action276 Questions
Exam 10: Externalities300 Questions
Exam 11: Public Goods and Common Resources177 Questions
Exam 12: Markets With Private Information101 Questions
Exam 13: Consumer Choice and Demand287 Questions
Exam 14: Production and Cost266 Questions
Exam 15: Perfect Competition275 Questions
Exam 16: Monopoly377 Questions
Exam 17: Monopolistic Competition213 Questions
Exam 18: Oligopoly222 Questions
Exam 19: Markets for Factors of Production178 Questions
Exam 20: Economic Inequality155 Questions
Select questions type


Describe how economic losses are eliminated in a perfectly competitive industry.
(Essay)
4.9/5  (84)
(84) Catfish farming is a perfectly competitive industry.Catfish farmers suffered tremendous economic losses in the late 2000s.As a result,
(Multiple Choice)
5.0/5 (84)
(84) A perfectly competitive firm is producing 50 units of output, which it sells at the market price of $23 per unit.The firm's average total cost is $20.What is the firm's total revenue?
(Multiple Choice)
4.9/5 (74)
(74) What are the four types of markets? Give a brief description of each type.
(Essay)
4.8/5 (83)
(83) 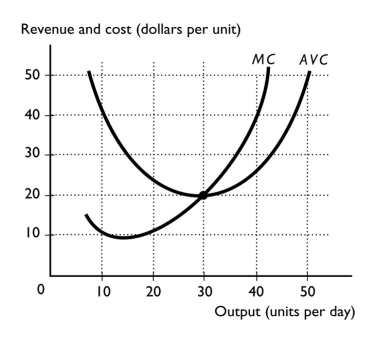 -The above figure illustrates a perfectly competitive firm.If the market price is $10 a unit, to maximize its profit (or minimize its loss)the firm should
 (Multiple Choice)
5.0/5 (88)
(88) We know that a perfectly competitive firm is a price taker because
(Multiple Choice)
4.9/5 (79)
(79) With regard to its profits and losses, how is the short run different from the long run for a perfectly competitive firm?
(Essay)
4.7/5 (85)
(85) To increase its profit, a perfectly competitive firm will produce more output when
(Multiple Choice)
4.8/5 (76)
(76)  The figure above shows some of a firm's cost curves and its marginal revenue curve.
-The firm in the figure above is ________ that is equal to ________.
The figure above shows some of a firm's cost curves and its marginal revenue curve.
-The firm in the figure above is ________ that is equal to ________. (Multiple Choice)
4.9/5 (77)
(77) In which market structure do firms exist in very large numbers, each firm produces an identical product, and there is freedom of entry and exit?
(Multiple Choice)
4.8/5 (74)
(74) 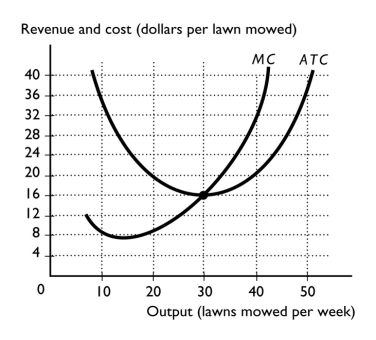 -Bill owns a lawn-care company in Windermere, Florida, whose cost curves are illustrated in the above figure.The market equilibrium price in this perfectly competitive market equals $32 per lawn mowed.Bill's average total cost curve is ATC, so his total cost of production equals
 (Multiple Choice)
4.9/5 (72)
(72) One part of a perfectly competitive trout farm's supply curve is its
(Multiple Choice)
4.8/5 (78)
(78)  -The above figure shows three possible average total cost curves.If all firms in a perfectly competitive industry each have an average total cost curve identical to ATC₀, each produces 20 units, and the market price of the good is $16 per unit, then
 (Multiple Choice)
4.8/5 (75)
(75) 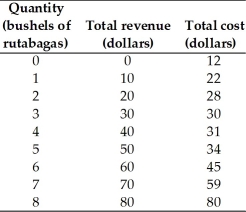 -The above table has the total revenue and total cost schedule for Omar, a perfectly competitive grower of rutabagas.When Omar produces 2 bushels of rutabagas, his total profit equals
 (Multiple Choice)
4.8/5 (64)
(64)
-The above figure shows three possible average total cost curves.If all firms in a perfectly competitive industry each have an average total cost curve identical to ATC₂, each produces 40 units, and the market price of the good is $20 per unit, then
-The above figure shows three possible average total cost curves.If all firms in a perfectly competitive industry each have an average total cost curve identical to ATC₂, each produces 40 units, and the market price of the good is $20 per unit, then (Multiple Choice)
4.8/5 (81)
(81) 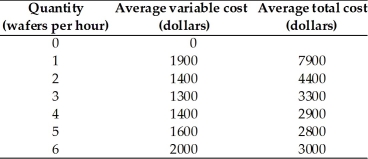 -Computer memory chips are produced on wafers, each wafer having many separate chips that are separated and sold.The above table shows costs for a perfectly competitive producer of computer memory chips.This firm will produce as long as the market price of a wafer is above
 (Multiple Choice)
4.9/5 (61)
(61) One requirement for an industry to be perfectly competitive is that
(Multiple Choice)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)