



 Chat with AI
Exam 11: Technology, Production, and Costs

Exam 1: Economics: Foundations and Models240 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System258 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes208 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods262 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply293 Questions
Exam 7: The Economics of Health Care171 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance261 Questions
Exam 9: Comparative Advantage and the Gains From International Trade188 Questions
Exam 10: Consumer Choice and Behavioral Economics304 Questions
Exam 11: Technology, Production, and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets297 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets257 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy258 Questions
Exam 17: The Markets for Labor and Other Factors of Production279 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Select questions type


Which of the following would be categorized as an implicit cost?
A.not being able to spend your $10,000 savings if you sink the money in your business
B.the cost of purchasing supplies for your house-cleaning business
C.the cost of purchasing auto insurance for your dry-cleaning delivery business
(Multiple Choice)
4.9/5  (74)
(74) One reason why, in the short run, the marginal product of labor might increase initially as more workers are hired is that
(Multiple Choice)
4.8/5 (80)
(80) Vipsana's Gyros House sells gyros.The cost of ingredients (pita, meat, spices, etc.)to make a gyro is $2.00.Vipsana pays her employees $60 per day.She also incurs a fixed cost of $120 per day.Calculate Vipsana's variable cost per day when she produces 50 gyros using two workers?
(Multiple Choice)
4.9/5 (77)
(77) Which of the following costs will not change as output changes?
(Multiple Choice)
4.8/5 (83)
(83) Costs that change as output changes are called incremental costs.
(True/False)
4.8/5 (95)
(95) Jayanthi moves her yoga studio from her home to a space she rents in Oakland, California.Holding everything else constant, as a result of this move
(Multiple Choice)
4.8/5 (71)
(71) What is the difference between "diminishing marginal returns" and "diseconomies of scale"?
(Multiple Choice)
4.9/5 (77)
(77) Figure 11-10
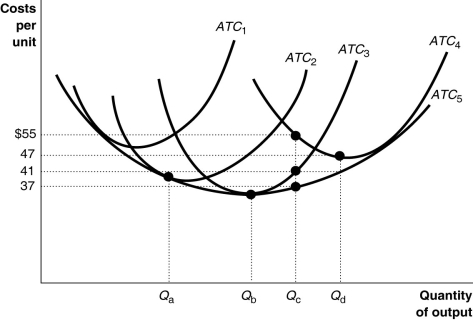 -Refer to Figure 11-10.Identify the minimum efficient scale of production.
 (Multiple Choice)
4.9/5 (78)
(78) In the short run, changes in output can only be brought about by a change in the quantity of variable inputs.
(True/False)
4.9/5 (88)
(88) If a firm experiences positive technological change, it is able to produce more output using the same inputs.
(True/False)
4.9/5 (85)
(85) The marginal cost curve is U-shaped because of the law of increasing opportunity costs.
(True/False)
5.0/5 (81)
(81) You own a business that answers telephone calls for physicians after their offices close.You have an incentive to substitute capital for labor if the
(Multiple Choice)
4.9/5 (86)
(86) In the short run, if the marginal product is at its maximum, then the
(Multiple Choice)
4.7/5 (67)
(67) The difference between technology and technological change is that
(Multiple Choice)
4.8/5 (89)
(89) Figure 11-6
 Figure 11-6 contains information about the short-run cost structure of a firm.
-Refer to Figure 11-6.In the figure above, which letter represents the average variable cost curve?
Figure 11-6 contains information about the short-run cost structure of a firm.
-Refer to Figure 11-6.In the figure above, which letter represents the average variable cost curve? (Multiple Choice)
4.8/5 (71)
(71) Which of the following can a firm do in the long run but not in the short run?
(Multiple Choice)
5.0/5 (84)
(84) Suppose two countries use different combinations of inputs, such as labor and capital, to produce the same product.This implies any one of the following except that
(Multiple Choice)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)