



 Chat with AI
Exam 11: Technology, Production, and Costs

Exam 1: Economics: Foundations and Models240 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System258 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes208 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods262 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply293 Questions
Exam 7: The Economics of Health Care171 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance261 Questions
Exam 9: Comparative Advantage and the Gains From International Trade188 Questions
Exam 10: Consumer Choice and Behavioral Economics304 Questions
Exam 11: Technology, Production, and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets297 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets257 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy258 Questions
Exam 17: The Markets for Labor and Other Factors of Production279 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Select questions type


Which of the following is an example of market "production," as used by economists?
(Multiple Choice)
4.9/5  (80)
(80) The slope of an isocost line determines the marginal rate of substitution.
(True/False)
4.9/5 (74)
(74) Consider a manufacturing operation that uses specialized machinery and labor to produce its output.In this case, the input that is not fixed in the short run is labor.
(True/False)
4.8/5 (77)
(77) Minimum efficient scale is defined as the level of output at which the short-run average total cost stops decreasing.
(True/False)
4.9/5 (82)
(82) Firms in different countries that face different input prices may produce the same good using different combinations of inputs, even though they have access to the same technology.
(True/False)
4.8/5 (79)
(79) Table 11-4
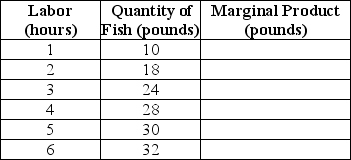 -Refer to Table 11-4.The table above shows the following relationship between hours spent fishing and the quantity of fish caught for Juan, a commercial fisherman.
a.Complete the Marginal Product column in Table 11-4.
b.Characterize the production function, i.e.does the production function display increasing marginal returns, diminishing marginal returns, etc.
c.Using the data above, graph Juan's marginal product curve.Be sure to label the horizontal and vertical axes.Is your graph consistent with your answer to part (b)? Explain.
d.Juan uses the following inputs for fishing - a small wooden boat (B), a fishing pole (P)and of course, his labor (L).Treating the boat and the fishing pole as fixed inputs and using the data above, graph Juan's Total Product of Labor curve.Be sure to label the horizontal and vertical axes.
e.The opportunity cost of Juan's time is $8 per hour.If Juan receives $2 per pound for his fish, what is the optimal number of hours he should spend fishing? Explain how you arrived at your answer.Hint: Recall marginal benefit and marginal cost analysis.
-Refer to Table 11-4.The table above shows the following relationship between hours spent fishing and the quantity of fish caught for Juan, a commercial fisherman.
a.Complete the Marginal Product column in Table 11-4.
b.Characterize the production function, i.e.does the production function display increasing marginal returns, diminishing marginal returns, etc.
c.Using the data above, graph Juan's marginal product curve.Be sure to label the horizontal and vertical axes.Is your graph consistent with your answer to part (b)? Explain.
d.Juan uses the following inputs for fishing - a small wooden boat (B), a fishing pole (P)and of course, his labor (L).Treating the boat and the fishing pole as fixed inputs and using the data above, graph Juan's Total Product of Labor curve.Be sure to label the horizontal and vertical axes.
e.The opportunity cost of Juan's time is $8 per hour.If Juan receives $2 per pound for his fish, what is the optimal number of hours he should spend fishing? Explain how you arrived at your answer.Hint: Recall marginal benefit and marginal cost analysis. (Essay)
4.8/5 (94)
(94) Table 11-2
 Table 11-2 summarizes production at the Crunchy Apple Orchard for the month of April.
-Refer to Table 11-2.What is the marginal product of the 4th worker?
Table 11-2 summarizes production at the Crunchy Apple Orchard for the month of April.
-Refer to Table 11-2.What is the marginal product of the 4th worker? (Multiple Choice)
4.9/5 (86)
(86) Figure 11-6
 Figure 11-6 contains information about the short-run cost structure of a firm.
-Refer to Figure 11-6.In the figure above, which letter represents the marginal cost curve?
Figure 11-6 contains information about the short-run cost structure of a firm.
-Refer to Figure 11-6.In the figure above, which letter represents the marginal cost curve? (Multiple Choice)
4.8/5 (81)
(81) If the 15th unit of output has a marginal cost of $29.50 and the average cost of producing 14 units of output is $30.23, what will happen to the average cost of production if the 15th unit is produced?
(Multiple Choice)
5.0/5 (72)
(72) If 11 workers can produce 53 units of output while 12 workers can produce 56 units of output, what is the marginal product of the 12th worker?
(Multiple Choice)
4.8/5 (69)
(69) Which of the following statements best describes the economic short run?
(Multiple Choice)
4.9/5 (67)
(67) Economies of scale exist as a firm increases its size in the long run because of all of the following except
(Multiple Choice)
4.9/5 (85)
(85) A curve that shows all the combinations of two inputs, such as labor and capital, that will produce the same level of output is called
(Multiple Choice)
4.8/5 (76)
(76) A characteristic of the long run that is not available in the short run is that a firm is free to vary its output.
(True/False)
4.7/5 (71)
(71) Golda Rush quit her job as a manager for Home Depot to start her own hair dressing salon, Goldilocks.She gave up a salary of $40,000 per year, invested her savings of $30,000 (which was earning 5 percent interest)and borrowed $10,000 from a close friend, agreeing to pay 5 percent interest per year.In her first year, Golda spent $18,000 to rent a salon, hired a part-time assistant for $12,000 and incurred another $15,000 in expenses on equipment and hairdressing material.Based on this information, what is the amount of her implicit costs for the first year?
(Multiple Choice)
4.7/5 (95)
(95) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)