



 Chat with AI
Exam 11: Technology, Production, and Costs

Exam 1: Economics: Foundations and Models240 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System258 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes208 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods262 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply293 Questions
Exam 7: The Economics of Health Care171 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance261 Questions
Exam 9: Comparative Advantage and the Gains From International Trade188 Questions
Exam 10: Consumer Choice and Behavioral Economics304 Questions
Exam 11: Technology, Production, and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets297 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets257 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy258 Questions
Exam 17: The Markets for Labor and Other Factors of Production279 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Select questions type


Which of the following statements explains the difference between diminishing returns and diseconomies of scale?
(Multiple Choice)
4.8/5  (86)
(86) The president of Toyota's Georgetown plant was quoted as saying, "Demand for high volumes saps your energy.Over a period of time, it eroded our focus [and] thinned out the expertise and knowledge we painstakingly built up over the years." This quote suggests that
(Multiple Choice)
5.0/5 (62)
(62) If production displays constant returns to scale, then all economies of scale have been exhausted.
(True/False)
4.9/5 (86)
(86) Figure 11-17
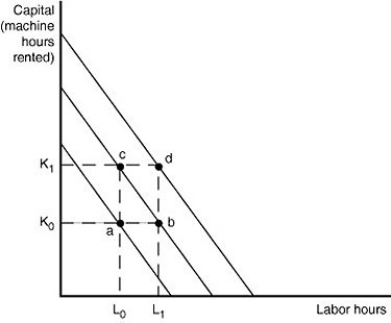 -Refer to Figure 11-17.Assume that production isoquants are convex.Total cost and output produced must increase for each of the following movements except one.Which movement is the exception?
 (Multiple Choice)
4.8/5 (86)
(86) The processes a firm uses to turn inputs into outputs of goods and services is called
(Multiple Choice)
4.9/5 (79)
(79) Which of the following statements regarding a firm's long-run average total cost (LRATC)curve and its short-run average total cost (SRATC)curve is true?
(Multiple Choice)
4.8/5 (84)
(84) In the short run, marginal product of labor increases at first and then falls because
(Multiple Choice)
5.0/5 (78)
(78) If a firm produces 20 units of output and incurs a total cost of $1,000 and a variable cost is $700, calculate the firm's average fixed cost of production if it expands output to 25 units.
(Multiple Choice)
4.9/5 (99)
(99) Gertrude Stork's Chocolate Shoppe normally employs 4 workers.When the Chocolate Shoppe hired a 5th worker, the Shoppe's total output decreased.Therefore,
(Multiple Choice)
4.9/5 (72)
(72) If we have information about workers' marginal products, then total and average product can be found by
(Multiple Choice)
4.8/5 (78)
(78) Figure 11-7
 Figure 11-7 shows the cost structure for a firm.
-Refer to Figure 11-7.When the output level is 100 units, average fixed cost is
Figure 11-7 shows the cost structure for a firm.
-Refer to Figure 11-7.When the output level is 100 units, average fixed cost is (Multiple Choice)
4.7/5 (75)
(75) Which of the following statements correctly describes the distinction between technology and technological change?
(Multiple Choice)
4.9/5 (78)
(78) Table 11-7
 Table 11-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 11-7.What is the variable cost of production when the firm produces 115 lanterns?
Table 11-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 11-7.What is the variable cost of production when the firm produces 115 lanterns? (Multiple Choice)
4.9/5 (85)
(85) Average total cost is equal to average variable cost minus average fixed cost.
(True/False)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)