



 Chat with AI
Exam 6: Accounting Quality

Exam 1: Overview of Financial Reporting, financial Statement Analysis, and Valuation101 Questions
Exam 2: Asset and Liability Valuation and Income Measurement81 Questions
Exam 3: Income Flows Versus Cash Flows: Understanding the Statement of Cash Flows88 Questions
Exam 4: Profitability Analysis97 Questions
Exam 5: Risk Analysis86 Questions
Exam 6: Accounting Quality64 Questions
Exam 7: Financing Activities66 Questions
Exam 8: Investing Activities100 Questions
Exam 9: Operating Activities94 Questions
Exam 10: Forecasting Financial Statements63 Questions
Exam 11: Risk-Adjusted Expected Rates of Return and the Dividends Valuation Approach52 Questions
Exam 12: Valuation: Cash-Flow-Based Approaches65 Questions
Exam 13: Valuation: Earnings-Based Approaches67 Questions
Exam 14: Valuation: Market-Based Approaches64 Questions
Select questions type


Accounting information should be a fair and complete representation of the firm's economic ____________________,____________________,and ____________________.

Free
(Short Answer)
4.8/5  (73)
(73) Correct Answer: Verified
performance,position,risk
The _________________________ is the date on which a firm commits itself to a formal plan to dispose of a business segment.
Free
(Short Answer)
4.9/5 (85)
(85) Correct Answer:Verified
Verifiedmeasurement date
Healy and Wahlen state that one type of earnings management occurs when managers use judgement in financial reporting to alter financial reports in order to mislead some stakeholder about the economic performance of the company.Earnings management is a consequence of a judgement by management which results in lower economic information content of the financial reports.
Discuss five motives that encourage managers to practice earnings management.
Free
(Essay)
4.9/5 (87)
(87) Correct Answer:Verified
VerifiedMotives to manage earnings:
1.Managers want to maximize their compensation packages.
2.Managers want to protect their jobs and gain more job security.
3.Managers want to reduce risk in order to create a more optimal lending environment and to manage debt restrictions and covenants.
4.Managers want to influence short-term stock price movements for their advantage.
5.Managers want to manage earnings in order to thwart industry-specific and anti-trust actions against the firm.
First Bank recognized an extraordinary loss from the settlement of a lawsuit with Fifth Street Bank that it had impeded on a processing patent.The extraordinary loss was in the amount of $4,250,000 and First Bank Corporation has an effective tax rate of 35%.First Bank paid the settlement immediately and recognized the tax benefit as a receivable to offset the current period's taxes.
Instructions:a.Prepare the extraordinary item portion of First Bank Corporation's financial statement.
b.Using the analytical framework discussed in the text and reprinted below show the effect of following event on First Bank Corporation's financial statements.
Analytical Framework:
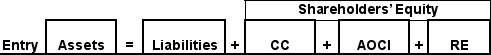
(Essay)
4.9/5 (85)
(85) As transitory components become a more important part of a firm's reported earnings,the reported earnings
(Multiple Choice)
4.9/5 (70)
(70) Achieving comparability in financial reporting is important to the analysis of multinational firms.However,the data from the reconciliation of foreign firms financial statement to U.S.GAAP must be carefully interpreted.What types of things complicate the analysis of multinational firms?
(Essay)
4.9/5 (80)
(80) Banks Corp.reported net income of $595,000 in 2012.During 2012 Banks reported a loss of $87,435 from a peripheral activity.The loss was included as part of income from continuing operations.Assuming that the loss is a one-time event and that Banks has an effective tax rate of 35% calculate Banks' adjusted net income.Show all of your calculations for credit.
In addition,discuss why analysts might make an adjustment of this type.
(Essay)
4.9/5 (71)
(71) On September 1,2012,Ramos Inc.approved a plan to dispose of a segment of its business.Ramos expected that the sale would occur on March 31,2013,at an estimated gain of $375,500.The segment had actual and estimated operating profits (losses as follows):
Realized loss from 1/1/12 to 8/31/12 \ 200,000 Realized loss from 9/1/12 to 12/31/12 (135,000 Expected profit from 1/1/13 to 3/31/13 475,000
Assume a marginal tax rate of 35%
Required:
A)In its 2012 income statement,what should Ramos report as profit or loss from discontinued operations (net of tax effects)?
B)Calculate the amount of income that should be shown on the 2013 income statement as a result of the operating profit and the gain on disposal (net of tax)
(Essay)
4.9/5 (89)
(89) A ____________________ of operations differs from a discontinuation of operations because the firm continues to operate in the business segment.
(Short Answer)
4.9/5 (68)
(68) When evaluating the quality of accounting information the user should consider the reasonableness of the ____________________ made in applying GAAP.
(Short Answer)
4.8/5 (70)
(70) An extraordinary gain or loss is unusual in nature,_____________________________________________,and material in amount.
(Short Answer)
4.8/5 (86)
(86) U.S.GAAP requires that changes in estimates be accounted for by recognizing the effect ________________________________________ period(s).
(Short Answer)
4.9/5 (72)
(72) Some firms attempt to maximize the amount of restructuring charge in a particular year,analysts refer to this as the _________________________ approach.
(Short Answer)
4.9/5 (78)
(78) Examples of poor earnings quality that hinder the forecasting of expected future earnings include all of the following except:
(Multiple Choice)
4.8/5 (80)
(80) ____________________ represents the concept of being able to compare financial statement data across years for any particular firm.
(Short Answer)
4.8/5 (77)
(77) Income or loss from discontinued operations would best be regarded by an analyst as:
(Multiple Choice)
4.9/5 (90)
(90) Which of the following are characteristics of an extraordinary item?
(Multiple Choice)
4.9/5 (68)
(68) Which one of the following is an example of sustainable earnings?
(Multiple Choice)
4.9/5 (83)
(83) Mattel,Inc.designs,manufactures and markets various toy products worldwide through sales to retailers and directly to consumers.Among the company's many products are Barbie,GI Joe,and American Girls.Below is an income statement for Mattel for years 2002,2001 and 2000.Notes to the financial statements reveal the following information.
1.Discontinued Operations - In 1999 Mattel merged with Learning Company,with Mattel being the surviving company.The Learning Company,which produced consumer software,represented a separate line of business for Mattel.In 2000 Mattel's Board of Directors committed to dispose of the Learning Company and its consumer software operations.In 2000 the Learning Company was reported as a discontinued operation and the company was sold to Gores Technology on October 18,2000.
In 2002 Mattel received a contractual payment from Gores Technology based on the sale of assets of Learning Company and other liquidation events.
2.Accounting Change - In 2001 Mattel changed the manner in which it accounted for derivative instruments consistent with the issuance of SFAS No.133 Accounting for Derivative Instruments and hedging Activities.The change resulted in Mattel recording a one-time adjustment of $12 million.
3.Accounting Change - In 2002 the FASB issued SFAS No.142 Goodwill and Other Intangible Assets.The standard requires that management estimate the value of its goodwill and,if necessary,record an impairment charge.Consistent with SFAS No.142 Mattel recorded a one-time adjustment of $252.2 million,net of tax,as the cumulative effect of the change in accounting principle.
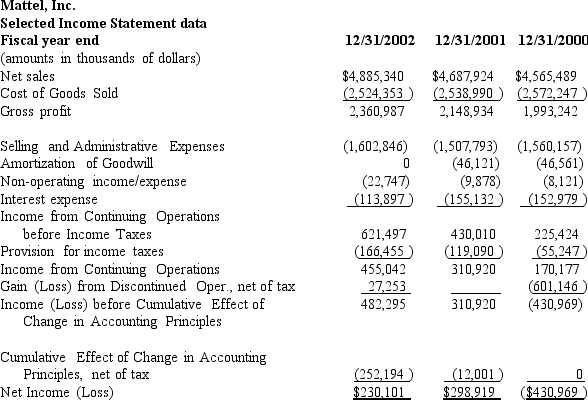 Required:a.Discuss whether or not you would adjust for each of the following items when using earnings to forecast the future profitability of Mattel:
(1)Discontinuance of the Consumer Software operations.
(2)The change in accounting for derivative instruments.
(3)The change in accounting for goodwill and other intangible assets.
b.Indicate the adjustment you would make to Mattel's net income for each of the items in part a.
c.Prepare a common size income statement for 2002,2001,2000 for Mattel.
d.Repeat part c after making the income statement adjustments in part b.
e.Assess the changes in profitability of Mattel during the three-year period.
Required:a.Discuss whether or not you would adjust for each of the following items when using earnings to forecast the future profitability of Mattel:
(1)Discontinuance of the Consumer Software operations.
(2)The change in accounting for derivative instruments.
(3)The change in accounting for goodwill and other intangible assets.
b.Indicate the adjustment you would make to Mattel's net income for each of the items in part a.
c.Prepare a common size income statement for 2002,2001,2000 for Mattel.
d.Repeat part c after making the income statement adjustments in part b.
e.Assess the changes in profitability of Mattel during the three-year period. (Essay)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)