



 Chat with AI
Exam 2: Asset and Liability Valuation and Income Measurement

Exam 1: Overview of Financial Reporting, financial Statement Analysis, and Valuation101 Questions
Exam 2: Asset and Liability Valuation and Income Measurement81 Questions
Exam 3: Income Flows Versus Cash Flows: Understanding the Statement of Cash Flows88 Questions
Exam 4: Profitability Analysis97 Questions
Exam 5: Risk Analysis86 Questions
Exam 6: Accounting Quality64 Questions
Exam 7: Financing Activities66 Questions
Exam 8: Investing Activities100 Questions
Exam 9: Operating Activities94 Questions
Exam 10: Forecasting Financial Statements63 Questions
Exam 11: Risk-Adjusted Expected Rates of Return and the Dividends Valuation Approach52 Questions
Exam 12: Valuation: Cash-Flow-Based Approaches65 Questions
Exam 13: Valuation: Earnings-Based Approaches67 Questions
Exam 14: Valuation: Market-Based Approaches64 Questions
Select questions type


The application of GAAP requires firms to write down assets whose fair values decrease below their book values,but does not allow firms to revalue upward the values of assets whose fair values have increased.This asymmetric treatment rests on the ________________________________________.

Free
(Short Answer)
4.8/5  (87)
(87) Correct Answer: Verified
conservatism convention.
Reporting financial assets and liabilities at fair values also is referred to as:
Free
(Multiple Choice)
4.9/5 (76)
(76) Correct Answer:Verified
VerifiedC
When recognizing deferred tax assets and liabilities,the income statement approach and the balance sheet approach yield identical results
Free
(Multiple Choice)
4.9/5 (80)
(80) Correct Answer:Verified
VerifiedC
Revenues and expenses that firms include in both net income to shareholders and in taxable income,but in different periods are referred to as _____________________________________________.
(Short Answer)
4.8/5 (75)
(75) Fellsmere Company's income tax return shows income taxes for 2010 of $35,000.The firm reports deferred tax assets before any valuation allowance of $32,600 at the beginning of 2010 and $35,200 at the end of 2010.It reports deferred tax liabilities of $26,900 at the beginning of 2010 and $24,300 at the end of 2010.
Required:
a.Assume for this part that the valuation allowance on the deferred tax assets totaled
$14,400 at the beginning of 2010 and $15,100 at the end of 2010.Compute the amount
of income tax expense for 2010.
b.Assume for this part that the valuation allowance on the deferred tax assets totaled
$14,400 at the beginning of 2010 and $12,700 at the end of 2010.Compute the amount
of income tax expense for 2010.
(Essay)
4.8/5 (79)
(79) There are three valuation methods that reflect historical values: acquisition cost,adjusted acquisition cost,and present value of cash flows using historical interest rates.For each of three methods discuss what the valuation represents and provide an example of a balance sheet item that is valued using the method.In addition,for each of the three methods valuation methods explain its advantages and disadvantages.
(Essay)
4.8/5 (75)
(75) Jurgen Company's income tax return shows income taxes for 2010 of $75,000 (that is,$75,000 is owed for 2010).For financial reporting,the firm reports deferred tax assets of $67,900 at the beginning of 2010 and $63,600 at the end of 2010.It reports deferred tax liabilities of $53,600 at the beginning of 2010 and $59,400 at the end of 2010.
Required:
a.Compute the amount of income tax expense for 2010.
b.Assume for this part that the firm's deferred tax assets are as stated above for 2010 but that its deferred tax liabilities were $83,500 at the beginning of 2010 and $72,100
at the end of 2010.Compute the amount of income tax expense for 2010.
c.Explain contextually why income tax expense is higher than taxes owed in Part a and lower than taxes owed in Part b.
(Essay)
4.9/5 (82)
(82) When income tax expense for a period is greater than income tax payable the difference will be reported how and on which financial statement?
(Multiple Choice)
4.8/5 (88)
(88) The analytical framework used to evaluate transactions is reproduced below:
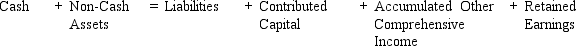 Using this analytical framework indicate the effect of each of the following transactions for TX Corporation:
1.TX Corporation sold additional shares of common stockmarketable securities for for $250,000 cash
2.At the end of the period TX Corporation revalued the securities to $125,000.
3.During the next period TX Corporation sells equipment with a book value of $100,000 for $$90,000
Using this analytical framework indicate the effect of each of the following transactions for TX Corporation:
1.TX Corporation sold additional shares of common stockmarketable securities for for $250,000 cash
2.At the end of the period TX Corporation revalued the securities to $125,000.
3.During the next period TX Corporation sells equipment with a book value of $100,000 for $$90,000 (Essay)
4.9/5 (82)
(82) Discuss the three ways in which GAAP allows value changes to be treated in the financial statements.Provide an example of each value change treatment.
(Essay)
4.9/5 (85)
(85) U.S.GAAP and IFRS allows the use of present value to calculate the cost of an asset except:
(Multiple Choice)
4.9/5 (84)
(84) For some transactions GAAP requires that value changes are recognized on the balance sheet and the income statement when they occur,even if not realized.Discuss what types of transactions get this type of treatment and the logic behind this accounting.
(Essay)
4.7/5 (88)
(88) Firms use acquisition cost valuations and adjusted acquisition cost valuations for which of the following types of assets?
(Multiple Choice)
5.0/5 (70)
(70) The net amount a firm would receive if it sold an asset or the net amount it would pay to settle a liability is referred to as
(Multiple Choice)
4.9/5 (89)
(89) Balance Sheet Equation
 -Refer to Balance Sheet Equation.The payment of a note payable by a firm reduces cash and ______________________________.
 (Short Answer)
4.8/5 (85)
(85) If a portfolio manager had to estimate the fair value of privately placed bond issues,which of the following would he/she most likely identify as the level of inputs to determine this?
(Multiple Choice)
4.8/5 (74)
(74) For each of the items below,determine whether the items are temporary differences or permanent differences.
For each temporary difference,determine whether a deferred tax asset or deferred tax liability is created by the temporary difference described.Assume that each of the temporary differences described is an originating difference.1.Accrued bad debt expense
2.The dividends received deduction
3.Installment sales revenue
4.Insurance payments for executives for which the company is the beneficiary
5.Fines paid for law violations
6.Municipal bond interest
7.Accrued warranty expense
8.Revenues received in advance
9.Expenses paid for in advance (prepaid insurance)
10.Tax depreciation expense exceeds GAAP (book)depreciation expense
(Essay)
4.9/5 (88)
(88) If a portfolio manager had to estimate the fair value of real estate,which of the following would he/she most likely identify as the level of inputs to determine this?
(Multiple Choice)
4.8/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)