



 Chat with AI
Exam 7: International Arbitrage and Interest Rate Parity

Exam 1: Multinational Financial Management: An Overview79 Questions
Exam 2: International Flow of Funds74 Questions
Exam 3: International Financial Markets101 Questions
Exam 4: Exchange Rate Determination69 Questions
Exam 5: Currency Derivatives161 Questions
Exam 6: Government Influence on Exchange Rates116 Questions
Exam 7: International Arbitrage and Interest Rate Parity92 Questions
Exam 8: Relationships among Inflation, Interest Rates, and Exchange Rates59 Questions
Exam 9: Forecasting Exchange Rates84 Questions
Exam 10: Measuring Exposure to Exchange Rate Fluctuations82 Questions
Exam 11: Managing Transaction Exposure81 Questions
Exam 12: Managing Economic Exposure and Translation Exposure58 Questions
Exam 13: Direct Foreign Investment53 Questions
Exam 14: Multinational Capital Budgeting60 Questions
Exam 15: International Corporate Governance and Control72 Questions
Exam 16: Country Risk Analysis57 Questions
Exam 17: Multinational Cost of Capital and Capital Structure68 Questions
Exam 18: Long-Term Debt Financing53 Questions
Exam 19: Financing International Trade66 Questions
Exam 20: Short-Term Financing49 Questions
Exam 21: International Cash Management50 Questions
Select questions type


Realignment in the exchange rates of banks will eliminate locational arbitrage. More specifically, market forces will increase the ask rate of the bank from which the currency was bought to conduct locational arbitrage and will decrease the bid rate of the bank to which the currency was sold to conduct locational arbitrage
(True/False)
4.7/5  (79)
(79) Which of the following is an example of triangular arbitrage initiation?
(Multiple Choice)
4.9/5 (85)
(85) Assume the U.S. interest rate is 2 percentage points higher than the Swiss rate, and the forward rate of the Swiss franc has a 4 percent premium. Given this information:
(Multiple Choice)
4.9/5 (73)
(73) Assume the following information:
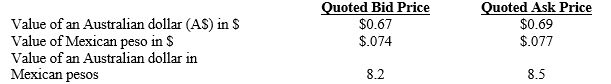 Assume you have $100,000 to conduct triangular arbitrage. What will be your profit from implementing this strategy?
(Multiple Choice)
4.9/5 (85)
(85) From the U.S. perspective, an example of a cross exchange rate is the exchange rate between a non-U.S. country and the U.S.
(True/False)
4.8/5 (64)
(64) If interest rate parity (IRP) does not hold, there is still the possibility that covered interest arbitrage is not worthwhile because of such factors as transaction costs, currency restrictions, and differential tax laws.
(True/False)
4.7/5 (69)
(69) When using ____, funds are typically tied up for a significant period of time
(Multiple Choice)
4.7/5 (78)
(78) Assume the following information for a bank quoting on spot exchange rates: Based on the information given, as you and others perform triangular arbitrage, what should logically happen to the spot exchange rates?
Exchange rate of Singapore dollar in U.S $=$.60
Exchange rate of pound in U.S.$=$1.50
Exchange rate of pound in Singapore dollars=S$2.6
(Multiple Choice)
4.9/5 (75)
(75) Assume the following information:
What will be the yield for an investor who has $1,000,000 available to conduct triangular arbitrage?
Exchange rate of Japanese yen in U.S.$
=$)011
Exchange rate of euro in U.S.$
=$1)40
Exchange rate of euro in Japanese yen
=140 yen
(Multiple Choice)
4.7/5 (79)
(79) Which of the following is not true regarding covered interest arbitrage?
(Multiple Choice)
5.0/5 (82)
(82) Assume the British pound is worth $1.60, and the Canadian dollar is worth $.80. What is the value of the Canadian dollar in pounds?
(Multiple Choice)
4.8/5 (72)
(72) To capitalize on high foreign interest rates using covered interest arbitrage, a U.S. investor would convert dollars to the foreign currency, invest in the foreign country, and simultaneously sell the foreign currency forward
(True/False)
4.7/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)