



 Chat with AI
Exam 11: Managing Transaction Exposure

Exam 1: Multinational Financial Management: An Overview42 Questions
Exam 2: International Flow of Funds46 Questions
Exam 3: International Financial Markets52 Questions
Exam 4: Exchange Rate Determination45 Questions
Exam 5: Currency Derivatives103 Questions
Exam 6: Government Influence on Exchange Rates68 Questions
Exam 7: International Arbitrage and Interest Rate Parity58 Questions
Exam 8: Relationships among Inflation,Interest Rates,and Exchange Rates37 Questions
Exam 9: Forecasting Exchange Rates58 Questions
Exam 10: Measuring Exposure to Exchange Rate Fluctuations59 Questions
Exam 11: Managing Transaction Exposure63 Questions
Exam 12: Managing Economic Exposure and Translation Exposure43 Questions
Exam 13: Direct Foreign Investment45 Questions
Exam 14: Multinational Capital Budgeting49 Questions
Exam 15: Multinational Restructuring52 Questions
Exam 16: Country Risk Analysis49 Questions
Exam 17: Multinational Cost of Capital and Capital Structure50 Questions
Exam 18: Long-Term Financing45 Questions
Exam 19: Financing International Trade60 Questions
Exam 20: Short-Term Financing48 Questions
Exam 21: International Cash Management38 Questions
Select questions type


Since the results of both a money market hedge and a forward hedge are known beforehand,an MNC can implement the one that is more feasible.
(True/False)
4.8/5  (91)
(91) Assume that Patton Co.will receive 100,000 New Zealand dollars (NZ$)in 180 days. Today's spot rate of the NZ$ is $.50,and the 180day forward rate is $.51. A call option on NZ$ exists,with an exercise price of $.52,a premium of $.02,and a 180day expiration date. A put option on NZ$ exists with an exercise price of $.51,a premium of $.02,and a 180day expiration date. Patton Co.has developed the following probability distribution for the spot rate in 180 days:
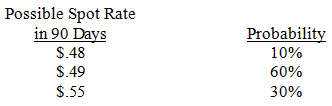 The probability that the forward hedge will result in more U.S.dollars received than the options hedge is _______ (deduct the amount paid for the premium when estimating the U.S.dollars received on the options hedge).
 (Multiple Choice)
4.9/5 (75)
(75) Money Corp.frequently uses a forward hedge to hedge its Malaysian ringgit (MYR)receivables.For the next month,Money has identified its net exposure to the ringgit as being MYR1,500,000.The 30-day forward rate is $.23.Furthermore,Money's financial center has indicated that the possible values of the Malaysian ringgit at the end of next month are $.20 and $.25,with probabilities of.30 and.70,respectively.Based on this information,what is the expected real cost of hedging receivables
(Multiple Choice)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)