



 Chat with AI
Exam 11: Managing Transaction Exposure

Exam 1: Multinational Financial Management: An Overview42 Questions
Exam 2: International Flow of Funds46 Questions
Exam 3: International Financial Markets52 Questions
Exam 4: Exchange Rate Determination45 Questions
Exam 5: Currency Derivatives103 Questions
Exam 6: Government Influence on Exchange Rates68 Questions
Exam 7: International Arbitrage and Interest Rate Parity58 Questions
Exam 8: Relationships among Inflation,Interest Rates,and Exchange Rates37 Questions
Exam 9: Forecasting Exchange Rates58 Questions
Exam 10: Measuring Exposure to Exchange Rate Fluctuations59 Questions
Exam 11: Managing Transaction Exposure63 Questions
Exam 12: Managing Economic Exposure and Translation Exposure43 Questions
Exam 13: Direct Foreign Investment45 Questions
Exam 14: Multinational Capital Budgeting49 Questions
Exam 15: Multinational Restructuring52 Questions
Exam 16: Country Risk Analysis49 Questions
Exam 17: Multinational Cost of Capital and Capital Structure50 Questions
Exam 18: Long-Term Financing45 Questions
Exam 19: Financing International Trade60 Questions
Exam 20: Short-Term Financing48 Questions
Exam 21: International Cash Management38 Questions
Select questions type


The real cost of hedging payables with a forward contract equals:
(Multiple Choice)
4.8/5  (70)
(70) To hedge a ___________ in a foreign currency,a firm may _________ a currency futures contract for that currency.
(Multiple Choice)
4.8/5 (77)
(77) Assume zero transaction costs. If the 90day forward rate of the euro is an accurate estimate of the spot rate 90 days from now,then the real cost of hedging payables will be:
(Multiple Choice)
4.9/5 (78)
(78) Assume that Cooper Co.will not use its cash balances in a money market hedge. When deciding between a forward hedge and a money market hedge,it _______ determine which hedge is preferable before implementing the hedge. It _______ determine whether either hedge will outperform an unhedged strategy before implementing the hedge.
(Multiple Choice)
4.9/5 (85)
(85) FAB Corporation will need 200,000 Canadian dollars (C$)in 90 days to cover a payable position.Currently,a 90-day call option with an exercise price of $.75 and a premium of $.01 is available.Also,a 90-day put option with an exercise price of $.73 and a premium of $.01 is available.FAB plans to purchase options to hedge its payable position.Assuming that the spot rate in 90 days is $.71,what is the net amount paid,assuming FAB wishes to minimize its cost
(Multiple Choice)
4.8/5 (69)
(69) Perkins Corp.will receive 250,000 Jordanian dinar (JOD)in 360 days.The current spot rate of the dinar is $1.48,while the 360-day forward rate is $1.50.How much will Perkins receive in 360 days from implementing a money market hedge (assume any receipts before the date of the receivable are invested)
(Multiple Choice)
4.9/5 (83)
(83) The hedging of a foreign currency for which no forward contract is available with a highly correlated currency for which a forward contract is available is referred to as cross-hedging.
(True/False)
4.7/5 (79)
(79) Assume the following information:
U.S.deposit rate for 1 year = 11%
U.S.borrowing rate for 1 year = 12%
Swiss deposit rate for 1 year = 8%
Swiss borrowing rate for 1 year = 10%
Swiss forward rate for 1 year = $.40
Swiss franc spot rate = $.39
Also assume that a U.S.exporter denominates its Swiss exports in Swiss francs and expects to receive SF600,000 in 1 year.
Using the information above,what will be the approximate value of these exports in 1 year in U.S.dollars given that the firm executes a forward hedge
(Multiple Choice)
4.8/5 (81)
(81) From the perspective Detroit Co.that has payables in Mexican pesos and receivables in Canadian dollars,hedging the payables would be most desirable if the expected real cost of hedging payables is _______,and hedging the receivables would be most desirable if the expected real cost of hedging receivables is _______.
(Multiple Choice)
4.8/5 (77)
(77) A _______ involves an exchange of currencies between two parties,with a promise to reexchange currencies at a specified exchange rate and future date.
(Multiple Choice)
4.9/5 (74)
(74) A futures hedge involves taking a money market position to cover a future payables or receivables position.
(True/False)
5.0/5 (84)
(84) A __________ involves an exchange of currencies between two parties,with a promise to reexchange currencies at a specified exchange rate and future date.
(Multiple Choice)
4.7/5 (75)
(75) If interest rate parity (IRP)exists,then the money market hedge will yield the same result as the options hedge.
(True/False)
4.7/5 (69)
(69) The ______________ hedge is not a technique to eliminate transaction exposure discussed in your text.
(Multiple Choice)
4.9/5 (80)
(80) The forward rate of the Swiss franc is $.50. The spot rate of the Swiss franc is $.48. The following interest rates exist:
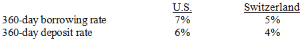 You need to purchase SF200,000 in 360 days. If you use a money market hedge,the amount of dollars you need in 360 days is:
 (Multiple Choice)
4.8/5 (80)
(80) Samsong Inc.needs €1,000,000 in 30 days.Samsong can earn 5 percent annualized on a German security.The current spot rate for the euro is $1.00.Samsong can borrow funds in the U.S.at an annualized interest rate of 6 percent.If Samsong uses a money market hedge to hedge the payable,what is the cost of implementing the hedge
(Multiple Choice)
4.8/5 (77)
(77) Which of the following is the least effective way of hedging transaction exposure in the long run
(Multiple Choice)
4.9/5 (75)
(75) Hedging the position of individual subsidiaries is generally necessary,even if the overall performance of the MNC is already insulated by the offsetting positions between subsidiaries.
(True/False)
4.8/5 (79)
(79) Lorre Company needs 200,000 Canadian dollars (C$)in 90 days and is trying to determine whether or not to hedge this position.Lorre has developed the following probability distribution for the Canadian dollar:
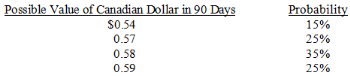 The 90-day forward rate of the Canadian dollar is $.575,and the expected spot rate of the Canadian dollar in 90 days is $.55.If Lorre implements a forward hedge,what is the probability that hedging will be more costly to the firm than not hedging
 (Multiple Choice)
4.7/5 (78)
(78) Assume that Parker Company will receive SF200,000 in 360 days. Assume the following interest rates:
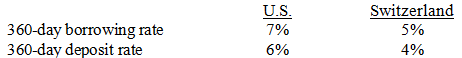 Assume the forward rate of the Swiss franc is $.50 and the spot rate of the Swiss franc is $.48. If Parker Company uses a money market hedge,it will receive _______ in 360 days.
 (Multiple Choice)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)