



 Chat with AI
Exam 11: Managing Transaction Exposure

Exam 1: Multinational Financial Management: An Overview42 Questions
Exam 2: International Flow of Funds46 Questions
Exam 3: International Financial Markets52 Questions
Exam 4: Exchange Rate Determination45 Questions
Exam 5: Currency Derivatives103 Questions
Exam 6: Government Influence on Exchange Rates68 Questions
Exam 7: International Arbitrage and Interest Rate Parity58 Questions
Exam 8: Relationships among Inflation,Interest Rates,and Exchange Rates37 Questions
Exam 9: Forecasting Exchange Rates58 Questions
Exam 10: Measuring Exposure to Exchange Rate Fluctuations59 Questions
Exam 11: Managing Transaction Exposure63 Questions
Exam 12: Managing Economic Exposure and Translation Exposure43 Questions
Exam 13: Direct Foreign Investment45 Questions
Exam 14: Multinational Capital Budgeting49 Questions
Exam 15: Multinational Restructuring52 Questions
Exam 16: Country Risk Analysis49 Questions
Exam 17: Multinational Cost of Capital and Capital Structure50 Questions
Exam 18: Long-Term Financing45 Questions
Exam 19: Financing International Trade60 Questions
Exam 20: Short-Term Financing48 Questions
Exam 21: International Cash Management38 Questions
Select questions type


Assume the following information:
U.S.deposit rate for 1 year = 11%
U.S.borrowing rate for 1 year = 12%
New Zealand deposit rate for 1 year = 8%
New Zealand borrowing rate for 1 year = 10%
New Zealand dollar forward rate for 1 year = $.40
New Zealand dollar spot rate = $.39
Also assume that a U.S.exporter denominates its New Zealand exports in NZ$ and expects to receive NZ$600,000 in 1 year. You are a consultant for this firm.
Using the information above,what will be the approximate value of these exports in 1 year in U.S.dollars given that the firm executes a money market hedge

Free
(Multiple Choice)
4.7/5  (83)
(83) Correct Answer: Verified
D
A forward contract hedge is very similar to a futures contract hedge,except that _________ contracts are commonly used for _________ transactions.
Free
(Multiple Choice)
4.9/5 (63)
(63) Correct Answer:Verified
VerifiedC
The price at which a currency put option allows the holder to sell a currency is called the settlement price.
Free
(True/False)
4.9/5 (80)
(80) Correct Answer:Verified
VerifiedFalse
If interest rate parity exists,and transaction costs do not exist,the money market hedge will yield the same result as the ___________ hedge.
(Multiple Choice)
4.9/5 (74)
(74) Your company will receive C$600,000 in 90 days. The 90day forward rate in the Canadian dollar is $.80. If you use a forward hedge,you will:
(Multiple Choice)
4.8/5 (77)
(77) Foghat Co.has 1,000,000 euros as receivables due in 30 days,and is certain that the euro will depreciate substantially over time. Assuming that the firm is correct,the ideal strategy is to:
(Multiple Choice)
4.9/5 (77)
(77) If Lazer Co.desired to lock in the maximum it would have to pay for its net payables in euros but wanted to be able to capitalize if the euro depreciates substantially against the dollar by the time payment is to be made,the most appropriate hedge would be:
(Multiple Choice)
4.9/5 (70)
(70) Assume zero transaction costs. If the 180day forward rate is an accurate estimate of the spot rate 180 days from now,then the real cost of hedging receivables will be:
(Multiple Choice)
4.8/5 (95)
(95) If interest rate parity exists,and transaction costs do not exist,the _________ hedge will yield the same result as the _________ hedge.
(Multiple Choice)
4.9/5 (71)
(71) Hanson Corp.frequently uses a forward hedge to hedge its British pound (£)payables.For the next quarter,Hanson has identified its net exposure to the pound as being £1,000,000.The 90-day forward rate is $1.50.Furthermore,Hanson's financial center has indicated that the possible values of the British pound at the end of next quarter are $1.57 and $1.59,with probabilities of.50 and.50,respectively.Based on this information,what is the expected real cost of hedging payables
(Multiple Choice)
4.9/5 (72)
(72) Spears Co.will receive SF1,000,000 in 30 days. Use the following information to determine the total dollar amount received (after accounting for the option premium)if the firm purchases and exercises a put option:
Exercise price = $.61
Premium = $.02
Spot rate = $.60
Expected spot rate in 30 days = $.56
30day forward rate = $.62
(Multiple Choice)
4.9/5 (67)
(67) Assume that Jones Co.will need to purchase 100,000 Singapore dollars (S$)in 180 days. Today's spot rate of the S$ is $.50,and the 180day forward rate is $.53. A call option on S$ exists,with an exercise price of $.52,a premium of $.02,and a 180day expiration date. A put option on S$ exists,with an exercise price of $.51,a premium of $.02,and a 180day expiration date. Jones has developed the following probability distribution for the spot rate in 180 days:
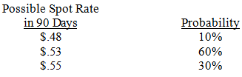 The probability that the forward hedge will result in a higher payment than the options hedge is _______ (include the amount paid for the premium when estimating the U.S.dollars required for the options hedge).
 (Multiple Choice)
4.8/5 (77)
(77) Use the following information to calculate the dollar cost of using a money market hedge to hedge 200,000 pounds of payables due in 180 days. Assume the firm has no excess cash. Assume the spot rate of the pound is $2.02,the 180day forward rate is $2.00.The British interest rate is 5%,and the U.S.interest rate is 4% over the 180day period.
(Multiple Choice)
4.8/5 (82)
(82) If interest rate parity exists and transactions costs are zero,the hedging of payables in euros with a forward hedge will _______.
(Multiple Choice)
4.8/5 (78)
(78) When a perfect hedge is not available to eliminate transaction exposure,the firm may consider methods to at least reduce exposure,such as ___________.
(Multiple Choice)
4.8/5 (74)
(74) If a Salerno Inc.desired to lock in a minimum rate at which it could sell its net receivables in Japanese yen but wanted to be able to capitalize if the yen appreciates substantially against the dollar by the time payment arrives,the most appropriate hedge would be:
(Multiple Choice)
4.9/5 (88)
(88) A ___________ is not a technique for hedging long-term transaction exposure.
(Multiple Choice)
4.8/5 (71)
(71) Samsong Inc.needs €1,000,000 in 30 days.Samsong can earn 5 percent annualized on a German security.The current spot rate for the euro is $1.00.Samsong can borrow funds in the U.S.at an annualized interest rate of 6 percent.If Samsong uses a money market hedge,how much should it borrow in the U.S.
(Multiple Choice)
4.8/5 (91)
(91) A call option exists on British pounds with an exercise price of $1.60,a 90day expiration date,and a premium of $.03 per unit. A put option exists on British pounds with an exercise price of $1.60,a 90day expiration date,and a premium of $.02 per unit. You plan to purchase options to cover your future receivables of 700,000 pounds in 90 days. You will exercise the option in 90 days (if at all). You expect the spot rate of the pound to be $1.57 in 90 days. Determine the amount of dollars to be received,after deducting payment for the option premium.
(Multiple Choice)
5.0/5 (76)
(76) To hedge a contingent exposure,in which an MNC's exposure is contingent on a specific event occurring,the appropriate hedge would be a(n)__________ hedge.
(Multiple Choice)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)