



 Chat with AI
Exam 2: Review of the Accounting Process

Exam 1: Environment and Theoretical Structure of Financial Accounting181 Questions
Exam 2: Review of the Accounting Process 139 Questions
Exam 3: The Balance Sheet and Financial Disclosures168 Questions
Exam 4: The Income Statement, Comprehensive Income, and the Statement of Cash Flows178 Questions
Exam 5: Revenue Recognition316 Questions
Exam 6: Time Value of Money Concepts126 Questions
Exam 7: Cash and Receivables187 Questions
Exam 8: Inventories: Measurement182 Questions
Exam 9: Inventories: Additional Issues153 Questions
Exam 10: Property, Plant, and Equipment and Intangible Assets: Acquisition149 Questions
Exam 11: Property, Plant, and Equipment and Intangible Assets: Utilization and Disposition223 Questions
Exam 12: Investments183 Questions
Exam 13: Current Liabilities and Contingencies155 Questions
Exam 14: Bonds and Long-Term Notes256 Questions
Exam 15: Leases262 Questions
Exam 16: Accounting for Income Taxes176 Questions
Exam 17: Pensions and Other Postretirement Benefits246 Questions
Exam 18: Shareholders Equity179 Questions
Exam 19: Share-Based Compensation and Earnings Per Share231 Questions
Exam 20: Accounting Changes and Error Corrections152 Questions
Exam 21: The Statement of Cash Flows Revisited192 Questions
Select questions type


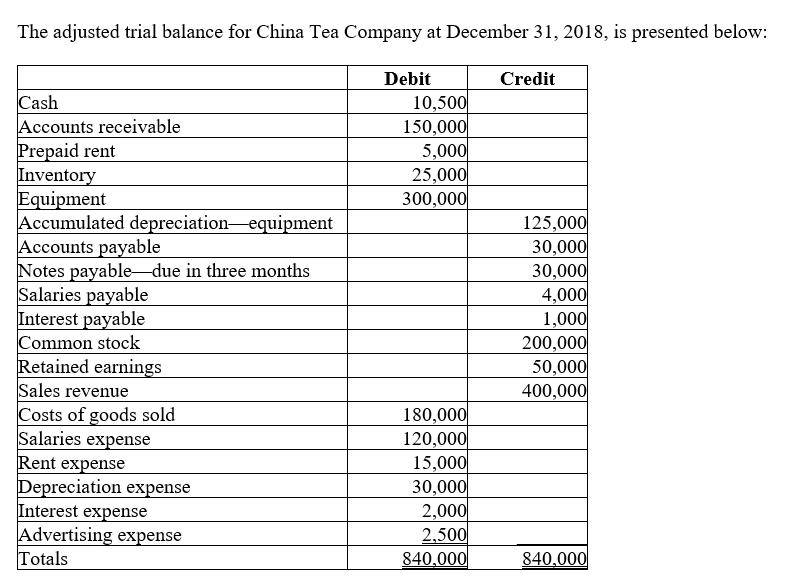 -Prepare the closing entries for China Tea Company for the year ended December 31, 2018.
 (Essay)
4.8/5  (79)
(79) The statement of shareholders' equity discloses the changes in the temporary shareholders' equity accounts.
(True/False)
4.8/5 (82)
(82) The closing process brings all temporary accounts to a zero balance and updates the balance in the retained earnings account.
(True/False)
4.8/5 (89)
(89) Ace Bonding Company purchased merchandise inventory on account. The inventory costs $2,000 and is expected to sell for $3,000. How should Ace record the purchase?
(Multiple Choice)
5.0/5 (95)
(95) The Yankel Corporation's controller prepares adjusting entries only at the end of the fiscal year. The following adjusting entries were prepared on December 31, 2018:
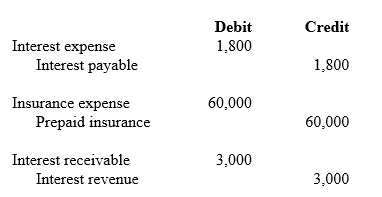 Additional information:
1. The company borrowed $30,000 on June 30, 2018. Principal and interest are due on June 30, 2019. This note is the company's only interest-bearing debt.
2. Insurance for the year on the company's office buildings is $90,000. The insurance is paid in advance.
3. On August 31, 2018, Yankel lent money to a customer. The customer signed a note with principal and interest at 9% due in one year.
Required:
Determine the following:
1. What is the interest rate on the company's note payable?
2. The 2018 insurance payment was made at the beginning of which month?
3. How much did Yankel lend its customer on August 31?
Additional information:
1. The company borrowed $30,000 on June 30, 2018. Principal and interest are due on June 30, 2019. This note is the company's only interest-bearing debt.
2. Insurance for the year on the company's office buildings is $90,000. The insurance is paid in advance.
3. On August 31, 2018, Yankel lent money to a customer. The customer signed a note with principal and interest at 9% due in one year.
Required:
Determine the following:
1. What is the interest rate on the company's note payable?
2. The 2018 insurance payment was made at the beginning of which month?
3. How much did Yankel lend its customer on August 31? (Essay)
4.8/5 (90)
(90) Molly's Auto Detailers maintains its records on the cash basis. During 2018, Molly's collected $72,000 from customers and paid $21,000 in expenses. Depreciation expense of $5,000 would have been recorded on the accrual basis. Over the course of the year, accounts receivable increased $4,000, prepaid expenses decreased $2,000, and accrued liabilities decreased $1,000. Molly's accrual basis net income was:
(Multiple Choice)
4.9/5 (69)
(69) Which of the following accounts has a balance whereby credits normally exceed debits?
(Multiple Choice)
4.9/5 (76)
(76) In its first year of operations Acme Corp. had income before tax of $400,000. Acme made income tax payments totaling $150,000 during the year and has an income tax rate of 40%. What is the balance in income tax payable at the end of the year?
(Multiple Choice)
4.8/5 (84)
(84) Somerset Leasing received $12,000 for 24 months' rent in advance. How should Somerset record this transaction?
(Multiple Choice)
4.9/5 (81)
(81) 1100 Cash 2170 Property taxes payable 1120 Short-term investments 2180 Rent payable 1130 Notes receivable 2200 Long-term notes payable 1140 Accounts receivable 3100 Common stock 1145 Loan receivable 3200 Retained earnings 1150 Interest receivable 5000 Sales revenue 1160 Other accrued receivables 5300 Interest revenue 1200 Inventory 6000 Cost of goods sold 1250 Supplies 6200 Advertising expense 1260 Prepaid expenses 6210 Miscellaneous expense 1320 Buildings and equipment (B\&E) 6220 Depreciation expense 1325 Accumulated depreciation-B\&E 6230 Insurance expense 2110 Short-term notes payable 6240 Property tax expense 2120 Interest payable 6250 Rent expense 2130 Accounts payable 6260 Supplies expense 2140 Deferred revenue 6270 Salaries and wages expense 2150 Salaries and wages payable 6400 Interest expense 2160 Dividends payable 6999 Income summary account
Required:
Using the chart of accounts provided, indicate by account number the account or accounts that would be debited and credited in the following transactions. Also enter the number 1, 2, or 3 to indicate the type of transaction as: (1) an external transaction, (2) an internal transaction recorded as an adjusting journal entry, or (3) a closing entry. The company uses a perpetual inventory system. All prepayments are initially recorded in permanent accounts
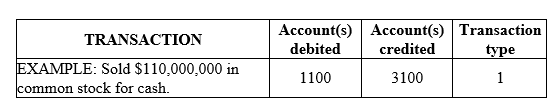 -Salaries and wages have been recognized but are unpaid at the end of an accounting period.
 (Essay)
4.8/5 (72)
(72) 1100 Cash 2170 Property taxes payable 1120 Short-term investments 2180 Rent payable 1130 Notes receivable 2200 Long-term notes payable 1140 Accounts receivable 3100 Common stock 1145 Loan receivable 3200 Retained earnings 1150 Interest receivable 5000 Sales revenue 1160 Other accrued receivables 5300 Interest revenue 1200 Inventory 6000 Cost of goods sold 1250 Supplies 6200 Advertising expense 1260 Prepaid expenses 6210 Miscellaneous expense 1320 Buildings and equipment (B\&E) 6220 Depreciation expense 1325 Accumulated depreciation-B\&E 6230 Insurance expense 2110 Short-term notes payable 6240 Property tax expense 2120 Interest payable 6250 Rent expense 2130 Accounts payable 6260 Supplies expense 2140 Deferred revenue 6270 Salaries and wages expense 2150 Salaries and wages payable 6400 Interest expense 2160 Dividends payable 6999 Income summary account
Required:
Using the chart of accounts provided, indicate by account number the account or accounts that would be debited and credited in the following transactions. Also enter the number 1, 2, or 3 to indicate the type of transaction as: (1) an external transaction, (2) an internal transaction recorded as an adjusting journal entry, or (3) a closing entry. The company uses a perpetual inventory system. All prepayments are initially recorded in permanent accounts
-Collected a note receivable at maturity, including the interest that had already been accrued.
-Collected a note receivable at maturity, including the interest that had already been accrued. (Essay)
4.8/5 (101)
(101) 1100 Cash 2170 Property taxes payable 1120 Short-term investments 2180 Rent payable 1130 Notes receivable 2200 Long-term notes payable 1140 Accounts receivable 3100 Common stock 1145 Loan receivable 3200 Retained earnings 1150 Interest receivable 5000 Sales revenue 1160 Other accrued receivables 5300 Interest revenue 1200 Inventory 6000 Cost of goods sold 1250 Supplies 6200 Advertising expense 1260 Prepaid expenses 6210 Miscellaneous expense 1320 Buildings and equipment (B\&E) 6220 Depreciation expense 1325 Accumulated depreciation-B\&E 6230 Insurance expense 2110 Short-term notes payable 6240 Property tax expense 2120 Interest payable 6250 Rent expense 2130 Accounts payable 6260 Supplies expense 2140 Deferred revenue 6270 Salaries and wages expense 2150 Salaries and wages payable 6400 Interest expense 2160 Dividends payable 6999 Income summary account
Required:
Using the chart of accounts provided, indicate by account number the account or accounts that would be debited and credited in the following transactions. Also enter the number 1, 2, or 3 to indicate the type of transaction as: (1) an external transaction, (2) an internal transaction recorded as an adjusting journal entry, or (3) a closing entry. The company uses a perpetual inventory system. All prepayments are initially recorded in permanent accounts
-Invested idle cash in short-term money market funds.
-Invested idle cash in short-term money market funds. (Essay)
4.9/5 (79)
(79) Presented below is income statement information of the Nebraska Corporation for the year ended December 31, 2018. 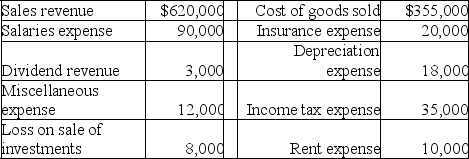 Required:
Prepare the necessary closing entries at December 31, 2018.
Required:
Prepare the necessary closing entries at December 31, 2018. (Essay)
5.0/5 (92)
(92) Adjusting journal entries are recorded at the end of any period when financial statements are prepared.
(True/False)
4.8/5 (82)
(82) Hughes Aircraft sold a four-passenger airplane for $380,000, receiving a $50,000 down payment and a 12% note for the balance. The journal entry to record this sale would include a:
(Multiple Choice)
4.7/5 (88)
(88) The account titles to be responded to are provided in no particular order. Assume that all accounts have normal balances according to whether the account is increased by a debit or increased by a credit.
Required:
In column A, indicate whether a debit will:
1. Increase the account balance, or
2. Decrease the account balance.
In column B, classify each account according to the following scheme. For contra accounts, indicate the classification of the account to which it relates.
1. A current asset in the balance sheet.
2. A noncurrent asset in the balance sheet.
3. A current liability in the balance sheet.
4. A long-term liability in the balance sheet.
5. A permanent equity account in the balance sheet.
6. A revenue account in the income statement.
7. An expense account shown in the income statement.
8. Account does not appear in either the balance sheet or the income statement.
 -Retained earnings
 (Short Answer)
4.8/5 (76)
(76) Compared to the accrual basis of accounting, the cash basis of accounting produces a higher amount of income by the net decrease during the accounting period of: 
(Multiple Choice)
4.8/5 (77)
(77) 1100 Cash 2170 Property taxes payable 1120 Short-term investments 2180 Rent payable 1130 Notes receivable 2200 Long-term notes payable 1140 Accounts receivable 3100 Common stock 1145 Loan receivable 3200 Retained earnings 1150 Interest receivable 5000 Sales revenue 1160 Other accrued receivables 5300 Interest revenue 1200 Inventory 6000 Cost of goods sold 1250 Supplies 6200 Advertising expense 1260 Prepaid expenses 6210 Miscellaneous expense 1320 Buildings and equipment (B\&E) 6220 Depreciation expense 1325 Accumulated depreciation-B\&E 6230 Insurance expense 2110 Short-term notes payable 6240 Property tax expense 2120 Interest payable 6250 Rent expense 2130 Accounts payable 6260 Supplies expense 2140 Deferred revenue 6270 Salaries and wages expense 2150 Salaries and wages payable 6400 Interest expense 2160 Dividends payable 6999 Income summary account
Required:
Using the chart of accounts provided, indicate by account number the account or accounts that would be debited and credited in the following transactions. Also enter the number 1, 2, or 3 to indicate the type of transaction as: (1) an external transaction, (2) an internal transaction recorded as an adjusting journal entry, or (3) a closing entry. The company uses a perpetual inventory system. All prepayments are initially recorded in permanent accounts
-Sold merchandise to a customer in exchange for a promissory note.
-Sold merchandise to a customer in exchange for a promissory note. (Essay)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)