



 Chat with AI
Exam 18: Option Valuation and Strategies

Exam 1: An Introduction to Investments19 Questions
Exam 2: Securities Markets77 Questions
Exam 3: The Time Value of Money41 Questions
Exam 4: Financial Planning, Taxation and the Efficiency of Financial Markets57 Questions
Exam 5: Risk and Portfolio Management56 Questions
Exam 6: Investment Companies: Mutual Funds65 Questions
Exam 7: Closed-End Investment Companies, Real Estate Investment Trusts Reits, and Exchange-Traded Funds Etfs50 Questions
Exam 8: Stock104 Questions
Exam 9: The Valuation of Common Stock35 Questions
Exam 10: Investment Returns and Aggregate Measures of Stock Markets42 Questions
Exam 11: The Macroeconomic Environment for Investment Decisions36 Questions
Exam 12: Behavioral Finance and Technical Analysis34 Questions
Exam 13: The Bond Market64 Questions
Exam 14: The Valuation of Fixed-Income Securities64 Questions
Exam 15: Government Securities50 Questions
Exam 16: Convertible Bonds and Convertible Preferred Stock47 Questions
Exam 17: An Introduction to Options85 Questions
Exam 18: Option Valuation and Strategies40 Questions
Exam 19: Commodity and Financial Futures47 Questions
Exam 20: Financial Planning and Investing in an Efficient Market Context22 Questions
Select questions type


If an investor sells a stock short, that individual reduces the risk of loss by

Free
(Multiple Choice)
4.9/5  (78)
(78) Correct Answer: Verified
B
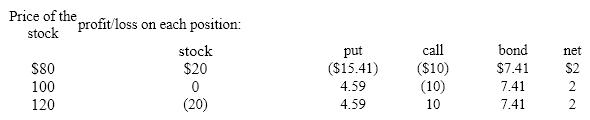
Put-call parity basically says that combination of a put, a call, and a risk-free bond must be the same value as the underlying stock. If not, at least one market is in disequilibrium. The resulting arbitrage alters the securities' prices until the value of the call plus the bond is equal to the prices of the put plus the stock. Currently, the price of a stock is $100 while the price of a call option at $100 is $10; the price of the put option is $4.59, and the rate of interest is 8 percent, so that the investor may purchase a $100 discounted note for $92.59.
a. Do these prices indicate that the financial markets are in equilibrium? Show all calculations.
b. An arbitrage opportunity exists, but if the position is set up incorrectly, losses will be sustained. Verify that a loss will be sustained if the arbitrage is set up incorrectly. Calculate the results based on stock prices of $80, $100, and $120 as of the expiration date of the options.
Free
(Essay)
4.9/5 (84)
(84) Correct Answer:Verified
Verifieda. Price of the stock + put: $100 + $4.59 = $104.59
Price of the call + bond: $10 + 92.59 = $102.59
An arbitrage opportunity exists; short the stock and put and purchase the call and the bond.
b. Profit on the arbitrage position:
Selling a call and purchasing a treasury bill produces the same returns as buying a stock.
(True/False)
4.8/5 (71)
(71) According to the Black/Scholes option valuation model, the value of a call option increases if
(Multiple Choice)
4.8/5 (88)
(88) If the hedge ratio is 0.7, the number of call options necessary to offset a long position in a stock is 7.0.
(True/False)
4.8/5 (78)
(78) The Black/Scholes option valuation model divides the option's strike price by the probability that the option will be exercised.
(True/False)
4.8/5 (72)
(72) Put-call parity explains why a change in interest rates by the Federal Reserve affects stock and option prices.
(True/False)
4.7/5 (74)
(74) If a call is overvalued, put-call parity suggests that the investor should
(Multiple Choice)
5.0/5 (91)
(91) The price of a stock is $46 and the prices of call options to buy the stock at $45 and $50 are $6 and $3, respectively. What are the potential profits and losses when the price of the stock is $40, $45, $50, and $55 if the investor buys the call at $45 and sells the call at $50?
(Essay)
5.0/5 (92)
(92) The "collar strategy" is used to lock-in profits from an increase in the price of a stock.
(True/False)
4.8/5 (88)
(88) A call option exists to buy a stock at $25 a share. According to the Black/Scholes option valuation model, what is the value of the call
a. if the price of the stock is $25, the interest rate is 8 percent, the option expires in three months, and the standard deviation of the stock's return is 0.20 (20 percent)?
b. if the price of the stock is $25, the interest rate is 6 percent, the option expires in three months, and the standard deviation of the stock's return is 0.20 (20 percent)?
c. if the price of the stock is $27, the interest rate is 8 percent, the option expires in three months, and the standard deviation of the stock's return is 0.20 (20 percent)?
(Essay)
4.7/5 (89)
(89) According to the Black/Scholes option valuation model, the value of a call option rises as interest rates increase.
(True/False)
4.9/5 (83)
(83) To construct a bear spread, the investor buys a call option and shorts the stock.
(True/False)
4.7/5 (86)
(86) An investor owns 1,000 shares of stock but anticipates its price may decline. To reduce the risk of loss, how many call options must be sold if the hedge ratio is 0.7?
(Essay)
4.7/5 (81)
(81) If the investor anticipates that the price of stock will be stable, he or she may
(Multiple Choice)
4.8/5 (76)
(76) If an individual sells a stock short, that investor is protected from a large increase in the price of the stock by selling a call option.
(True/False)
4.8/5 (89)
(89) According to put-call parity, if a stock is overpriced, the investor should sell the stock short, sell the put, buy the call, and buy the bond.
(True/False)
4.9/5 (90)
(90) According to the Black/Scholes option valuation model, a call option's value decreases if
(Multiple Choice)
4.7/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)