



 Chat with AI
Exam 8: Corporate Formation, Reorganization, and Liquidation

Exam 1: Business Income, Deductions, and Accounting Methods105 Questions
Exam 2: Property Acquisition and Cost Recovery86 Questions
Exam 3: Property Dispositions111 Questions
Exam 4: Business Entities Overview81 Questions
Exam 5: Corporate Operations114 Questions
Exam 6: Accounting for Income Taxes106 Questions
Exam 7: Corporate Taxation: Non-Liquidating Distributions101 Questions
Exam 8: Corporate Formation, Reorganization, and Liquidation108 Questions
Exam 9: Forming and Operating Partnerships114 Questions
Exam 10: Dispositions of Partnership Interests and Partnership Distributions94 Questions
Exam 11: S Corporations132 Questions
Exam 12: State and Local Taxes114 Questions
Exam 13: The Us Taxation of Multinational Transactions88 Questions
Exam 14: Transfer Taxes and Wealth Planning114 Questions
Select questions type


Which of the following statements best describes the continuity of interest principle as it applies to a tax-deferred acquisition?

Free
(Multiple Choice)
4.7/5  (74)
(74) Correct Answer: Verified
B
Which of the following statements best describes the impact of receiving boot in a §351 transaction?
Free
(Multiple Choice)
5.0/5 (67)
(67) Correct Answer:Verified
VerifiedB
The definition of property as it relates to a §351 transaction includes money.
Free
(True/False)
4.8/5 (84)
(84) Correct Answer:Verified
VerifiedTrue
Sue transferred 100 percent of her stock in Oakland Company to Applegate Corporation in a Type A merger. In exchange she received stock in Applegate with a fair market value of $800,000 plus $400,000 in cash. Sue's tax basis in the Oakland stock was $1,500,000. What amount of gain or loss does Sue recognize in the exchange and what is her basis in the Applegate stock she receives?
(Essay)
4.9/5 (66)
(66) To meet the control test under §351, taxpayers transferring property to a corporation must in aggregate own 80 percent or more of the corporation's voting stock and 80 percent of each class of nonvoting stock after the transfer.
(True/False)
4.9/5 (70)
(70) Continuity of interest as it relates to a tax reorganization focuses on the aggregate equity received by the shareholders of the target corporation in the transaction.
(True/False)
4.9/5 (85)
(85) Which of the following statements best describes the tax consequences of a §338 election?
(Multiple Choice)
4.8/5 (70)
(70) A taxpayer always will have a tax basis in boot received in a §351 transaction equal to its fair market value.
(True/False)
4.8/5 (67)
(67) Antoine transfers property with a tax basis of $500 and a fair market value of $600 to a corporation in exchange for stock with a fair market value of $550 in a transaction that qualifies for deferral under section 351. The corporation assumed a liability of $50 on the property transferred. What is Antoine's tax basis in the stock received in the exchange?
(Multiple Choice)
4.9/5 (69)
(69) A reverse triangular reorganization requires that the target shareholders receive voting stock of the acquiring corporation.
(True/False)
4.8/5 (95)
(95) Sami transferred property with a fair market value of $600 and a tax basis of $300 to a corporation in exchange for stock with a fair market value of $600. In addition, Sami received stock with a fair market value of $50 in exchange for services she provided to the corporation in the incorporation process. Which of the following statements best describes the tax result to Sami because of the exchanges?
(Multiple Choice)
4.8/5 (80)
(80) April transferred 100 percent of her stock in June Company to March Corporation in a taxable merger. In exchange she received stock in March with a fair market value of $400,000 plus $1,200,000 in cash. April's tax basis in the June stock was $2,000,000. What amount of loss does April recognize in the exchange and what is her basis in the March stock she receives?
(Essay)
4.7/5 (79)
(79) Casey transfers property with a tax basis of $2,500 and a fair market value of $6,900 to a corporation in exchange for stock with a fair market value of $5,300 and $700 in cash in a transaction that qualifies for deferral under section 351. The corporation assumed a liability of $900 on the property transferred. Casey also incurred selling expenses of $316. What is the amount realized by Casey in the exchange?
(Multiple Choice)
4.9/5 (77)
(77) Phillip incorporated his sole proprietorship by transferring inventory, a building, and land to the corporation in return for 100 percent of the corporation's stock. The property transferred to the corporation had the following fair market values and tax-adjusted bases.
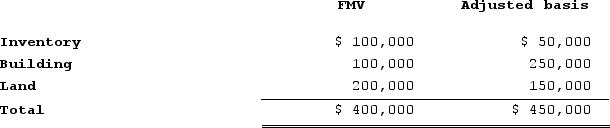 The fair market value of the corporation's stock received in the exchange was $400,000. The transaction met the requirements to be tax-deferred under §351.
a. What amount of net gain or loss does Phillip realize on the transfer of the property to his corporation?
b. What amount of gain or loss does Phillip recognize on the transfer of the property to his corporation?
c. What is the corporation's adjusted basis in each of the assets received in the exchange?
The fair market value of the corporation's stock received in the exchange was $400,000. The transaction met the requirements to be tax-deferred under §351.
a. What amount of net gain or loss does Phillip realize on the transfer of the property to his corporation?
b. What amount of gain or loss does Phillip recognize on the transfer of the property to his corporation?
c. What is the corporation's adjusted basis in each of the assets received in the exchange? (Essay)
4.8/5 (69)
(69) Rachelle transfers property with a tax basis of $980 and a fair market value of $1,280 to a corporation in exchange for stock with a fair market value of $720 and $88 incash in a transaction that qualifies for deferral under section 351. The corporation assumed a liability of $472 on the property transferred. What is the corporation's tax basis in the property received in the exchange?
(Multiple Choice)
4.8/5 (74)
(74) Rachelle transfers property with a tax basis of $800 and a fair market value of $900 to a corporation in exchange for stock with a fair market value of $750 and $50 in cash in a transaction that qualifies for deferral under section 351. The corporation assumed a liability of $100 on the property transferred. What is the corporation's tax basis in the property received in the exchange?
(Multiple Choice)
4.8/5 (72)
(72) Simone transferred 100 percent of her stock in Purple Company to Plum Corporation in a Type A merger. In exchange, she received stock in Plum with a fair market value of $500,000 plus $500,000 in cash. Simone's tax basis in the Purple stock was $200,000. What amount of gain does Simone recognize in the exchange and what is her basis in the Plum stock she receives?
(Multiple Choice)
4.9/5 (84)
(84) Which of the following statements best describes the tax law approach to recognizing gain or loss realized in an exchange?
(Multiple Choice)
4.7/5 (69)
(69) Maria defers $100 of gain realized in a §351 transaction. The stock she receives in the exchange has a fair market value of $500. Maria's tax basis in the stock will be $400.
(True/False)
4.7/5 (90)
(90) Which of the following statements best describes the tax results to a shareholder in a §351 transaction when liabilities on property transferred to the corporation are assumed by the corporation?
(Multiple Choice)
4.7/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)