



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law208 Questions
Exam 2: Working With the Tax Law102 Questions
Exam 3: Computing the Tax166 Questions
Exam 4: Gross Income: Concepts and Inclusions122 Questions
Exam 5: Gross Income: Exclusions111 Questions
Exam 6: Deductions and Losses: in General148 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses116 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion113 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses126 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions103 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments103 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges250 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions156 Questions
Exam 15: Taxing Business Income65 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules137 Questions
Exam 18: Corporations: Organization and Capital Structure107 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation183 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations67 Questions
Exam 21: Partnerships231 Questions
Exam 22: S Corporations121 Questions
Exam 23: Exempt Entities129 Questions
Exam 24: Multistate Corporate Taxation184 Questions
Exam 25: Taxation of International Transactions128 Questions
Exam 26: Tax Practice and Ethics174 Questions
Exam 27: The Federal Gift and Estate Taxes145 Questions
Exam 28: Income Taxation of Trusts and Estates154 Questions
Select questions type


Parent Corporation owns all of the stock of Junior Corporation, a Delaware passive investment company. Parent operates strictly in nonunitary State B, which levies a 9% income tax. This year, Junior earned $200,000 of portfolio interest income and paid a $150,000 dividend to Parent. In which state(s) will the interest income create an income tax liability?
(Multiple Choice)
4.8/5  (74)
(74) Match each of the following items with the appropriate description in determining whether sales/use tax typically must be collected.
-Computing services purchased by a business.
(Multiple Choice)
4.9/5 (79)
(79) Match each of the following events considered independently to its likely effect on WillCo's various apportionment factors. WillCo is based in Q and has customers in Q, R, and S. To this point, WillCo has not established nexus with S. More than one choice may be correct.
-R adopts an increase in its statutory corporate income tax rates.
(Multiple Choice)
4.8/5 (89)
(89) Ting, a regional sales manager, works from her office in State W. Her region includes several states as indicated in the following sales report. Determine how much of Ting's $300,000 compensation is assigned to the payroll factor of State W. State Sales Generated Ting's Time Spent There \ 1,000,000 15\% 5,000,000 55\% 4,000,000 30\% \1 0,000,000 100\%
(Multiple Choice)
5.0/5 (86)
(86) Boot Corporation is subject to income tax in States A and B. Boot's operations generated $200,000 of apportionable income, and its sales and payroll activity and average property owned in each of the states is as follows: State A State B T otals Sales \ 200,000 \ 600,000 \ 800,000 Payroll 100,000 50,000 150,000 Property 200,000 50,000 250,000 How much more (less) of Boot's income is subject to State A income tax if, instead of using an equally weighted three-factor apportionment formula, State A uses a formula with a double-weighted sales factor?
(Multiple Choice)
4.9/5 (87)
(87) The benefits of a passive investment company employed in a nonunitary state typically include:
(Multiple Choice)
4.9/5 (80)
(80) José Corporation realized $900,000 taxable income from the sales of its products in States X and Z. José's activities in both states establish nexus for income tax purposes. José's sales, payroll, and property among the states include the following: State X State Totals Sales \ 1,500,000 \ 1,000,000 \ 2,500,000 Property 500,000 -0- 500,000 Payroll 2,000,000 -0- 2,000,000 Z utilizes a double-weighted sales factor in its three-factor apportionment formula. How much of José's taxable income is apportioned to Z?
(Multiple Choice)
4.9/5 (81)
(81) If a state follows Federal income tax rules, the state's tax compliance and enforcement become easier to accomplish.
(True/False)
5.0/5 (70)
(70) What is the significance of the term nexus when discussing state income taxation?
(Essay)
4.8/5 (85)
(85) Mercy Corporation, headquartered in State F, sells wireless computer devices, including keyboards and bar code readers. Mercy's degree of operations is sufficient to establish income tax nexus only in States E and F. Determine its sales factor in those states.
State E applies a throwback rule to sales, but State F does not. State G has not adopted an income tax to date. Mercy reported the following sales for the year. All of the goods were shipped from Mercy's F manufacturing facilities. 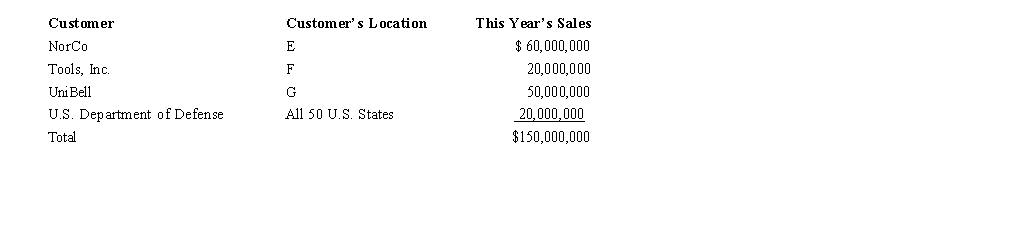
(Essay)
4.9/5 (71)
(71) State Q wants to increase its income tax collections, but politically it would be unwise to raise taxes on in-state individuals or businesses. State Q currently follows all UDITPA rules and employs an equally weighted three-factor apportionment formula. State Q allocates nonbusiness income amounts.
Identify some changes to the income tax apportionment formula that would shift the scheduled income tax increases to out-of-state businesses.
(Essay)
4.8/5 (74)
(74) Compute Still Corporation's State Q taxable income and tax liability for the year. Addition modifications \ 70,000 Allocated income - total \ 80,000 Allocated income - State Q \ 60,000 Allocated income - State P \ 20,000 Apportionment percentage - State Q 40\% Federal taxable income \ 500,000 State tax credits \ 11,000 Subtraction modifications \ 30,000 Tax rate 5\%
(Essay)
4.9/5 (66)
(66) Match each of the following terms with the appropriate description in the state income tax formula. Apply the
UDITPA rules in your responses.
-Dividend income from P & G stock held.
(Multiple Choice)
5.0/5 (76)
(76) Under the UDITPA's concept, sales are assumed to take place at the point of delivery as opposed to the location at which the shipment originates.
(Short Answer)
4.9/5 (78)
(78) Match each of the following terms with the appropriate description in the state income tax formula. Apply the
UDITPA rules in your responses.
-Deduction for advertising expenditures.
(Multiple Choice)
4.8/5 (76)
(76) By making a water's edge election, a multinational taxpayer can limit the reach of unitary principles to the apportionment factors and income of its U.S. and E.U. affiliates.
(True/False)
4.9/5 (72)
(72) Dott Corporation generated $300,000 of state taxable income from selling its mapping software in States A and B.
For the taxable year, the corporation's activities within the two states were as follows: State A State B Total Sales \ 500,000 \ 1,500,000 \ 2,000,000 Property 250,000 -0- 250,000 Payroll 200,000 300,000 500,000 Dott has determined that it is subject to tax in both A and B. Both states utilize a three-factor apportionment formula that equally weights sales, property, and payroll. The rates of corporate income tax imposed in States A and B are
7% and 10%, respectively. Determine Dott's total state income tax liability.
(Essay)
4.8/5 (84)
(84) Under Public Law 86-272, a state is prohibited from income taxing the income of a business if the only connection with the state is the of orders for sales of tangible personal property that are sent outside the state for approval or rejection.
(Short Answer)
4.9/5 (86)
(86) Which of the following is not immune from state income taxation even if P.L. 86-272 is in effect?
(Multiple Choice)
4.7/5 (75)
(75) P.L. 86-272 (does/does not) create income-tax nexus when the sales representative approves a sale at the customer's location.
(Short Answer)
4.9/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)