



 Chat with AI
Exam 18: Corporations: Organization and Capital Structure

Exam 1: Understanding and Working With the Federal Tax Law208 Questions
Exam 2: Working With the Tax Law102 Questions
Exam 3: Computing the Tax166 Questions
Exam 4: Gross Income: Concepts and Inclusions122 Questions
Exam 5: Gross Income: Exclusions111 Questions
Exam 6: Deductions and Losses: in General148 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses116 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion113 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses126 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions103 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments103 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges250 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions156 Questions
Exam 15: Taxing Business Income65 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules137 Questions
Exam 18: Corporations: Organization and Capital Structure107 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation183 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations67 Questions
Exam 21: Partnerships231 Questions
Exam 22: S Corporations121 Questions
Exam 23: Exempt Entities129 Questions
Exam 24: Multistate Corporate Taxation184 Questions
Exam 25: Taxation of International Transactions128 Questions
Exam 26: Tax Practice and Ethics174 Questions
Exam 27: The Federal Gift and Estate Taxes145 Questions
Exam 28: Income Taxation of Trusts and Estates154 Questions
Select questions type


When Pheasant Corporation was formed under § 351, Kristen transferred property (basis of $26,000 and fair market value of $22,500) for § 1244 stock. Kristen's basis in the Pheasant stock is $26,000. Three years later, Pheasant Corporation goes bankrupt and its stock becomes worthless. Kristen, who is single, owned the stock as an investment. Kristen's loss is:

Free
(Multiple Choice)
4.8/5  (77)
(77) Correct Answer: Verified
B
Hunter and Warren form Tan Corporation. Hunter transfers equipment (basis of $210,000 and fair market value of $180,000) while Warren transfers land (basis of $15,000 and fair market value of $150,000) and $30,000 of cash. Each receives 50% of Tan's stock. As a result of these transfers:
Free
(Multiple Choice)
4.8/5 (92)
(92) Correct Answer:Verified
VerifiedB
Kim, a real estate dealer, and others form Eagle Corporation under § 351. Kim contributes inventory (land held for resale) in return for Eagle stock. The holding period for the stock includes the holding period of the inventory.
Free
(True/False)
4.9/5 (75)
(75) Correct Answer:Verified
VerifiedFalse
Rob and Yi form Bluebird Corporation with the following investments. 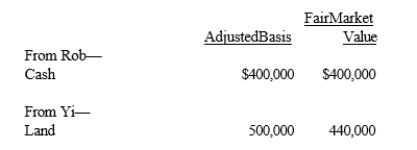 Each receives 50% of Bluebird's stock. In addition, Yi receives cash of $40,000. One result of these transfers is that Yi has a:
 (Multiple Choice)
4.7/5 (80)
(80) How is the transfer of liabilities in a property transaction generally treated for tax purposes? How is a transfer of liabilities generally treated in a § 351 transaction? What exceptions could arise to this usual treatment in a § 351 setting?
(Essay)
4.7/5 (75)
(75) Ira, a calendar year taxpayer, purchases as an investment stock in Redbird Corporation on November 3, 2018. On February 2, 2019, Redbird Corporation is declared bankrupt, and Ira's stock becomes worthless. Presuming § 1244 (stock in a small business corporation) does not apply, Ira has a short-term capital loss for 2019.
(True/False)
4.9/5 (81)
(81) Under Federal tax law, a bias for corporate issuers exists in favor of debt as compared to equity when financing the operations of a corporation.
(True/False)
4.8/5 (80)
(80) Karen formed Grebe Corporation with an investment of $100,000 cash for which she received $10,000 in stock and
$90,000 in 7% interest-bearing bonds maturing in 10 years. A few years later, Karen loaned Grebe an additional
$60,000 on open account. Grebe becomes insolvent in the current year and is adjudged bankrupt. Karen was the president of Grebe Corporation and was paid an annual salary of $50,000 for the past three years. Karen has no other employment. How will Karen treat her losses for tax purposes?
(Essay)
4.8/5 (70)
(70) Earl and Mary form Crow Corporation. Earl transfers property, basis of $200,000 and value of $1,600,000, for 50 shares in Crow Corporation. Mary transfers property, basis of $80,000 and value of $1,480,000, and agrees to serve as manager of Crow for one year; in return Mary receives 50 shares of Crow. The value of Mary's services is $120,000. With respect to the transfers:
(Multiple Choice)
4.8/5 (75)
(75) Kirby and Helen form Red Corporation. Kirby transfers property, basis of $20,000 and value of $300,000, for 100 shares in Red Corporation. Helen transfers property, basis of $40,000 and value of $280,000, and provides legal services in organizing the corporation. The value of her services is $20,000. In return Helen receives 100 shares in Red Corporation. Regarding these transfers:
(Multiple Choice)
4.8/5 (96)
(96) Joe and Kay form Gull Corporation. Joe transfers cash of $250,000 for 200 shares in Gull Corporation. Kay transfers property with a basis of $50,000 and fair market value of $240,000. She agrees to accept 200 shares in Gull Corporation for the property and for providing bookkeeping services to the corporation in its first year of operation. The value of Kay's services is $10,000. With respect to the transfer:
(Multiple Choice)
5.0/5 (92)
(92) A transferor who receives stock for both property and services may not be included in the control group in determining whether an exchange meets the requirements of § 351.
(True/False)
4.7/5 (79)
(79) Wren Corporation (a minority shareholder in Lark Corporation) has made loans to Lark Corporation that become worthless in the current year.
(Multiple Choice)
4.9/5 (79)
(79) A person who performs services for a corporation in exchange for stock cannot be treated as a member of the transferring group even if that person also transfers some property to the corporation.
(True/False)
4.9/5 (70)
(70) A corporation's holding period for property received under § 351 includes the holding period of the transferor shareholder.
(True/False)
4.9/5 (77)
(77) Mary transfers a building (adjusted basis of $15,000 and fair market value of $90,000) to White Corporation. In return, Mary receives 80% of White Corporation's stock (worth $65,000) and an automobile (fair market value of $5,000). In addition, there is an outstanding mortgage of $20,000 (taken out 15 years ago) on the building, which
White Corporation assumes. With respect to this transaction:
(Multiple Choice)
4.9/5 (75)
(75) Blue Corporation (a seller of goods to Cedar Corporation) has made loans to Cedar Corporation, which become worthless in the current year.
(Multiple Choice)
4.9/5 (80)
(80) Rita forms Finch Corporation by transferring land (basis of $125,000; fair market value of $750,000) which is subject to a mortgage of $375,000. Two weeks prior to incorporating Finch, Rita borrows $125,000 for personal purposes
and gives the lender a second mortgage on the land. Finch Corporation issues stock worth $250,000 to Rita and assumes the two mortgages on the land. What are the tax consequences to Rita and to Finch Corporation?
(Essay)
4.8/5 (89)
(89) Silver Corporation receives $1 million in cash from Madison County as an inducement to expand its operations there.
Within one year, Silver spends $1.5 million to enlarge its existing plant. Silver Corporation's basis in the expansion is
$500,000.
(True/False)
4.8/5 (64)
(64) Jane transfers property (basis of $180,000 and fair market value of $500,000) to Green Corporation for 80% of its stock (worth $425,000) and a long-term note (worth $75,000) executed by Green Corporation and made payable to Jane. As a result of the transfer:
(Multiple Choice)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)