



 Chat with AI
Exam 18: Corporations: Organization and Capital Structure

Exam 1: Understanding and Working With the Federal Tax Law208 Questions
Exam 2: Working With the Tax Law102 Questions
Exam 3: Computing the Tax166 Questions
Exam 4: Gross Income: Concepts and Inclusions122 Questions
Exam 5: Gross Income: Exclusions111 Questions
Exam 6: Deductions and Losses: in General148 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses116 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion113 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses126 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions103 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments103 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges250 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions156 Questions
Exam 15: Taxing Business Income65 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules137 Questions
Exam 18: Corporations: Organization and Capital Structure107 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation183 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations67 Questions
Exam 21: Partnerships231 Questions
Exam 22: S Corporations121 Questions
Exam 23: Exempt Entities129 Questions
Exam 24: Multistate Corporate Taxation184 Questions
Exam 25: Taxation of International Transactions128 Questions
Exam 26: Tax Practice and Ethics174 Questions
Exam 27: The Federal Gift and Estate Taxes145 Questions
Exam 28: Income Taxation of Trusts and Estates154 Questions
Select questions type


In a § 351 transaction, if a transferor receives consideration other than stock, the transaction can be taxable.
(True/False)
4.9/5  (89)
(89) In general, the basis of property to a corporation in a transfer that qualifies as a nontaxable exchange under § 351 is the basis in the hands of the transferor shareholder decreased by the amount of any gain recognized on the transfer.
(True/False)
4.9/5 (72)
(72) A shareholder contributes land to his wholly owned corporation but receives no stock in return. The corporation has a zero basis in the land.
(True/False)
4.7/5 (85)
(85) A taxpayer transfers assets and liabilities to a corporation in return for its stock. If the liabilities exceed the basis of the assets transferred, the taxpayer will have a negative basis in the stock.
(True/False)
4.8/5 (64)
(64) When a taxpayer incorporates her business, she transfers several liabilities to the corporation. If one of the liabilities is personal in origin, the release of only that liability is treated as boot.
(True/False)
4.9/5 (82)
(82) Leah transfers equipment (basis of $400,000 and fair market value of $500,000) for additional stock in Crow Corporation. After the transfer, Leah owns 80% of Crow's stock. Associated with the equipment is § 1245 depreciation recapture potential of $70,000. As a result of the transfer:
(Multiple Choice)
4.8/5 (77)
(77) Nancy, Guy, and Rod form Goldfinch Corporation with the following consideration. 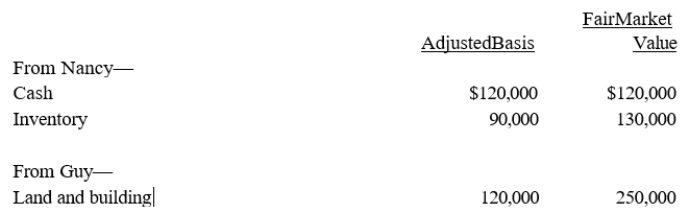 From Rod- Legal and accounting services to incorporate -0- 50,000
Goldfinch issues its 500 shares of stock as follows: 250 to Nancy, 200 to Guy, and 50 to Rod. In addition, Guy gets
$50,000 in cash.
a. Does Nancy, Guy, or Rod recognize gain (or income)?
b. What basis does Guy have in the Goldfinch stock?
c. What basis does Goldfinch Corporation have in the inventory? In the land and building?
d. What basis does Rod have in the Goldfinch stock?
From Rod- Legal and accounting services to incorporate -0- 50,000
Goldfinch issues its 500 shares of stock as follows: 250 to Nancy, 200 to Guy, and 50 to Rod. In addition, Guy gets
$50,000 in cash.
a. Does Nancy, Guy, or Rod recognize gain (or income)?
b. What basis does Guy have in the Goldfinch stock?
c. What basis does Goldfinch Corporation have in the inventory? In the land and building?
d. What basis does Rod have in the Goldfinch stock? (Essay)
4.9/5 (77)
(77) For transfers falling under § 351, what are the holding period rules for stock received by the shareholder and for the assets transferred to the corporation?
(Essay)
4.8/5 (66)
(66) Four individuals form Chickadee Corporation under § 351. Two of these individuals, Jane and Walt, made the following contributions: 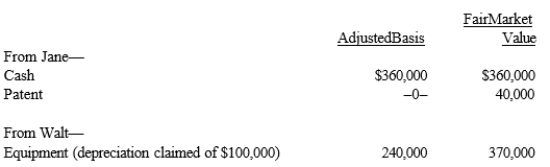 Both Jane and Walt receive stock in Chickadee Corporation equal to the value of their investments.
 (Multiple Choice)
4.7/5 (77)
(77) The control requirement under § 351 requires that the person or persons transferring property to the corporation immediately after the transfer own stock possessing at least 80% of the total combined voting power of all classes of stock entitled to vote and at least 80% of the total number of shares of all other classes of stock of the corporation.
(True/False)
4.9/5 (81)
(81) Because boot is generated under § 357(b) (i.e., the liability is not supported by a bona fide business purpose), the transferor shareholder will always have to recognize gain.
(True/False)
4.9/5 (78)
(78) Similar to the like-kind exchange provision, § 351 can be partly justified under the wherewithal to pay concept.
(True/False)
4.9/5 (86)
(86) When consideration is transferred to a corporation in return for stock, the definition of "property" is important because tax deferral treatment of § 351 is available only to taxpayers who transfer property.
(True/False)
4.9/5 (80)
(80) Alan, an Owl Corporation shareholder, makes a contribution to capital of equipment to Owl, basis of $40,000 and fair market value of $50,000. Owl's basis of the equipment that Alan contributes is equal to $50,000, the property's fair market value.
(True/False)
4.8/5 (76)
(76) In return for legal services worth $60,000 rendered incident to its formation, Crimson Corporation issues stock to Greta, an attorney. Crimson cannot immediately deduct the value of any of this stock but instead must capitalize it as an organizational expenditure.
(True/False)
4.8/5 (87)
(87) Ashley, a 70% shareholder of Wren Corporation, transfers property with a basis of $250,000 and a fair market value of $900,000 to Wren Corporation for additional stock. Ashley owns 78% of Wren after the transfer. Two other shareholders in Wren transfer a nominal amount of property to Wren along with Ashley's transfer so that Ashley and the two shareholders own 90% of the Wren stock after the transfer. Does Ashley have taxable gain on the transfer?
(Essay)
4.9/5 (68)
(68) Similar to like-kind exchanges, the receipt of "boot" under § 351 can cause loss to be recognized.
(True/False)
4.9/5 (83)
(83) Because services are not considered property under § 351, a taxpayer must report as income the fair market value of stock received for such services.
(True/False)
4.8/5 (93)
(93) Sarah and Tony (mother and son) form Dove Corporation with the following investments: cash by Sarah of $65,000; land by Tony (basis of $25,000 and fair market value of $35,000). Dove Corporation issues 400 shares of stock, 200 each to Sarah and Tony. Thus, each receives stock in Dove worth $50,000.
(Multiple Choice)
4.9/5 (82)
(82) When depreciable property is transferred to a controlled corporation under § 351, any recapture potential disappears and does not carry over to the corporation.
(True/False)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)