



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law208 Questions
Exam 2: Working With the Tax Law102 Questions
Exam 3: Computing the Tax166 Questions
Exam 4: Gross Income: Concepts and Inclusions122 Questions
Exam 5: Gross Income: Exclusions111 Questions
Exam 6: Deductions and Losses: in General148 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses116 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion113 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses126 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions103 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments103 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges250 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions156 Questions
Exam 15: Taxing Business Income65 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules137 Questions
Exam 18: Corporations: Organization and Capital Structure107 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation183 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations67 Questions
Exam 21: Partnerships231 Questions
Exam 22: S Corporations121 Questions
Exam 23: Exempt Entities129 Questions
Exam 24: Multistate Corporate Taxation184 Questions
Exam 25: Taxation of International Transactions128 Questions
Exam 26: Tax Practice and Ethics174 Questions
Exam 27: The Federal Gift and Estate Taxes145 Questions
Exam 28: Income Taxation of Trusts and Estates154 Questions
Select questions type


Kim Corporation, a calendar year taxpayer, has manufacturing facilities in States A and B. A summary of Kim's property holdings follows: 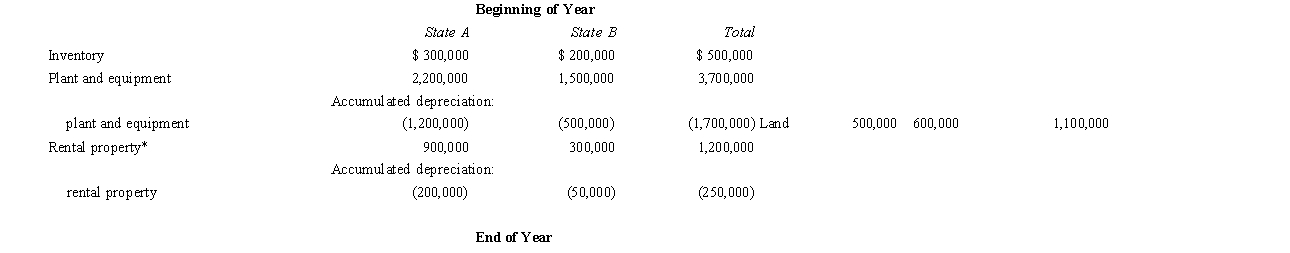 State A State B Total Inventory \ 400,000 \ 100,000 \ 500,000
Plant and equipment 2,500,000 1,200,000 3,700,000 Accumulated depreciation: plant and equipment (1,500,000) (450,000) (1,950,000) Land 600,000 400,000 1,000,000 Rental property* 900,000 300,000 1,200,000 Accumulated depreciation: rental property (300,000) (100,000) (400,000) *Unrelated to Kim's regular business and operations.
Determine Kim's property factors for the two states. State A's statutes provide that the average historical cost of business property is to be included in the property factor. State B's statutes provide that the property factor is based on the average depreciated basis of in-state business property.
State A State B Total Inventory \ 400,000 \ 100,000 \ 500,000
Plant and equipment 2,500,000 1,200,000 3,700,000 Accumulated depreciation: plant and equipment (1,500,000) (450,000) (1,950,000) Land 600,000 400,000 1,000,000 Rental property* 900,000 300,000 1,200,000 Accumulated depreciation: rental property (300,000) (100,000) (400,000) *Unrelated to Kim's regular business and operations.
Determine Kim's property factors for the two states. State A's statutes provide that the average historical cost of business property is to be included in the property factor. State B's statutes provide that the property factor is based on the average depreciated basis of in-state business property. (Essay)
4.8/5  (96)
(96) Given the following transactions for the year, determine Comp Corporation's D payroll factor denominator. State D has adopted the principles of UDITPA. Compensation of sales force \ 600,000 Compensation paid to independent contractors 300,000 Compensation paid to managers of nonbusiness rental property 100,000 Total compensation \ 1,000,000
(Multiple Choice)
4.9/5 (83)
(83) The property factor includes land and buildings used for business purposes.
(True/False)
4.7/5 (91)
(91) Typically, a sales/use tax is applied to a retail sale of property.
(Short Answer)
4.8/5 (81)
(81) Match each of the following items with the appropriate description in determining whether sales/use tax typically must be collected.
-Earthmoving equipment used by the purchaser in a construction business.
(Multiple Choice)
4.9/5 (74)
(74) The starting point in computing state taxable income generally is .
(Short Answer)
4.7/5 (83)
(83) In the income tax apportionment formula, market-sourcing the sales factor means that:
(Multiple Choice)
4.9/5 (78)
(78) Match each of the following items with the appropriate description in applying the P.L. 86-272 definition of solicitation.
-Checking the customer's inventory to determine whether a reorder is needed.
(Multiple Choice)
4.7/5 (62)
(62) Pail Corporation is a merchandiser. It purchases overstock garments from various suppliers and sells the goods in its
State L retail store. Sales to State L residents \ 600,000 Sales to homeless shelter operated by a local church 80,000 Sales to residents who cross the border from nearby State M 100,000 Sales to a similar merchandiser located in another State L town 20,000 Determine the total sales that are subject to the State L sales tax.
(Essay)
4.9/5 (72)
(72) Typically, the state's payroll factor (does/does not) include the salaries and bonuses paid to its corporate executives.
(Short Answer)
4.9/5 (78)
(78) Helene Corporation owns manufacturing facilities in States A, B, and C. State A uses a three-factor apportionment formula under which the sales, property, and payroll factors are equally weighted. State B uses a three-factor apportionment formula under which sales are double-weighted. State C employs a single-factor apportionment factor based solely on sales. Helene's operations generated $1,000,000 of apportionable income, and its sales and payroll activity and average property owned in each of the three states is as follows: State A State B State C Totals Sales \ 400,000 \ 800,000 \ 300,000 \ 1,500,000 Payroll 100,000 150,000 50,000 300,000 Property 200,000 200,000 200,000 600,000 Helene's apportionable income assigned to State A is:
(Multiple Choice)
4.8/5 (87)
(87) Drieser Corporation's manufacturing facility, distribution center, and retail store are located in State K. Drieser sells its products to residents located in States K, M, and N.
Sales to residents of K are conducted through a retail store. Sales to residents of M are obtained by Drieser's sales representative, who has the authority to solicit, accept, and approve sales orders in State M. Residents of N can purchase Drieser's product only if they place an order online and arrange to take delivery of the product at Drieser's shipping dock.
Drieser's sales this year were reported as follows: Sales to residents of State \ 1,000,000 Sales to residents of State 600,000 Sales to residents of State 900,000 Total \ 2,500,000 Drieser's activities within the three states are limited to those described above. All of the states have adopted a throwback provision and utilize a three-factor apportionment formula under which sales, property, and payroll are equally weighted. State K sources dock sales to the destination state.
Determine Drieser's sales factors for States K, M, and N.
(Essay)
5.0/5 (86)
(86) Roughly 5% of all taxes paid by businesses in the United States are to state, local, and municipal jurisdictions.
(True/False)
4.9/5 (78)
(78) Match each of the following events considered independently to its likely effect on WillCo's various apportionment factors. WillCo is based in Q and has customers in Q, R, and S. To this point, WillCo has not established nexus with S. More than one choice may be correct.
-WillCo completes the construction of production facilities in S.
(Multiple Choice)
4.9/5 (89)
(89) State Q has adopted sales-factor-only apportionment for its corporate income tax. As a result, a
(larger/smaller) percentage of an out-of-state corporation's income is assigned to tax in the state.
(Short Answer)
4.8/5 (81)
(81) Zhao Company sold an asset on the first day of the tax year for $500,000. Zhao's Federal tax basis for the asset was $300,000. Because of differences in cost recovery schedules, the state regular-tax basis in the asset was $350,000. What modification, if any, should be made to Zhao's Federal taxable income in determining the correct taxable income for the typical state?
(Multiple Choice)
4.9/5 (73)
(73) Usually a business chooses a location where it will build a new plant based chiefly on tax considerations.
(True/False)
5.0/5 (76)
(76) Under P.L. 86-272, which of the following transactions by itself would create nexus with a state?
(Multiple Choice)
4.8/5 (89)
(89) Match each of the following events considered independently to its likely effect on WillCo's various apportionment factors. WillCo is based in Q and has customers in Q, R, and S. To this point, WillCo has not established nexus with S. More than one choice may be correct.
-Q adopts a sales-only apportionment formula.
(Multiple Choice)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)