



 Chat with AI
Exam 18: Leases

Exam 12: Financial Liabilities and Provisions78 Questions
Exam 13: Financial Instruments: Long-Term Debt74 Questions
Exam 14: Shareholders Equity181 Questions
Exam 15: Financial Instruments: Complex Debt and Equity135 Questions
Exam 16: Corporate Income Tax122 Questions
Exam 17: Tax Losses98 Questions
Exam 18: Leases234 Questions
Exam 19: Post-Employment Benefits92 Questions
Exam 20: Earnings Per Share153 Questions
Exam 21: Accounting Changes157 Questions
Exam 22: Financial Statement Analysis165 Questions
Select questions type


One incentive for entering into sale-and-leaseback arrangements is:
(Multiple Choice)
4.7/5  (92)
(92) LAS owns a building in North Bay.LAS enters into an agreement with BH as follows: LAS sells the building to BH on 1/1/2014 for $1,900,000 (the building's fair value on that date was $1,800,000)and immediately leases it back for $500,000 per year for 10 years.The remaining life of the building is estimated at 20 years.The historical cost of the building was $9,000,000 and accumulated amortization amounted to $7,000,000.Assuming that ASPE applies, and that the lease does not qualify as a finance lease, the net effect of this transaction on the statement of comprehensive income in the year of sale would be:
(Multiple Choice)
4.7/5 (75)
(75) Contingent rent is one of three common methods used to avoid capitalization.
(True/False)
4.8/5 (86)
(86) At the inception of a finance lease which calls for payments on an annuity due basis, the lessee typically debits:
(Multiple Choice)
4.9/5 (80)
(80) LAS owns a building in North Bay.LAS enters into an agreement with BH as follows: LAS sells the building to BH on 1/1/2014 for $2,900,000 (which was the building's fair value on that date)and immediately leases it back for $500,000 per year for 10 years.The historical cost of the building was $9,000,000 and accumulated amortization amounted to $7,000,000.The net effect of this transaction on the statement of comprehensive income in the year of sale would be:
(Multiple Choice)
4.9/5 (76)
(76) A finance lease is accounted for "as if" it transfers a material interest in the leased asset from the lessor to the lessee.
(True/False)
4.8/5 (59)
(59) Under ASPE, when a sale leaseback qualifies as a capital lease, any gain or loss should always be amortized over the term over which depreciation is taken.
(True/False)
4.8/5 (75)
(75) On January 1, 2014, BE Company collected a $15,000 cash, non-refundable, bonus payment on an operating lease.Assuming a 12 percent interest rate and a five-year lease term, the lease bonus amortization journal entry for 2014, if the interest method is used, is:
(Multiple Choice)
4.8/5 (80)
(80) Under proposed changes to IFRS leasing standards, a lease that is less than 12 months in duration may be classified as long-term if there are substantial penalties for non-renewal.
(True/False)
4.9/5 (80)
(80) Under a finance lease that includes a bargain purchase option (BPO), how is depreciation on the asset under lease recognized by: 
(Multiple Choice)
4.9/5 (72)
(72) JMR Company leases an asset from KAR Company.The rate implicit in the lease is 12% and JMR's incremental borrowing rate is 11%.JMR is aware of the implicit rate.Assuming that both rates would provide an MLP amount well below the fair value of the leased asset, the rate that JMR should use for discounting the net lease payment is:
(Multiple Choice)
5.0/5 (71)
(71) One of the most common methods of avoiding the capitalization of a lease is to enter into lease agreements that provide year-by-year renewal.
(True/False)
4.8/5 (85)
(85) On December 31, 2015, JKL leased a new machine from MNO.The following information relates to the lease transaction: * Market value of the machine at inception of lease: $500,000
* the machine has an estimated useful life of seven years, which coincides with the lease term.
* lease rentals consist of seven equal annual payments of $100,000, the first of which was paid on December 31, 2015.
* MNO's implicit interest rate is 12 percent, which is known by JKL.
* JKL's incremental borrowing rate is 14 percent at December 31, 2015.
* present value of an annuity of $1 in advance for seven periods at 12 percent is 5.11.
* present value of an annuity of $1 in advance for seven periods at 14 percent is 4.89.
At the inception of the lease, JKL should record a capitalized lease liability of:
(Multiple Choice)
5.0/5 (76)
(76) Under ASPE, any initial loss arising from a sale leaseback arrangement must be recognized immediately..
(True/False)
4.8/5 (72)
(72) Both guaranteed and unguaranteed residual values should be included in the calculation of the lessee's minimum lease payments of the lessee.
(True/False)
4.9/5 (80)
(80) A lease which contains a bargain purchase option, but which has a term equal to only 70% of the estimated economic life of the leased property cannot properly be classified as a finance lease by a lessee.
(True/False)
5.0/5 (85)
(85) Lessor Company leases small computers on three-year leases at the end of which the residual value
is not material in amount.Rents are collected at year-end.On January 1, 2014, Lessor signed a 3-year lease with Lessee Company that called for annual rents of $12,063, which was a return to
Lessor of 10% on the $30,000 cost (market value at date of lease).Assume the lease qualifies as a direct financing lease to the lessor and a finance lease to the lessee.There was no bargain purchase option or residual value.The lessee's incremental borrowing rate is 12%.
(a)Complete the following amortization schedule for the lease.Round to the nearest dollar. 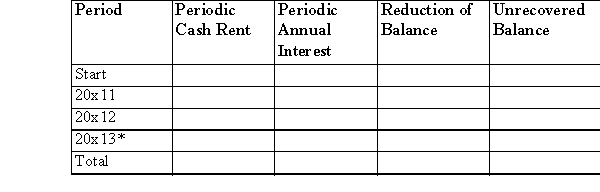 * May have slight rounding error.
(b)Can both the lessor and lessee use the amortization schedule values in this instance? Yes ________ No ________
Explain why _.
(c)Give the entries for the lessor and lessee on the following dates (assume the accounting period ends December 31).Use the abbreviated account titles.
January 1, 2014-Inception of the lease:
 December 31, 2014-Interest date and end of accounting period (give all entries except closing entries):
* May have slight rounding error.
(b)Can both the lessor and lessee use the amortization schedule values in this instance? Yes ________ No ________
Explain why _.
(c)Give the entries for the lessor and lessee on the following dates (assume the accounting period ends December 31).Use the abbreviated account titles.
January 1, 2014-Inception of the lease:
December 31, 2014-Interest date and end of accounting period (give all entries except closing entries): (Essay)
4.8/5 (77)
(77) ML leased a computer to LH on January 1, 2014.The lease was a five year fixed, non-cancellable agreement.The payments were finalized at $2,380 per year with the first payment on January 1, 2014 and ML paid $9,500 for the computer.Carrying value is equal to fair value.The lease is deemed a finance lease.Based on the above information, what type of lease is this for the lessor.Prepare the journal entries for at the inception of the lease using the gross method.
(Essay)
4.9/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)