



 Chat with AI
Exam 22: S Corporations

Exam 1: An Introduction to Tax110 Questions
Exam 2: Tax Compliance, the Irs, and Tax Authorities112 Questions
Exam 3: Tax Planning Strategies and Related Limitations107 Questions
Exam 4: Individual Income Tax Overview, Exemptions, and Filing Status126 Questions
Exam 5: Gross Income and Exclusions131 Questions
Exam 6: Individual Deductions107 Questions
Exam 7: Investments75 Questions
Exam 8: Individual Income Tax Computation and Tax Credits154 Questions
Exam 9: Business Income, Deductions, and Accounting Methods99 Questions
Exam 10: Property Acquisition and Cost Recovery94 Questions
Exam 11: Property Dispositions110 Questions
Exam 12: Compensation102 Questions
Exam 13: Retirement Savings and Deferred Compensation115 Questions
Exam 14: Tax Consequences of Home Ownership111 Questions
Exam 15: Entities Overview70 Questions
Exam 16: Corporate Operations140 Questions
Exam 17: Accounting for Income Taxes100 Questions
Exam 18: Corporate Taxation: Nonliquidating Distributions98 Questions
Exam 19: Corporate Formation, Reorganization, and Liquidation100 Questions
Exam 20: Forming and Operating Partnerships102 Questions
Exam 21: Dispositions of Partnership Interests and Partnership Distributions100 Questions
Exam 22: S Corporations134 Questions
Exam 23: State and Local Taxes117 Questions
Exam 24: The US Taxation of Multinational Transactions100 Questions
Exam 25: Transfer Taxes and Wealth Planning123 Questions
Select questions type


Hazel is the sole shareholder of Maple Corp. In 2017 Maple operated as a C corporation and reported $15,000 of taxable income (and earnings and profits). In 2017, Maple elected S corporation status. During 2018 Maple reported $12,000 of ordinary business income and no separately stateditems. It also distributed $25,000 to Hazel. What is the amount and character of income Hazel must recognize on the distribution? What is Hazel's stock basis at the end of 2018 (after accounting for the distribution) if her basis at the beginning of the year was $5,000?
(Essay)
4.8/5  (83)
(83) The IRS may consent to an early re-election of S corporation status after a termination under which of the following:
(Multiple Choice)
4.7/5 (90)
(90) Suppose SPA Corp. was formed by Sara Inc. (a C corporation that is 100% owned by Sara) andSara's friend Tyson. In exchange for 50% of the stock of SPA, Sara contributed $100,000. Inexchange for the remaining 50% of the SPA stock, Tyson contributed a building with a fair market value of $100,000 and an adjusted tax basis of $60,000. How much gain is Tyson required torecognize on the contribution? Is SPA eligible to elect S corporation status?
(Essay)
4.7/5 (92)
(92) Separately stated items are tax items that are treated similarly for tax purposes as a shareholder's share of ordinary business income (loss).
(True/False)
4.8/5 (84)
(84) S corporations without earnings and profits from prior C corporation years are not subject to the excess net passive income tax.
(True/False)
4.9/5 (84)
(84) Suppose at the beginning of 2017, Jamaal's basis in his S corporation stock is $0, he hasa $0 debt basis associated with a $10,000 loan he made to the S corporation and a $5,000 suspended loss from the S corporation. In 2017, Jamaal contributed $8,000 to the Scorporation, and the S corporation had ordinary income of $4,000. Assume that Jamaalowns 40% of the S corporation. What is Jamaal's stock and debt basis at the end of2017?
(Multiple Choice)
4.8/5 (80)
(80) Clampett, Inc. converted to an S corporation on January 1, 2017. At that time, Clampett, Inc. had cash ($40,000), inventory (FMV $60,000, Basis $30,000), accounts receivable (FMV $40,000, Basis $40,000), and equipment (FMV $60,000, Basis $80,000). In 2018, Clampett, Inc. sells its entire inventory for $60,000 (Basis $30,000). Assuming thecorporate tax rate is 35%. Clampett, Inc.'s taxable income in 2018 would have been$1,000,000 if it had been a C corporation. How much built-in gains tax does Clampett, Inc. pay in 2018?
(Multiple Choice)
4.9/5 (69)
(69) XYZ Corporation (an S corporation) is owned by Jane and Rebecca who are each 50% shareholders. At the beginning of the year, Jane's basis in her XYZ stock was $40,000. XYZ reported the following tax information for 2017. 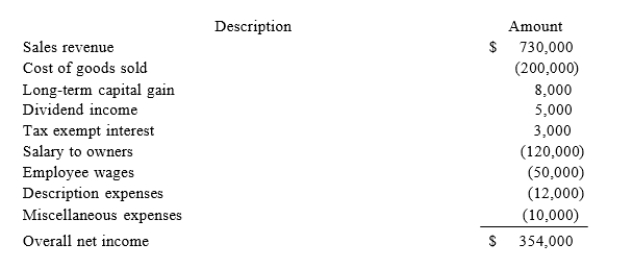 Required:a. What amount of ordinary business income is allocated to Jane?b. What is the amount and character of separately stated items allocated to Jane?c. What is Jane's basis in her XYZ corp. stock at the end of the year?
 (Essay)
4.8/5 (85)
(85) Jackson is the sole owner of JJJ corp. (an S corporation). At the end of 2017, Jackson's basis in his JJJ stock and his at risk amount was $0. Jackson also had a $10,000 suspended ordinary business loss (suspended at the tax basis and at risk level). JJJ's S election was terminated effective the end of the day on December 31, 2017. If Jackson contributes $6,000 cash to JJJ on July 1, 2018 and $3,000 cash on January 5, 2019, how much of his $10,000 suspended loss will he be allowed to deduct and how much disappears unused?
(Essay)
4.9/5 (80)
(80) Which of the following would not result in an S election termination?
(Multiple Choice)
5.0/5 (79)
(79) If an S corporation shareholder sells her stock to a nonresident alien, it will automatically terminate the S election.
(True/False)
4.8/5 (76)
(76) At the beginning of the year, Clampett, Inc. had $100,000 in its AAA, $60,000 of earnings and profits from prior C corporation years. During the year, Clampett, Inc.earned $50,000 of ordinary income and paid $200,000 in distributions to its shareholders. Assume that J. D. owns 25% of Clampett, Inc., his basis in Clampett, Inc. at thebeginning of the year is $30,000, and his share of the distribution was $50,000. How much, if any, of the distribution is taxable as a dividend?
(Multiple Choice)
4.8/5 (73)
(73) Unlike partnerships, adjustments that decrease an S corporation shareholder's basis may reduce it below zero.
(True/False)
4.8/5 (66)
(66) Lamont is a 100% owner of JKL Corporation. JKL has been an S corporation since its inception in2017. During 2018, JKL distributed $20,000 to Lamont. During 2018, JKL reported $5,000 ofbusiness income and no separately stated items. What is the amount and character of the gain on the distribution, if any, Lamont must recognize in each of the following alternative scenarios? Also, what isLamont's stock basis at the end of 2018 in each of the following scenarios?a. Lamont's stock basis at the beginning of 2018 was $30,000. b. Lamont's stock basis at the beginning of 2018 was $4,000.
(Essay)
4.9/5 (85)
(85) In general, an S corporation shareholder makes increasing adjustments to her basis first, followed by adjustments that decrease basis.
(True/False)
4.9/5 (83)
(83) SEC Corporation has been operating as a C corporation since 2014. It elected to become an Scorporation, effective January 1, 2017. On December 31, 2016, SEC reported a net unrealized built in gain of $60,000. In addition to other transactions in 2017, SEC sold inventory it owned at the beginning of 2017 (it did not sell any other assets it owned at the beginning of 2017). At the beginning of the year, the inventory it sold had a fair market value of $30,000 and a FIFO tax basis of $10,000. SEC sold the inventory for $35,000. If SEC had been a C corporation in 2017, itstaxable income would have been $100,000. How much built-in gains tax must SEC pay in 2017?
(Essay)
4.9/5 (75)
(75) RGD Corporation was a C corporation from its inception in 2013 through 2016. However, it elected Scorporation status effective January 1, 2017. RGD had $50,000 of earnings and profits at the end of 2016. RGDreported the following information for its 2017 tax year.  What amount of excess net passive income tax is RGD liable for in 2017? (Round your answer for excess net passive income to the nearest thousand).
 (Essay)
4.8/5 (89)
(89) Clampett, Inc. converted to an S corporation on January 1, 2017. At that time, Clampett, Inc. had cash ($40,000), inventory (FMV $60,000, Basis $30,000), accounts receivable (FMV $40,000, Basis $40,000), and equipment (FMV $60,000, Basis $80,000). What is Clampett, Inc.'s built-in gain or loss on January 1, 2017?
(Multiple Choice)
4.9/5 (75)
(75) Jackson is the sole owner of JJJ corp. (an S corporation). At the beginning of 2017, Jackson's basis in his JJJ stock was $8,000. For 2017, JJJ reported a ($30,000) ordinary business loss (not a passive loss) and $4,000 of long-term capital gains. Assuming Jackson's tax basis and his at risk amount are the same, what is Jackson's stock basis at the end of the year and how much of the ordinary business loss is he allowed to deduct in 2017?
(Essay)
4.9/5 (78)
(78) For an S corporation shareholder to deduct it, a loss must clear three separatetax-provision hurdles: (1) tax basis, (2) at-risk amount, and (3) tax-shelter rules.
(True/False)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)