



 Chat with AI
Exam 25: Transfer Taxes and Wealth Planning

Exam 1: An Introduction to Tax110 Questions
Exam 2: Tax Compliance, the Irs, and Tax Authorities112 Questions
Exam 3: Tax Planning Strategies and Related Limitations107 Questions
Exam 4: Individual Income Tax Overview, Exemptions, and Filing Status126 Questions
Exam 5: Gross Income and Exclusions131 Questions
Exam 6: Individual Deductions107 Questions
Exam 7: Investments75 Questions
Exam 8: Individual Income Tax Computation and Tax Credits154 Questions
Exam 9: Business Income, Deductions, and Accounting Methods99 Questions
Exam 10: Property Acquisition and Cost Recovery94 Questions
Exam 11: Property Dispositions110 Questions
Exam 12: Compensation102 Questions
Exam 13: Retirement Savings and Deferred Compensation115 Questions
Exam 14: Tax Consequences of Home Ownership111 Questions
Exam 15: Entities Overview70 Questions
Exam 16: Corporate Operations140 Questions
Exam 17: Accounting for Income Taxes100 Questions
Exam 18: Corporate Taxation: Nonliquidating Distributions98 Questions
Exam 19: Corporate Formation, Reorganization, and Liquidation100 Questions
Exam 20: Forming and Operating Partnerships102 Questions
Exam 21: Dispositions of Partnership Interests and Partnership Distributions100 Questions
Exam 22: S Corporations134 Questions
Exam 23: State and Local Taxes117 Questions
Exam 24: The US Taxation of Multinational Transactions100 Questions
Exam 25: Transfer Taxes and Wealth Planning123 Questions
Select questions type


Caleb transferred $115,000 to an irrevocable trust for Avery. The trustee has the discretion to distribute income or corpus for Avery's benefit but is required to distribute all assets to Avery (or his estate) not later than Avery's 21st birthday. What is the amount, if any, of the taxable gift?
(Essay)
4.9/5  (93)
(93) Property inherited from a decedent has an adjusted basis equal to the value of the property included in the decedent's estate.
(True/False)
4.9/5 (79)
(79) The testamentary transfer of property to a qualified charity is deductible in calculating the taxable estate without any ceiling limitation.
(True/False)
4.9/5 (64)
(64) The gross estate always includes the value of half of any real property owned by a decedent and another person in joint tenancy with the right of survivorship.
(True/False)
4.8/5 (84)
(84) Ashley owns a whole-life insurance policy worth $25,000 that directs the insurance company to pay the beneficiary $500,000 on her death. Ashley pays the annual policy premiums and has the power to designate the beneficiary of the policy. What value of the policy, if any, would be included in Ashley's estate upon her death?
(Essay)
4.7/5 (72)
(72) The amount of the estate tax is directly related to the amount of taxable gifts.
(True/False)
4.9/5 (83)
(83) Harold and Mary are married and live in a community property state. During the marriage Harold bought a parcel of real estate for $100,000 in community funds and titled the property in his name alone. Mary died on January 30th of this year and wassurvived by Harold who did not remarry. The parcel of real property was worth $250,000 on January 30th of this year but was only worth $220,000 at year end. What amount, if any, is included in Mary's gross estate?
(Multiple Choice)
4.8/5 (91)
(91) The debts of the decedent at the time of death are deducted in calculating the taxable estate.
(True/False)
4.7/5 (73)
(73) Eric has $5 million of property that he wants to leave to his four children. He is considering making a current gift of the property (rather than leaving the property to pass through his will). Eric has made many prior taxable gifts and additional taxable transfers will be subject to the highest transfer tax rate. Determine how much estate tax Eric will save if he gifts the property now and survives at least three years, during which time the property appreciates to $5.5 million? Ignore the time value of money in your calculation. (Use Exhibit 25-1) 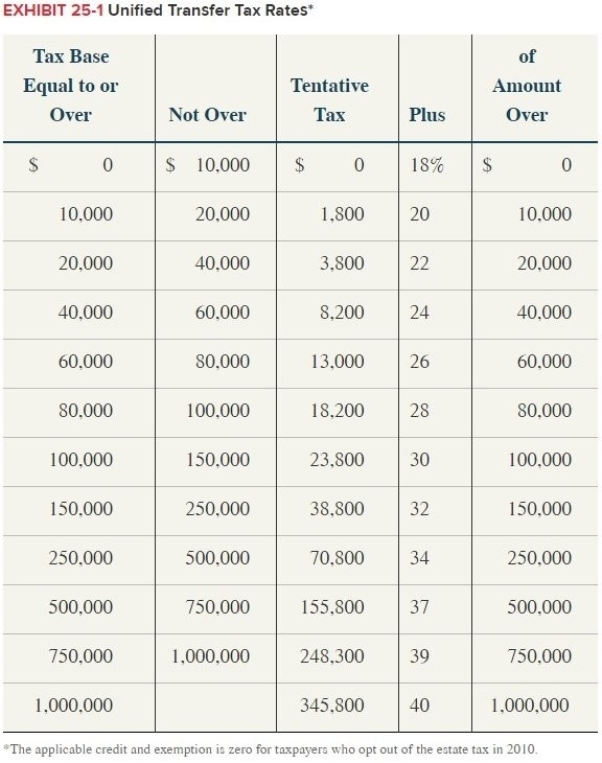
(Essay)
4.8/5 (70)
(70) For 2017, the exemption equivalent for the estate tax is $5.49 million.
(True/False)
4.9/5 (70)
(70) A withdrawal of money from a bank account held in joint tenancy with the right of survivorship may constitute a completed gift.
(True/False)
5.0/5 (65)
(65) A trust is a legal entity whose purpose is to hold and administer property for the benefit of beneficiaries.
(True/False)
4.8/5 (85)
(85) A serial gift strategy uses multiple gifts to maximize the value of the annual exclusion.
(True/False)
4.9/5 (79)
(79) When creating an estate tax planning strategy, the income tax benefit derived from astep-up in tax basis on assets should be measured against the estate tax cost of including the assets in the decedent's gross estate.
(True/False)
4.8/5 (76)
(76) An exemption equivalent is the amount of annual gifts that is automatically exempt fromthe gift tax.
(True/False)
4.8/5 (81)
(81) A applicable credit is subtracted in calculating both the gift tax and the estate tax. Why doesn't this calculation have the effect of increasing the total applicable credit amount?
(Multiple Choice)
4.9/5 (78)
(78) Ricardo transferred $1,000,000 of cash to State University for a new sports complex. Calculate the amount of the taxable gift.
(Essay)
4.8/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)