



 Chat with AI
Exam 12: General Equilibrium and the Efficiency of Perfect Competition

Exam 1: The Scope and Method of Economics68 Questions
Exam 2: The Economic Problem: Scarcity and Choice50 Questions
Exam 3: Demand, Supply, and Market Equilibrium52 Questions
Exam 4: Demand and Supply Applications41 Questions
Exam 5: Elasticity74 Questions
Exam 6: Household Behavior and Consumer Choice50 Questions
Exam 7: The Production Process: the Behavior of Profit-Maximizing Firms64 Questions
Exam 8: Short-Run Costs and Output Decisions59 Questions
Exam 9: Long-Run Costs and Output Decisions87 Questions
Exam 10: Input Demand: the Labor and Land Markets77 Questions
Exam 11: Input Demand: the Capital Market and the Investment Decision66 Questions
Exam 12: General Equilibrium and the Efficiency of Perfect Competition44 Questions
Exam 13: Monopoly and Antitrust Policy45 Questions
Exam 14: Oligopoly53 Questions
Exam 15: Monopolistic Competition31 Questions
Exam 16: Externalities, Public Goods, and Social Choice54 Questions
Select questions type


Why does the model of perfect competition imply that firms will produce the products that households want the most?
(Essay)
4.9/5  (78)
(78) Use the three basic questions to describe why perfect competition is efficient.
(Essay)
4.7/5 (82)
(82) Why does the model of perfect competition imply that there will be an efficient allocation of resources among firms?
(Essay)
5.0/5 (84)
(84) What assumptions lead to the conclusion that final products are distributed efficiently among households?
(Essay)
4.9/5 (70)
(70) What does it mean for an industry to be considered an increasing cost industry?
(Essay)
4.9/5 (79)
(79) Create an example of a trade that is not Pareto efficient. Make sure that you explain why such a trade is not Pareto efficient.
(Essay)
4.7/5 (80)
(80) The text asserts that the allocation of resources among firms is efficient. What assumptions must hold for this to be true?
(Essay)
4.9/5 (80)
(80) Create an example of a Pareto efficient trade. Make sure that you explain why such a trade is Pareto efficient.
(Essay)
4.8/5 (70)
(70) How is a potentially efficient change different from a Pareto optimal change?
(Essay)
4.9/5 (89)
(89) Use Figure 12.1 to answer the following question. Assume that this industry is currently enjoying normal economic profit and for whatever reason there is an increase in demand for the goods produced by this industry. Using general equilibrium analysis explain what will happen both in this industry and in industry Y which is perceived by consumers as being a product that is a substitute for product X. 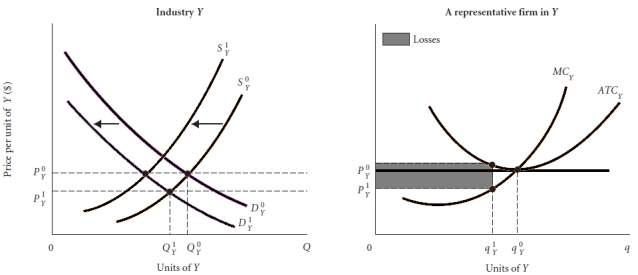
(Essay)
4.8/5 (70)
(70) Comment on the following statement: "Input and output markets should be considered separately because they operate independently of one another."
(Essay)
4.8/5 (96)
(96) In the early years of software development the industry had to train its own workers in developing code to build software applications. It was a very costly undertaking as software firms had to shoulder most of the training costs. However, over time the industry began to experience decreasing costs. How and why did this transformation take place?
(Essay)
4.8/5 (92)
(92) Why does an efficient distribution of outputs among households occur in perfectly competitive markets?
(Essay)
4.8/5 (71)
(71) When parents inoculate their children from communicable diseases prior to sending them off to school they not only provide their own children a benefit but also bestow a benefit on every other student at the school. There are now fewer students who can pass on these types of diseases. However, parents are not likely to take into account the fact that their actions create this external benefit. Therefore, economists argue that the market on its own may not provide for the optimal level of inoculations. What methods might work to get parents to take into account the external benefit when deciding whether to inoculate their children?
(Essay)
4.9/5 (77)
(77) If the economy were truly made of industries that fit the textbook definition of perfect competition what do you expect would be a major disadvantage of this from the consumer's perspective?
(Essay)
4.7/5 (57)
(57) Why is it difficult to determine whether an industry is operating efficiently when there is rapid technological process underway?
(Essay)
4.9/5 (81)
(81) Do the assumptions of the perfectly competitive model describe all real-world markets? Explain.
(Essay)
4.8/5 (88)
(88) What three assumptions must hold for the allocation of resources among firms to be efficient?
(Essay)
4.9/5 (79)
(79) Assume that the economy has two sectors, milk and orange juice, and that both sectors are initially in long-run competitive equilibrium. Milk and orange juice are substitute goods. Trace the effects of a change in preferences that increases the demand for orange juice.
(Essay)
4.8/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)