



 Chat with AI
Exam 7: Production Costs

Exam 1: Introducing the Economic Way of Thinking251 Questions
Exam 2: Production Possibilities, Opportunity Cost, and Economic Growth202 Questions
Exam 3: Market Demand and Supply412 Questions
Exam 4: Markets in Action253 Questions
Exam 5: Price Elasticity of Demand and Supply280 Questions
Exam 6: Consumer Choice Theory272 Questions
Exam 7: Production Costs243 Questions
Exam 8: Perfect Competition237 Questions
Exam 9: Monopoly168 Questions
Exam 10: Monopolistic Competition and Oligopoly187 Questions
Exam 11: Labor Markets202 Questions
Exam 12: Income Distribution, Poverty, and Discrimination130 Questions
Exam 13: Antitrust and Regulation203 Questions
Exam 14: Environmental Economics106 Questions
Exam 15: International Trade and Finance241 Questions
Exam 16: Economies in Transition108 Questions
Exam 17: Growth and the117 Questions
Select questions type


Exhibit 7-6 Total cost curves 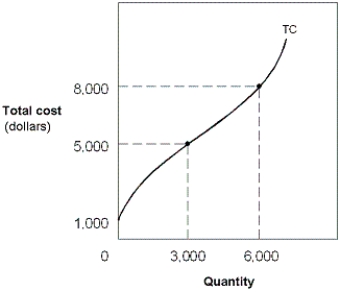 -In Exhibit 7-6, the total cost of producing 6,000 units of output is:
 (Multiple Choice)
4.8/5  (81)
(81) Exhibit 7-13 Cost curves 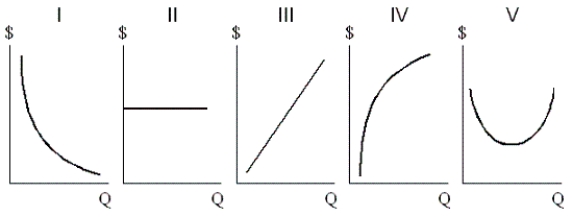 -In Exhibit 7-13, ATC is shown by the graph labeled:
 (Multiple Choice)
4.9/5 (78)
(78) If total cost is $1,000 when output is zero, and total cost is $1,200 when output is one, and total cost is $1,500 when output is two, then which of the following is true?
(Multiple Choice)
4.8/5 (80)
(80) Constant returns to scale exist over the range of output for which the long-run average cost is:
(Multiple Choice)
4.9/5 (85)
(85) Which of the following is true if the total variable cost curve is rising?
(Multiple Choice)
4.7/5 (82)
(82) A firm's marginal product curve slopes downward throughout its length.
(True/False)
4.8/5 (90)
(90) Which of the following will become smaller and smaller as the firm expands output?
(Multiple Choice)
4.9/5 (66)
(66) Which of the following is true at the point where diminishing returns set in?
(Multiple Choice)
4.8/5 (76)
(76) Each potential short-run average total cost curve is tangent to the long-run average cost curve at:
(Multiple Choice)
4.7/5 (72)
(72) Suppose that when output is 20, marginal cost is $20, and average total cost is $30. Then which of the following is most likely to be true?
(Multiple Choice)
4.7/5 (80)
(80) What is the difference between economic and accounting profit? Why is a distinction between them important?
(Essay)
4.9/5 (71)
(71) Which of the following are implicit costs for a typical firm?
(Multiple Choice)
4.9/5 (70)
(70) A downward-sloping portion of a long-run average total cost curve is the result of:
(Multiple Choice)
4.8/5 (82)
(82) Exhibit 7-7 Cost schedule for a firm Quantity Total Cost Marginal Cost 0 \ 200 1 900 2 \ 900 3 3,000
-In Exhibit 7-7, by filling in the blanks it can be determined that the fixed costs are:
(Multiple Choice)
5.0/5 (72)
(72) Which of the following is an example of a fixed cost for a fishing company?
(Multiple Choice)
4.8/5 (76)
(76) All of a firm's inputs are considered to be variable in the long run.
(True/False)
4.9/5 (72)
(72) Exhibit 7-17 Long-run average cost curve 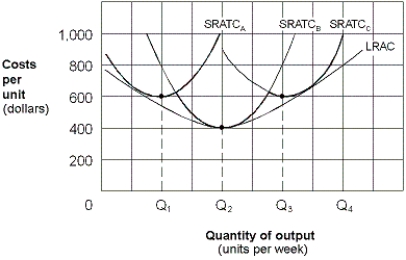 -If the firm represented in Exhibit 7-17 is operating with a plant whose size corresponds to short-run average total cost curve A, the level of output that would minimize its short-run average total cost is:
 (Multiple Choice)
4.8/5 (67)
(67) Which of the following is most likely to be true of economic and accounting profits?
(Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)