



 Chat with AI
Exam 7: Production Costs

Exam 1: Introducing the Economic Way of Thinking251 Questions
Exam 2: Production Possibilities, Opportunity Cost, and Economic Growth202 Questions
Exam 3: Market Demand and Supply412 Questions
Exam 4: Markets in Action253 Questions
Exam 5: Price Elasticity of Demand and Supply280 Questions
Exam 6: Consumer Choice Theory272 Questions
Exam 7: Production Costs243 Questions
Exam 8: Perfect Competition237 Questions
Exam 9: Monopoly168 Questions
Exam 10: Monopolistic Competition and Oligopoly187 Questions
Exam 11: Labor Markets202 Questions
Exam 12: Income Distribution, Poverty, and Discrimination130 Questions
Exam 13: Antitrust and Regulation203 Questions
Exam 14: Environmental Economics106 Questions
Exam 15: International Trade and Finance241 Questions
Exam 16: Economies in Transition108 Questions
Exam 17: Growth and the117 Questions
Select questions type


Exhibit 7-11 Short-run cost curves schedule for pizzeria's hourly production Total Product Total Variable Cost Total Cost 0 pizzas \ 0 \ 20 10 50 70 20 80 100 30 130 150 40 230 250
-In Exhibit 7-11, the pizzeria's fixed cost is equal to:
(Multiple Choice)
4.9/5  (80)
(80) A farm is able to produce 5,000 bushels of peaches per season on 100 acres. Assume it adds one more acre and is able to produce 6,000 bushels per season. The marginal product of the additional acre of land for this farm is:
(Multiple Choice)
4.8/5 (86)
(86) If a firm enlarges its factory size and realizes higher average (per unit) costs of production then:
(Multiple Choice)
4.9/5 (80)
(80) Paul's Plumbing is a small business that employs 12 people. Which of the following is most likely to be a fixed cost for Paul's Plumbing?
(Multiple Choice)
4.9/5 (89)
(89) A firm can produce 450 gallons of milk per day with 4 workers and 500 gallons per day with 5 workers. The marginal product of the fifth worker expressed in gallons per worker per day, is:
(Multiple Choice)
4.8/5 (86)
(86) Exhibit 7-14 Cost curves 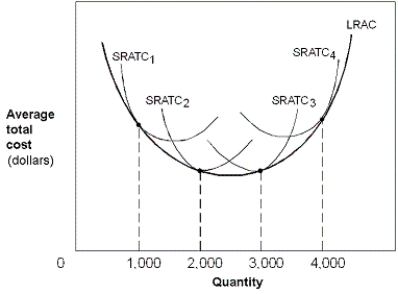 -In Exhibit 7-14, a firm finds that it is experiencing numerous managerial and information problems. The position of its short- and long-run average total cost curves suggest that it is operating at a production level:
 (Multiple Choice)
4.9/5 (77)
(77) If a firm increases output and its average total cost rises, then the firm is experiencing economies of scale.
(True/False)
4.8/5 (88)
(88) Exhibit 7-12 Cost schedule for producing pizza Pizzas Fixed Cost Variable Cost Total Cost 0 \ \ \ 1 48 2 17 3 27 4 78 5 40 6 64 7 80
-By filling in the blanks in Exhibit 7-12, the ATC of 4 pizzas is shown to be equal to:
(Multiple Choice)
4.8/5 (65)
(65) Cash payments to a steel mill for steel used in production would be an example of:
(Multiple Choice)
4.8/5 (81)
(81) An economist left his $100,000-a-year teaching position to work full-time in his own consulting business. In the first year, he had total revenue of $200,000 and business expenses of $150,000. He made a(n):
(Multiple Choice)
4.8/5 (84)
(84) Which of the following represents the key difference between the short run and the long run?
(Multiple Choice)
4.8/5 (94)
(94) Which of the following factors of production is not variable in the long run?
(Multiple Choice)
4.8/5 (67)
(67) When a total output curve is falling, its corresponding marginal product curve is:
(Multiple Choice)
4.8/5 (66)
(66) A firm has $200 million in total revenue and explicit costs of $190 million. Suppose its owners have invested $100 million in the company at an opportunity cost of 10 percent interest rate per year. The firm's economic profit is:
(Multiple Choice)
4.9/5 (92)
(92) Which of the following is an implication of the law of diminishing returns?
(Multiple Choice)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)