



 Chat with AI
Exam 9: Monopoly

Exam 1: Introducing the Economic Way of Thinking251 Questions
Exam 2: Production Possibilities, Opportunity Cost, and Economic Growth202 Questions
Exam 3: Market Demand and Supply412 Questions
Exam 4: Markets in Action253 Questions
Exam 5: Price Elasticity of Demand and Supply280 Questions
Exam 6: Consumer Choice Theory272 Questions
Exam 7: Production Costs243 Questions
Exam 8: Perfect Competition237 Questions
Exam 9: Monopoly168 Questions
Exam 10: Monopolistic Competition and Oligopoly187 Questions
Exam 11: Labor Markets202 Questions
Exam 12: Income Distribution, Poverty, and Discrimination130 Questions
Exam 13: Antitrust and Regulation203 Questions
Exam 14: Environmental Economics106 Questions
Exam 15: International Trade and Finance241 Questions
Exam 16: Economies in Transition108 Questions
Exam 17: Growth and the117 Questions
Select questions type


Which barrier to entry results in the creation of a natural monopoly?
(Multiple Choice)
4.8/5  (98)
(98) Which of the following factors is not a barrier limiting the entry of potential competitors into a market?
(Multiple Choice)
4.8/5 (84)
(84) To maximize its profits, a monopoly should produce the quantity where its marginal cost equals its:
(Multiple Choice)
4.8/5 (79)
(79) Exhibit 9-6 Monopoly
 -When the monopolist is maximizing total profit in Exhibit 9-6, the average total cost of producing that output level is:
 (Multiple Choice)
4.8/5 (80)
(80) A natural monopoly maximizes profits at the point at which price equals minimum average total cost.
(True/False)
4.9/5 (88)
(88) There is only one gas station within hundreds of miles. The owner finds that when she charges $3 a gallon, she sells 199 gallons a day, and when she charges $2.99 a gallon, she sells 200 gallons a day. The marginal revenue of the 200th gallon of gas is:
(Multiple Choice)
4.8/5 (77)
(77) Because monopolists are protected by high barriers to entry, they:
(Multiple Choice)
5.0/5 (78)
(78) In a natural monopoly, the long-run average cost curve declines and therefore average cost is lower when there is only one seller.
(True/False)
4.9/5 (76)
(76) Exhibit 9-3 Demand and cost curves for GeneTech, a monopolist with a patented vaccine
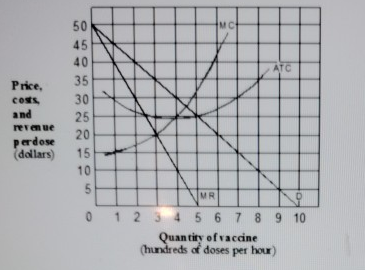 -As shown in Exhibit 9-3, in order to maximize its profit, what price should GeneTech charge for its vaccine?
 (Multiple Choice)
5.0/5 (86)
(86) In contrast to a perfectly competitive firm, a monopolist earns:
(Multiple Choice)
4.8/5 (88)
(88) An industry in which total costs are kept to a minimum because only one firm serves the whole market is called a:
(Multiple Choice)
4.8/5 (75)
(75) What is the name of the monopolist having a declining long-run average cost throughout the market?
(Multiple Choice)
4.7/5 (59)
(59) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)