



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics?198 Questions
Exam 2: The Economic Problem143 Questions
Exam 3: Demand and Supply178 Questions
Exam 4: Elasticity168 Questions
Exam 5: Efficiency and Equity108 Questions
Exam 6: Government Actions in Markets119 Questions
Exam 7: Global Markets in Action129 Questions
Exam 8: Utility and Demand110 Questions
Exam 9: Possibilities, Preferences, and Choices113 Questions
Exam 10: Organizing Production104 Questions
Exam 11: Output and Costs133 Questions
Exam 12: Perfect Competition118 Questions
Exam 13: Monopoly107 Questions
Exam 14: Monopolistic Competition111 Questions
Exam 15: Oligopoly97 Questions
Exam 16: Externalities112 Questions
Exam 17: Public Goods and Common Resources89 Questions
Exam 18: Markets for Factors of Production119 Questions
Exam 19: Economic Inequality117 Questions
Exam 20: Measuring GDP and Economic Growth127 Questions
Exam 21: Monitoring Jobs and Inflation112 Questions
Exam 22: Economic Growth90 Questions
Exam 23: Finance, Saving, and Investment142 Questions
Exam 24: Money, the Price Level, and Inflation115 Questions
Exam 25: The Exchange Rate and the Balance of Payments114 Questions
Exam 26: Aggregate Supply and Aggregate Demand124 Questions
Exam 27: Expenditure Multipliers: The Keynesian Model158 Questions
Exam 28: Canadian Inflation, Unemployment, and Business Cycle101 Questions
Exam 29: Fiscal Policy91 Questions
Exam 30: Monetary Policy88 Questions
Exam 31:International Trade Policy116 Questions
Select questions type


Use the figure below to answer the following questions.
 Figure 12.4.3
-Refer to Figure 12.4.3.which shows the cost curves and marginal revenue curve of a firm in a perfectly competitive market.In the long run,market
Figure 12.4.3
-Refer to Figure 12.4.3.which shows the cost curves and marginal revenue curve of a firm in a perfectly competitive market.In the long run,market (Multiple Choice)
4.9/5  (78)
(78) If a market experiences external diseconomies,the long-run market supply
(Multiple Choice)
4.8/5 (79)
(79) If a market experiences external economies,the long-run market supply
(Multiple Choice)
4.9/5 (84)
(84) When a perfectly competitive market is in long-run equilibrium
(Multiple Choice)
4.8/5 (81)
(81) Technological change spreads through a perfectly competitive market.Choose the statement that is incorrect.
(Multiple Choice)
4.9/5 (85)
(85) A perfectly competitive market is in short-run equilibrium with price below average total cost.Which one of the following is not a prediction of the long-run consequences of such a situation?
(Multiple Choice)
4.9/5 (81)
(81) Use the table below to answer the following questions.
Table 12.2.3
 -Refer to Table 12.2.3 which gives the total cost schedule for Brenda's Balloon Shop,a perfectly competitive firm.The average variable cost of producing the 1st balloon is
 (Multiple Choice)
4.8/5 (71)
(71) Use the information below to answer the following questions.
Fact 12.4.1
Franklin is a fiddlehead farmer.He sold 10 bags of fiddleheads last month, with total fixed cost of $100 and total variable cost of $50.
-Refer to Fact 12.4.1.Suppose the price of fiddleheads is expected to stay at $10 per bag for the foreseeable future,and Franklin's production and cost figures are expected to stay the same.His total fixed cost consists entirely of rent on land,and his five-year lease on the land runs out at the end of the month.Should Franklin renew the lease?
(Multiple Choice)
4.8/5 (83)
(83) Homer's Holesome Donuts has determined that its profit-maximizing quantity is 10,000 donuts per year.Homer's total revenue from the sale of donuts is $12,000 a year.Homer's costs are $16,000 in annual rental payments for its five-year lease on its store and $5,000 for ingredients.Should Homer's exit the market in the long run?
(Multiple Choice)
4.8/5 (92)
(92) Use the table below to answer the following questions.
Table 12.2.1
 -Refer to Table 12.2.1,which gives the total revenue schedule and total cost schedule of a perfectly competitive firm.If the firm produces 2 units of output,it
 (Multiple Choice)
4.9/5 (73)
(73) Use the table below to answer the following questions.
Table 12.2.3
-Refer to Table 12.2.3,which gives the total cost schedule for Brenda's Balloon Shop,a perfectly competitive firm.Brenda's total fixed cost is
-Refer to Table 12.2.3,which gives the total cost schedule for Brenda's Balloon Shop,a perfectly competitive firm.Brenda's total fixed cost is (Multiple Choice)
4.8/5 (92)
(92) Perfect competition occurs in a market where there are many firms,each selling
(Multiple Choice)
4.9/5 (79)
(79) Use the figure below to answer the following questions.
 Figure 12.2.2
-Refer to Figure 12.2.2,which shows a perfectly competitive firm's economic profit and loss.The firm is incurring a loss at
Figure 12.2.2
-Refer to Figure 12.2.2,which shows a perfectly competitive firm's economic profit and loss.The firm is incurring a loss at (Multiple Choice)
4.8/5 (71)
(71) Use the table below to answer the following question.
Table 12.4.1
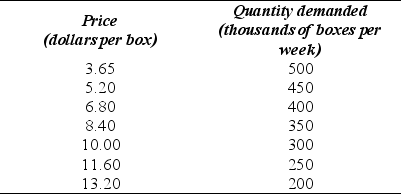
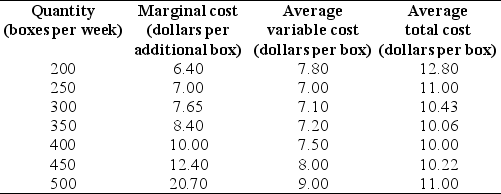 -Refer to Table 12.4.1.The top table shows the market demand schedule for paper.
The market is perfectly competitive and there are 1,000 firms that produce paper.Each firm has the costs shown in the bottom table when it uses its least-cost plant.
The market price in the long run is ________ a box and the equilibrium quantity produced in the long run is ________ boxes a week.
-Refer to Table 12.4.1.The top table shows the market demand schedule for paper.
The market is perfectly competitive and there are 1,000 firms that produce paper.Each firm has the costs shown in the bottom table when it uses its least-cost plant.
The market price in the long run is ________ a box and the equilibrium quantity produced in the long run is ________ boxes a week. (Multiple Choice)
4.8/5 (62)
(62) In a perfectly competitive market,the market demand curve is illustrated by
(Multiple Choice)
4.8/5 (81)
(81) Producers choose ________.
Producers are efficient on the market supply curve because ________.
(Multiple Choice)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)