



 Chat with AI
Exam 13: Equity Financing

Exam 1: Financial Reporting86 Questions
Exam 2: A Review of the Accounting Cycle94 Questions
Exam 3: The Balance Sheet and Notes to the Financial Statements72 Questions
Exam 4: The Income Statement82 Questions
Exam 5: Statement of Cash Flows and Articulation79 Questions
Exam 6: Earnings Management46 Questions
Exam 7: The Revenuereceivablescash Cycle81 Questions
Exam 8: Revenue Recognition74 Questions
Exam 9: Inventory and Cost of Goods Sold121 Questions
Exam 10: Investments in Noncurrent Operating Assets-Acquisition88 Questions
Exam 11: Investments in Noncurrent Operating Assets-Utilization and Retirement84 Questions
Exam 12: Debt Financing103 Questions
Exam 13: Equity Financing88 Questions
Exam 14: Investments in Debt and Equity Securities81 Questions
Exam 15: Leases80 Questions
Exam 16: Income Taxes77 Questions
Exam 17: Employee Compensation-Payroll, Pensions, Other Comp Issues78 Questions
Exam 18: Earnings Per Share78 Questions
Exam 19: Derivatives, Contingencies, Business Segments, and Interim Reports79 Questions
Exam 20: Accounting Changes and Error Corrections74 Questions
Exam 21: Statement of Cash Flows Revisited61 Questions
Exam 22: Accounting in a Global Market60 Questions
Exam 23: Analysis of Financial Statements57 Questions
Select questions type


A major conclusion of the FASB's standard on accounting for stock options is that fixed option plans for which the option price is equal to the market price of the stock at the date of grant will result in compensation cost. Under APB Opinion No. 25, such plans generated no such compensation cost if the exercise price was greater than or equal to the market price at the grant date. Under the FASB standard, compensation expense would be measured by the value of the option rather than the spread between the option price and the market price of the stock at the grant date.
One means of measuring the value of the option itself is the use of a mathematical model, such as the Black-Scholes option pricing model. This model considers both the minimum value and volatility values in measuring the fair value of an option. The minimum value is the current price of the stock minus both the present value of the exercise price and the present value of expected dividends on the stock during the term of the option, both discounted at the risk-free rate of return. The volatility value is a measure of the amount by which the price of the stock has fluctuated or is expected to fluctuate during a period. Volatility is measured by the standard deviation of a probability distribution. The larger the standard deviation in relation to average price level, the more variable the price.
Identify the objections that might be raised to the use of the Black-Scholes mathematical option pricing model in valuing options issued as part of a stock compensation plan.
(Essay)
4.8/5  (87)
(87) On September 1, 2011, Steelers Corporation declared and issued a 20 percent common stock dividend. Prior to this date, Steelers had 20,000 shares of $2 par value common stock that were both issued and outstanding. The market value of Steelers' stock was $20 per share at the time the dividend was issued. As a result of this stock dividend, Steelers' total stockholders' equity
(Multiple Choice)
4.9/5 (65)
(65) Victor Corporation was organized on January 2 with 100,000 authorized shares of $10 par value common stock. During the year, Victor had the following capital transactions:
 Victor used the par value method to record the purchase of the treasury shares.
What would be the balance in the paid-in capital from treasury stock account at December 31?
Victor used the par value method to record the purchase of the treasury shares.
What would be the balance in the paid-in capital from treasury stock account at December 31? (Multiple Choice)
4.9/5 (93)
(93) The FASB has been struggling with the issue of determining the difference between debt and equity financing for nearly twenty years. The Board is concerned that many provisions of U.S. GAAP conflict with the definition of a liability given in the Conceptual Framework. As a result, the Board is considering a new approach to distinguishing between debt and equity financing.
The method currently favored by the FASB is called the "basic ownership approach."
Required:
Explain the basic ownership approach and identify what effects, if any, this approach would have on financial accounting and reporting.
(Essay)
4.9/5 (89)
(89) Treasury stock was acquired for cash at a price in excess of its par value. The treasury stock was subsequently reissued for cash at a price in excess of its acquisition price. Assuming that the cost method of accounting for treasury stock transactions is used, what is the effect on retained earnings?

(Short Answer)
4.9/5 (94)
(94) The accounts from the stockholders' equity section of the balance sheet of Western Company showed the following at December 31, 2010:
 Western issued 475,000 shares of the $1 par value common stock on January 1, 2010.
The company also is authorized to issue 500,000 shares of $5 par value, 6% preferred stock.
During 2011, Western had the following transactions:
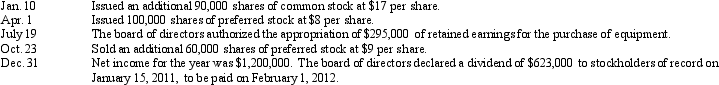 Prepare a statement of changes in stockholders' equity for 2011 using the information given above.
Western issued 475,000 shares of the $1 par value common stock on January 1, 2010.
The company also is authorized to issue 500,000 shares of $5 par value, 6% preferred stock.
During 2011, Western had the following transactions:
Prepare a statement of changes in stockholders' equity for 2011 using the information given above. (Essay)
5.0/5 (83)
(83) On January 2, 2011 the board of directors of Gimli Mining Corporation declared a cash dividend of $1,200,000 to stockholders of record on January 18, 2011, and payable on February 10, 2011. The dividend is permissible by law in Gimli's state of incorporation. Selected data from Gimli's December 31, 2010, balance sheet follow:
 The $1,200,000 dividend includes a liquidating dividend of
 (Multiple Choice)
4.9/5 (76)
(76) Which of the following is not one of the basic shareholders rights?
(Multiple Choice)
4.9/5 (67)
(67) Gains and losses on the purchase and resale of treasury stock may be reflected only in
(Multiple Choice)
4.7/5 (77)
(77) Thorpe Corporation holds 10,000 shares of its $10 par common stock as treasury stock, which was purchased in 2010 at a cost of $120,000. On December 10, 2011, Thorpe sold all 10,000 shares for $210,000. Assuming that Thorpe used the cost method of accounting for treasury stock, this sale would result in a credit to
(Multiple Choice)
4.9/5 (69)
(69) On March 2, 2011, Ross Corporation issued 4,000 shares of 6 percent cumulative $100 par value preferred stock for $434,000. Each preferred share carried one nondetachable stock warrant which entitled the holder to acquire, at $17, one share of Ross $10 par common stock. On March 2, 2011, the market price of the preferred stock (without warrants) was $90 per share and the market price of the stock warrants was $15 per warrant. The amount credited to Paid-In Capital in Excess of Par-Preferred by Ross on the issuance of the stock was
(Multiple Choice)
5.0/5 (78)
(78) On August 10, Jameson Corporation reacquired 8,000 shares of its $100 par value common stock at $134. The stock was originally issued at $110. The shares were resold on November 21 at $145.
Provide the entries required to record the reacquisition and the subsequent resale of the stock using the:

(Essay)
4.9/5 (80)
(80) On December 10, Daniel Co. split its stock 5-for-2 when the market value was $65 per share. Prior to the split, Daniel had 200,000 shares of $15 par value stock. After the split, Daniel's outstanding shares would be
(Multiple Choice)
4.9/5 (81)
(81) On June 1, 2011, Patriot Corporation declared a stock dividend entitling its stockholders to one additional share for each share held. At the time the dividend was declared, the market value of the stock was $10 per share and the par value was $5 per share. On this date Patriot had 1,000,000 shares of common stock authorized of which 600,000 shares were outstanding. Assuming the par value of the stock was not changed, what entry should Patriot make to record this transaction?
(Multiple Choice)
4.8/5 (80)
(80) Which of the following is most likely to be found in state laws regarding payment of dividends?
(Multiple Choice)
4.7/5 (83)
(83) Cohen Corporation owns 1,000 shares of common stock of Berg, Inc., a large publicly traded company listed on a major stock exchange. If Berg issues a 20 percent stock dividend when the par value is $10 per share and the market value is $70 per share, how much and what type of income should Cohen report?
(Multiple Choice)
4.8/5 (76)
(76) On July 1, Black Corporation had 200,000 shares of $10 par common stock outstanding. The market price of the stock was $12 per share. On the same date, Black declared a 1-for-2 reverse stock split. The par value of the stock was increased from $10 to $20, and one new $20 par share was issued for each two $10 par shares outstanding. Immediately before the 1-for-2 reverse stock split, Black's additional paid-in capital was $650,000. What should be the balance in Black's additional paid-in capital account immediately after the reverse stock split?
(Multiple Choice)
4.9/5 (90)
(90) The stockholders' equity section of Dolphin Corporation as of December 31, 2011, contained the following accounts:
 Dolphin's board of directors declared a 10 percent stock dividend on April 1, 2012, when the market value of the stock was $7 per share. Accordingly, 1,000 new shares were issued. All of Dolphin's stock has a par value of $3 per share. Assuming Dolphin sustained a net loss of $12,000 for the quarter ended March 31, 2012, what amount should Dolphin report as retained earnings as of April 1, 2012?
 (Multiple Choice)
4.7/5 (70)
(70) Thomas Company reported the following for the year ended December 31, 2011 (all items are net of income taxes):
 Comprehensive income (loss) for the year ended December 31, 2011, would be
 (Multiple Choice)
4.9/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)