



 Chat with AI
Exam 6: Corporate Liquidating Distributions

Exam 1: Tax Research107 Questions
Exam 2: Corporate Formations and Capital Structure120 Questions
Exam 3: The Corporate Income Tax116 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies59 Questions
Exam 6: Corporate Liquidating Distributions103 Questions
Exam 7: Corporate Acquisitions and Reorganizations104 Questions
Exam 8: Consolidated Tax Returns90 Questions
Exam 9: Partnership Formation and Operation115 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures105 Questions
Exam 16: Us Taxation of Foreign-Related Transactions86 Questions
Select questions type


Penny, a cash-basis taxpayer, reported a $15,000 long-term capital gain on the exchange of her Midwest Corporation stock when the corporation liquidated in 2016. Midwest subsequently lost a lawsuit and Penny paid an additional $3,000 in 2018 as her part of the settlement. What are the tax consequences to Penny in 2018 of the $3,000 additional payment she made?
(Essay)
4.8/5  (82)
(82) Cowboy Corporation owns 90% of the single class of stock in Doggie Corporation. The other 10% is owned by Miguel, an individual. Cowboy's basis in its Doggie Corporation stock is $100,000 and Miguel's basis is $50,000. Doggie Corporation distributes property having an adjusted basis of $150,000 and an FMV of $500,000 to Cowboy Corporation, and $60,000 of money to Miguel as a liquidating distribution. Doggie and Cowboy Corporations must recognize gain of:
(Multiple Choice)
4.8/5 (83)
(83) Carly owns 25% of Base Corporation's single class of stock and Premier Corporation owns the remaining 75%. Carly's basis in the Base stock is $200,000 and Premier Corporation's basis in the Base stock is $600,000. Carly receives property with a $175,000 adjusted basis and a $250,000 FMV and Premier Corporation receives property with a $600,000 adjusted basis and a $750,000 FMV in complete liquidation of Base Corporation. All of Base's cash is used to pay its liabilities. Which of following statements is correct concerning the tax effects of the liquidation?
(Multiple Choice)
4.7/5 (82)
(82) When a corporation liquidates, it performs three activities. What is the general order of these activities in a plan of liquidation?
(Multiple Choice)
4.9/5 (73)
(73) Section 336 prevents recognition of a loss when making a pro rata distribution of property to a related person.
(True/False)
4.7/5 (82)
(82) Charlene and Dennis each own 50% of Brewster Corporation and have owned it for five years. The adjusted bases of their Brewster stock are $80,000 and $40,000 respectively. Brewster Corporation liquidates and distributes $60,000 to Charlene in exchange for her stock. It distributes a parcel of land with a $140,000 FMV which is subject to a $90,000 mortgage to Dennis in exchange for his stock. Dennis assumes the mortgage and also receives $10,000 in cash.
a) What is the character and amount of each shareholder's gain or loss?
b) What is each shareholder's basis in the property received in the liquidation?
(Essay)
4.8/5 (84)
(84) Dusty Corporation owns 90% of Palace Corporation's stock and Susan owns the remaining stock. Dusty Corporation's stock basis is $300,000 and Susan's stock basis is $20,000. Under a plan of complete liquidation, Dusty Corporation receives property with a $400,000 adjusted basis and a $540,000 FMV and Susan receives property with a $20,000 adjusted basis and a $60,000 FMV. The bases of the properties are:
(Multiple Choice)
4.9/5 (75)
(75) Specialty Corporation distributes land to one of its shareholders, Sam, as part of a plan of liquidation. The land, which was used in Specialty's business, has an adjusted basis of $50,000 and an FMV of $130,000 on the date of distribution. Sam's basis in Specialty Corporation stock is $100,000. What is the amount and character of the gain/loss recognized by Specialty Corporation? What is the amount and character of the gain/loss recognized by Sam?
(Essay)
4.9/5 (75)
(75) A plan of liquidation must be reduced to writing in order to be accepted by the Internal Revenue Service.
(True/False)
4.8/5 (65)
(65) Ball Corporation owns 80% of Net Corporation's stock and Jack owns the remaining 20% of Net Corporation's stock. Ball's basis in the Net stock is $200,000 and Jack's basis in the Net stock is $100,000. Under a plan of complete liquidation, Ball Corporation receives property with an adjusted basis of $400,000 and an FMV of $800,000 and Jack receives property with an adjusted basis of $50,000 and an FMV of $200,000. Ball and Jack's bases in the property received are:
(Multiple Choice)
4.7/5 (84)
(84) Sandy, a cash method of accounting taxpayer, has a basis of $46,000 in her 500 shares of Newt Corporation stock. She receives the following distributions as part of Newt's plan of liquidation. 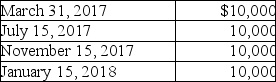 The amount of the final distribution is not known on December 31, 2017. What are the tax consequences of the distributions?
 (Multiple Choice)
4.9/5 (81)
(81) Jack Corporation is owned 75% by Sherri and 25% by Mark. Sherri and Mark have $125,000 and $50,000 bases in their stock, respectively. Jack Corporation adopts a plan of liquidation on March 1. On April 12, Sherri receives the following property as a liquidating distribution: cash of $30,000; land, $125,000 FMV; and 150 shares of Green Corporation stock, $30,000 FMV. The land is subject to a $20,000 mortgage. On the same date, Mark receives $10,000 FMV of Green stock (50 shares) and cash of $45,000 as a liquidating distribution. The land has a basis of $50,000 and the stock has a basis of $70,000 in Jack Corporation's hands. Both are capital assets to Jack Corporation and have been held for a number of years.
a) What is the amount and character of Jack Corporation's recognized gain or loss on the liquidating distributions?
b) What are the amounts and characters of Sherri and Mark's recognized gains or losses?
c) What are the bases of the land and stock to Sherri and Mark?
(Essay)
4.9/5 (86)
(86) Dexer Corporation is owned 70% by Amy and 30% by Brad. Dexer Corporation owns Eagle Corporation stock with a $50,000 adjusted basis and a $30,000 FMV. The stock is not disqualified property. As part of a complete liquidation, the Eagle Corporation stock is distributed to Amy. Amy's basis in her Dexer stock is $40,000. Dexer Corporation will recognize
(Multiple Choice)
4.8/5 (71)
(71) Greg, a cash method of accounting taxpayer, owns 100 shares of Parker Corporation stock with a basis of $20,000. Greg receives two liquidating distributions of $8,000 on March 3 of last year, and $8,000 on August 8 of this year. The amount of the second distribution is not known until June 15 of this year. Greg recognizes
(Multiple Choice)
4.9/5 (81)
(81) Under Illinois Corporation's plan of liquidation, the corporation distributes land to one of its shareholders, Springer. The land, which is used in Illinois trade or business, has a $20,000 adjusted basis and a $60,000 FMV on the distribution date. What are the tax consequences of this distribution to Illinois and Springer?
(Essay)
4.9/5 (88)
(88) Riverwalk Corporation is liquidated, with Juan receiving $5,000 in money, other property having a $6,000 FMV, and a $1,000 mortgage on the property. Juan's basis in his River walk stock is $8,000. Upon liquidation, Juan must recognize a gain of
(Multiple Choice)
4.9/5 (75)
(75) Under the general liquidation rules, Missouri Corporation is liquidated, with Jefferson receiving $5,000 in cash plus other property having a $6,000 FMV and assuming a $2,000 mortgage on the property. Jefferson's basis in his Missouri stock is $8,000. What is Jefferson's amount realized and gain or loss recognized on the liquidation?
(Essay)
4.9/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)