



 Chat with AI
Exam 10: Special Partnership Issues

Exam 1: Tax Research107 Questions
Exam 2: Corporate Formations and Capital Structure120 Questions
Exam 3: The Corporate Income Tax116 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies59 Questions
Exam 6: Corporate Liquidating Distributions103 Questions
Exam 7: Corporate Acquisitions and Reorganizations104 Questions
Exam 8: Consolidated Tax Returns90 Questions
Exam 9: Partnership Formation and Operation115 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures105 Questions
Exam 16: Us Taxation of Foreign-Related Transactions86 Questions
Select questions type


If a partner dies, his or her tax year closes

Free
(Multiple Choice)
4.7/5  (81)
(81) Correct Answer: Verified
A
The HMS Partnership, a cash method of accounting entity, has the following balance sheet at December 31 of last year:
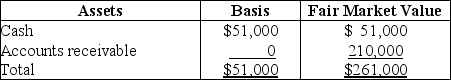
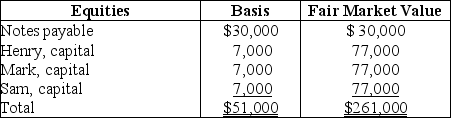 Sam, who has a one-third interest in profits, losses, and liabilities, sells his partnership interest to Beverly, for $77,000 cash on January 1 of this year. Sam's basis in his partnership interest (which, of course, includes a share of partnership liabilities) at the time of the sale was $17,000. In addition, Beverly assumes Sam's share of the partnership liabilities. What is the amount and character of the gain that Sam will recognize from this sale?
Free
(Essay)
4.8/5 (87)
(87) Correct Answer:Verified
VerifiedAmount realized = $77,000 + $10,000 liabilities assumed = $87,000.
Realized and recognized gain = $87,000 - $17,000 = $70,000.
The recognized gain is all ordinary income, since it equals his share of the unrealized receivables.
Identify which of the following statements is true.
Free
(Multiple Choice)
4.8/5 (85)
(85) Correct Answer:Verified
VerifiedB
For tax purposes, a partner who receives retirement payments ceases to be regarded as a partner
(Multiple Choice)
4.9/5 (74)
(74) The STU Partnership, an electing Large Partnership, has no passive activities and reports the following transactions for the year: net long-term capital losses $50,000, Sec. 1231 gain $60,000, ordinary income $20,000, charitable contributions $15,000, and tax-exempt income $2,000. How much will be reported as ordinary income to its partners?
(Multiple Choice)
4.7/5 (78)
(78) What conditions are required for a partner to recognize a loss upon receipt of a distribution from a partnership?
(Essay)
4.8/5 (74)
(74) Which of the following is a valid reason for making a 754 election?
(Multiple Choice)
4.9/5 (77)
(77) Two years ago, Tom contributed investment land with a basis of $50,000 and an FMV of $62,000 to the RST Partnership. This year, Tom has a basis in his partnership interest of $53,000 when he receives a current distribution of $14,000 cash and inventory with a basis of $35,000 and an FMV of $52,000. (There is no Sec. 751 exchange in connection with the inventory distribution.) The partnership continues to hold the land Tom contributed. How much gain (if any) must Tom recognize as a result of this distribution?
(Essay)
4.8/5 (84)
(84) Becky has a $24,000 basis in her partnership interest. She receives a current distribution of $4,000 cash, unrealized receivables with a basis of $12,000 and an FMV of $16,000, and land held as an investment with a basis of $3,000 and an FMV of $8,000. The partners' relative interests in the Sec. 751 assets do not change as a result of the current distribution. The basis of her partnership interest following the distribution is
(Multiple Choice)
4.7/5 (77)
(77) Eicho's interest in the DPQ Partnership is terminated when her basis in the partnership is $70,000. She receives a liquidating distribution of $20,000 cash and inventory with a $24,000 basis and a $40,000 FMV. What is her gain or loss, and what is her basis in the inventory received?
(Essay)
4.8/5 (89)
(89) Helmut contributed land with a basis of $5,000 and an FMV of $10,000 to the HG Partnership five years ago to acquire a 50% partnership interest. This year the land is distributed to another partner, Gail, when its FMV is $11,000. No other distributions have been made since Helmut became a partner. When the land is distributed to Gail, Helmut recognizes a gain of
(Multiple Choice)
4.9/5 (85)
(85) Patrick purchased a one-third interest in the PPP partnership for $600,000. At the time of the purchase, the partnership had a 754 election in effect and its only asset was land with a basis of $1,500,000. This year, PPP sells the land for $1,800,000. What is Patrick's recognized share of the gain on the sale of the land?
(Multiple Choice)
4.9/5 (84)
(84) Eicho's interest in the DPQ Partnership is terminated when her basis in the partnership is $70,000. She receives a liquidating distribution of $20,000 cash and inventory with a $24,000 basis and a $40,000 FMV. She also receives, as part of the distribution, a desk that has a $100 basis and a $200 FMV to the partnership. What is her gain or loss, and what is her basis in the items received?
(Essay)
4.8/5 (81)
(81) Under Sec. 751, unrealized receivables include potential Section 1245 or 1250 recapture on the partnership's depreciable property.
(True/False)
4.9/5 (76)
(76) Under the check-the-box rules, an LLC with more than one member is taxed as a partnership unless it elects to be taxed as a corporation.
(True/False)
4.9/5 (79)
(79) What are some advantages and disadvantages of making a Section 754 election?
(Essay)
4.8/5 (82)
(82) Kenya sells her 20% partnership interest having a $28,000 basis to Ebony for $40,000 cash. At the time of the sale, the partnership has no liabilities and its assets are as follows: 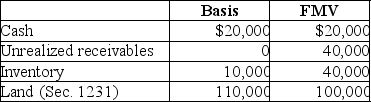 Kenya and Ebony have no agreement concerning the allocation of the sales price. Ordinary income recognized by Kenya as a result of the sale is
 (Multiple Choice)
4.8/5 (82)
(82) A partner's holding period for a partnership interest is never considered when determining the holding period for property distributed in a liquidating distribution.
(True/False)
4.9/5 (83)
(83) Quinn and Pamela are equal partners in the QP Partnership. On December 30 of the current year, the QP Partnership agrees to liquidate Quinn's partnership interest for a cash payment on December 30 of each of the next five years. What tax issues should Quinn and Pamela consider with respect to the liquidation of Quinn's partnership interest?
(Essay)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)