



 Chat with AI
Exam 10: Property, Plant, and Equipment: Acquisition and Disposal

Exam 1: The Environment of Financial Reporting41 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System87 Questions
Exam 4: The Balance Sheet and the Statement of Changes in Stockholders Equity78 Questions
Exam 5: The Income Statement and the Statement of Cash Flows104 Questions
Exam 6: Additional Aspects of Financial Reporting and Financial Analysis95 Questions
Exam 7: Cash and Receivables99 Questions
Exam 8: Inventories: Cost Measurement and Flow Assumptions89 Questions
Exam 9: Inventories: Special Valuation Issues109 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Disposal88 Questions
Exam 11: Depreciation and Depletion103 Questions
Exam 12: Intangibles84 Questions
Exam 13: Current Liabilities and Contingencies99 Questions
Exam 14: Long-Term Liabilities and Receivables140 Questions
Exam 15: Investments101 Questions
Exam 16: Contributed Capital121 Questions
Exam 17: Earnings Per Share and Retained Earnings86 Questions
Exam 18: Income Recognition and Measurement of Net Assets71 Questions
Exam 19: Accounting for Income Taxes74 Questions
Exam 20: Accounting for Postemployment Benefits68 Questions
Exam 21: Accounting for Leases114 Questions
Exam 22: The Statement of Cash Flows62 Questions
Exam 23: Accounting for Changes and Errors86 Questions
Exam 24: Time Value of Money Module72 Questions
Select questions type


A major difference between IFRS and GAAP regarding valuation of property, plant, and equipment is that
(Multiple Choice)
4.8/5  (76)
(76) On January 1, 2010, Rong Company signed a contract to have Rozy Associates construct a manufacturing facility at a cost of $14, 000, 000.It was estimated that it would take three years to complete the project.Also on January 1, 2010, to finance the construction cost, Rong borrowed $14, 000, 000 payable in seven annual installments of $2, 000, 000 plus interest at the rate of 9%.During 2010, Rong made progress payments totaling $5, 000, 000 under the contract, and the average amount of accumulated expenditures was $3, 000, 000 for the year.The excess borrowed funds were invested in short-term securities, from which Rong realized investment income of $330, 000.What amount should Rong report as capitalized interest at December 31, 2010?
(Multiple Choice)
4.9/5 (96)
(96) A plant site donated by a city to Rupp Company, which plans to open a new factory, should be recorded on Rupp's books at
(Multiple Choice)
4.9/5 (81)
(81) In 2010, Golf Oil Company incurred costs of $7 million drilling oil wells.Thirty percent of the drilling resulted in oil being found.The rest of the drilling was unsuccessful.If Golf uses the successful-efforts method of accounting, the oil and gas properties will be valued on the December 31, 2010 balance sheet at
(Multiple Choice)
5.0/5 (85)
(85) Rebby Company received $60, 000 in cash and used equipment with a fair value of $140, 000 from Farley Corporation for Rebby's existing equipment, which had a fair value of $200, 000 and an undepreciated cost of $170, 000 recorded on its books.The transaction was undertaken because Rebby was revising its market strategy and planned to reduce the use of this type of equipment in its production.How much gain should Rebby recognize on this exchange, and at what amount should the acquired equipment be recorded, respectively?
(Multiple Choice)
4.9/5 (81)
(81) Costs incurred by Mills Company that relate to its property, plant, and equipment assets might be recorded in one of the five following classes of accounts:
a. an expense account
b. an accumulated depreciation accoun
c. a land account
d. a building account
e. an equipment account Required:
For each of the costs identified below, indicate the type of account in which the cost should be recorded by placing the appropriate letter in the space provided.
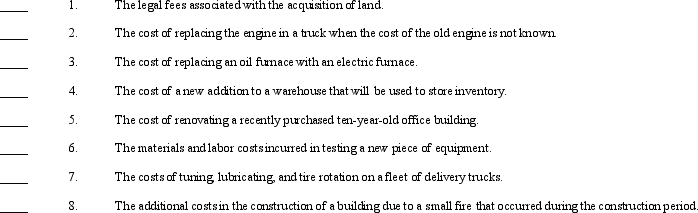
(Essay)
4.9/5 (89)
(89) The costs of drilling an unsuccessful well are expensed under
(Multiple Choice)
4.9/5 (68)
(68) When boot is involved in the exchange of nonmonetary productive assets, normally
(Multiple Choice)
4.9/5 (82)
(82) Performance Stage Company had a professional contract with Actor #1 that was recorded in its accounting records at $300, 000.Johnson Company had a contract with Actor #2 that was recorded in its accounting records at $280, 000.Performance traded Actor #1 to Johnson for Actor #2 by exchanging the actors' contracts.The fair value of each contract was $320, 000.What amount should be shown in the accounting records after the exchange of actor contracts? Performance Johnson I. \ 280,000 \ 280,000 II. \ 280,000 \ 300,000 III. \ 300,000 \ 280,000 IV. \ 320,000 \ 320,000
(Multiple Choice)
4.9/5 (89)
(89) Exhibit 10-1 Two construction companies, Fargo and Rambam, are in the construction business.Each owns a tract of land being held for development, but each company believes that the other's land is better suited to enhance the success of each planned development.Accordingly, they agree to exchange their land and have the following information:
Fargo's Rambam's Land Land Cost and book value \ 400,000 \ 250,000 Fair value based upon appraisal \ 500,000 \ 450,000 The exchange of land was made, and based on the difference in appraised fair value, Rambam paid $50, 000 cash to Fargo.
-
Refer to Exhibit 10-1.After the exchange, Fargo should record its newly acquired land on its books at
(Multiple Choice)
5.0/5 (74)
(74) All of the following costs associated with acquiring a building should be capitalized except
(Multiple Choice)
4.9/5 (57)
(57) Randal's Rifles purchased some equipment by issuing a three-year 6% note for $8, 000 when the market rate for an obligation of this nature was 8%.The interest is payable annually.Actuarial information for three periods follows: 6\% 8\% Future amount of 1 1.191016 1.259712 Future amount of amuity of 1 3.183600 3.246400 Present value of 1 0.839619 0.793832 Present value of annuity of 1 2.673012 2.577097
At the date of purchase, what amount should be debited to Equipment?
(Multiple Choice)
4.9/5 (84)
(84) On January 4, 2010, Rack Company traded in a used bulldozer with a carrying amount of $65, 000 for a new bulldozer having a list price of $120, 000 and paid cash difference of $40, 000 to the dealer.The used bulldozer had a fair value of $75, 000 on the date of exchange.At what amount should the new bulldozer be recorded on Rack's books?
(Multiple Choice)
4.8/5 (81)
(81) On January 3, 2010, Mercury Company began self-constructing an asset that qualified for interest capitalization.On January 5, Mercury borrowed $300, 000 on an 8% construction loan.In addition, Mercury had $400, 000 of 6% notes payable and $700, 000 of 9% bonds payable outstanding.By December 31, expenditures (occurring evenly throughout the year)of $800, 000 had been made on the asset.Investment of unused funds during the year yielded $1, 200 of interest revenue.
Required:
Compute the amount of interest that should be capitalized during 2010.
(Essay)
4.9/5 (74)
(74) When an operating asset is made up of significant individual components, IFRS require the company to
(Multiple Choice)
4.9/5 (86)
(86) Two alternative methods of accounting for the cost of oil and gas properties have been widely used.The method that capitalizes all costs associated with all wells is the
(Multiple Choice)
4.9/5 (81)
(81) Which one of the following types of assets should not be classified as property, plant, and equipment?
(Multiple Choice)
4.8/5 (80)
(80) All of the following are arguments in favor of including only the incremental fixed overhead costs in the cost of a self-constructed asset, except that the
(Multiple Choice)
4.9/5 (92)
(92) All of the following would be classified as property, plant, and equipment except
(Multiple Choice)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)