



 Chat with AI
Exam 19: Accounting for Income Taxes

Exam 1: The Environment of Financial Reporting41 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System87 Questions
Exam 4: The Balance Sheet and the Statement of Changes in Stockholders Equity78 Questions
Exam 5: The Income Statement and the Statement of Cash Flows104 Questions
Exam 6: Additional Aspects of Financial Reporting and Financial Analysis95 Questions
Exam 7: Cash and Receivables99 Questions
Exam 8: Inventories: Cost Measurement and Flow Assumptions89 Questions
Exam 9: Inventories: Special Valuation Issues109 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Disposal88 Questions
Exam 11: Depreciation and Depletion103 Questions
Exam 12: Intangibles84 Questions
Exam 13: Current Liabilities and Contingencies99 Questions
Exam 14: Long-Term Liabilities and Receivables140 Questions
Exam 15: Investments101 Questions
Exam 16: Contributed Capital121 Questions
Exam 17: Earnings Per Share and Retained Earnings86 Questions
Exam 18: Income Recognition and Measurement of Net Assets71 Questions
Exam 19: Accounting for Income Taxes74 Questions
Exam 20: Accounting for Postemployment Benefits68 Questions
Exam 21: Accounting for Leases114 Questions
Exam 22: The Statement of Cash Flows62 Questions
Exam 23: Accounting for Changes and Errors86 Questions
Exam 24: Time Value of Money Module72 Questions
Select questions type


On December 31, 2010, the South Padre Company had a deferred tax liability balance of $8, 100, arising from an excess of MACRS depreciation for tax purposes over straight-line depreciation for accounting purposes.The tax effects of that timing difference are expected to reverse in the following years:
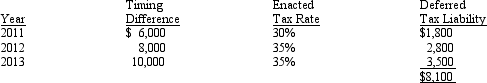 On January 27, 2011, Congress raised the effective income tax rate to 38% for all future years, including the current year, 2011.
Required:
Prepare the entry to record any adjustments necessary due to the income tax rate increase on January 27, 2011.
On January 27, 2011, Congress raised the effective income tax rate to 38% for all future years, including the current year, 2011.
Required:
Prepare the entry to record any adjustments necessary due to the income tax rate increase on January 27, 2011.
Free
(Essay)
4.8/5  (83)
(83) Correct Answer: Verified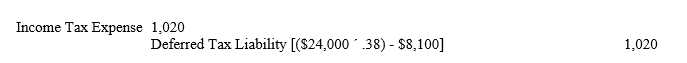
Which one of the following requires intraperiod tax allocation?
Free
(Multiple Choice)
4.8/5 (81)
(81) Correct Answer:Verified
VerifiedD
Examples of positive evidence cited by the FASB to indicate that a valuation allowance for the tax benefits from a deferred tax asset is not needed include all of the following except
Free
(Multiple Choice)
4.8/5 (80)
(80) Correct Answer:Verified
VerifiedC
Which one of the following transactions would result in the creation of a noncurrent deferred tax liability?
(Multiple Choice)
4.8/5 (72)
(72) The recognition of gross profit on installment sales at point of sale for financial reporting purposes but reporting the profit when the cash is received for income tax purposes results in deferred taxes reported in which section of the balance sheet?
(Multiple Choice)
5.0/5 (76)
(76) Which of the following activities does not result in a "tax credit" for income tax purposes?
(Multiple Choice)
4.9/5 (79)
(79) The asset/liability method of tax allocation should be followed for Interperiod Income Intraperiod Incom Tax Allocation Tax Allocation I. Yes Yes II. No No III. Yes No IV No Yes
(Multiple Choice)
4.9/5 (75)
(75) On January 1, 2010, Bedford Company began recognizing revenues from all sales under the accrual method for financial reporting purposes and under the installment sales method for income tax purposes.Bedford reported the following gross margin on sales for 2010 and 2011: Accual Installment Year Method Sales Methoo 2010 \ 1,200,000 \ 1,000,000 2011 1,800,000 1,400,000
The enacted tax rate for both 2010 and 2011 was 30%.Assuming there are no other temporary differences, Bedford's December 31, 2011 balance sheet would report a deferred tax liability of
(Multiple Choice)
4.9/5 (65)
(65) Permanent differences between pretax financial income and taxable income result when
(Multiple Choice)
5.0/5 (81)
(81) As of December 31, 2010, the Austin Company reported a deferred tax asset of $60, 000 related to accrued, unpaid warranty costs.However, since profits have been declining, Austin decides that it is more likely than not that $24, 000 of the deferred tax asset will not be realized.The entry to record the valuation allowance would include a
(Multiple Choice)
4.8/5 (79)
(79) Interperiod tax allocation is required for all of the following situations except
(Multiple Choice)
4.9/5 (66)
(66) Which of the following is not a timing difference that would cause pretax financial accounting income to differ from taxable income?
(Multiple Choice)
4.9/5 (78)
(78) Exhibit 19-1 On December 31, 2009, Fort Stockton, Inc.had no temporary differences that created deferred income taxes.On January 2, 2010, a new machine was purchased for $30, 000.Straight-line depreciation over a four-year life (no residual value)was used for financial accounting.Depreciation expense for tax purposes was $11, 000 in 2010, $9, 000 in 2011, $6, 000 in 2012, and $4, 000 in 2013.In each year, the income tax rate was 20% and Fort Stockton had no other items that created differences between pretax financial income and taxable income.Fort Stockton reported the following pretax financial income for 2010 through 2013:
2010 \ 50,000 2011 40,000 2012 30,000 2013 60,000
- Refer to Exhibit 19-1.The entry to record income taxes on December 31, 2011, would include a
(Multiple Choice)
4.8/5 (82)
(82) Which statement regarding the objectives of financial accounting and the Internal Revenue Code is true?
(Multiple Choice)
5.0/5 (73)
(73) The Pilot Point Company began operations in 2010 and, for that calendar year, reported an operating loss of $230, 000.Due to sufficient verifiable positive evidence, no valuation allowance was established to reduce the deferred tax asset as of December 31, 2010.During 2011, Pilot Point reported pretax accounting income of $350, 000.Assuming an income tax rate of 30%, what should Pilot Point record in 2011 as income tax payable at the end of 2011?
(Multiple Choice)
4.8/5 (75)
(75) On December 31, 2009, Lake Jackson, Inc.reported a deferred tax liability of $1, 875, based on the following schedule of future taxable amounts and enacted tax rates:
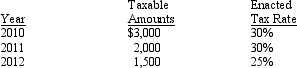 On February 7, 2010, Congress amended a previously passed tax law.The amendment changed the tax rate to 35% for 2010 and all future years.
Required:
Prepare the income tax journal entry for Lake Jackson, Inc.necessary on February 7, 2010.
On February 7, 2010, Congress amended a previously passed tax law.The amendment changed the tax rate to 35% for 2010 and all future years.
Required:
Prepare the income tax journal entry for Lake Jackson, Inc.necessary on February 7, 2010. (Essay)
4.9/5 (75)
(75) When Congress changes the tax laws or rates, a corporation's deferred tax liability and asset accounts
(Multiple Choice)
5.0/5 (81)
(81) Langtry Corporation began operations in 2009 and appropriately recorded a deferred tax liability at the end of 2009 and 2010 based on the following depreciation temporary differences between pretax financial income and taxable income: Income Tax Financial Year Depreciation Depreciation 2009 \ 800 \ 400 2010 600 400 2011 400 400 2012 200 400 2013 0 400
The income tax rate for 2009 and 2010 was 30%.In February 2011, due to budget constraints, Congress enacted an income tax rate of 35%.The journal entry required to adjust the Deferred Tax Liability account in February 2011 would be
(Multiple Choice)
4.7/5 (82)
(82) Sherman Company uses an accelerated depreciation method for income tax purposes and the straight-line depreciation method for financial reporting purposes.As of December 31, 2010, Sherman has a deferred tax liability balance related to depreciation temporary differences of $80, 000.In 2011, depreciation for income tax purposes was $260, 000, while depreciation for financial reporting purposes was $200, 000.If the income tax rate is 30%, no other temporary or permanent differences exist, and taxable income is $300, 000, the entry to record income tax expense on December 31, 2011, would include a
(Multiple Choice)
4.7/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)