



 Chat with AI
Exam 19: Accounting for Income Taxes

Exam 1: The Environment of Financial Reporting41 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System87 Questions
Exam 4: The Balance Sheet and the Statement of Changes in Stockholders Equity78 Questions
Exam 5: The Income Statement and the Statement of Cash Flows104 Questions
Exam 6: Additional Aspects of Financial Reporting and Financial Analysis95 Questions
Exam 7: Cash and Receivables99 Questions
Exam 8: Inventories: Cost Measurement and Flow Assumptions89 Questions
Exam 9: Inventories: Special Valuation Issues109 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Disposal88 Questions
Exam 11: Depreciation and Depletion103 Questions
Exam 12: Intangibles84 Questions
Exam 13: Current Liabilities and Contingencies99 Questions
Exam 14: Long-Term Liabilities and Receivables140 Questions
Exam 15: Investments101 Questions
Exam 16: Contributed Capital121 Questions
Exam 17: Earnings Per Share and Retained Earnings86 Questions
Exam 18: Income Recognition and Measurement of Net Assets71 Questions
Exam 19: Accounting for Income Taxes74 Questions
Exam 20: Accounting for Postemployment Benefits68 Questions
Exam 21: Accounting for Leases114 Questions
Exam 22: The Statement of Cash Flows62 Questions
Exam 23: Accounting for Changes and Errors86 Questions
Exam 24: Time Value of Money Module72 Questions
Select questions type


Duncanville Company appropriately uses the installment sales method for tax purposes and the accrual method for revenue recognition for accounting purposes.Pertinent data at December 31, 2010, the close of the first year of operations, are as follows: Revenue Recognized Revenue Recogrized Customer for Accounting Purposes for Tax Purposes Ace'sBuilders \ 200,000 \ 100,000 Tip Top Plumbing 500,000 350,000 Clearly Windows 600,000 350,000
Duncanville's tax rate is 30%.What amount should be included in the deferred tax account at December 31, 2010 for these installment sales?
(Multiple Choice)
4.8/5  (83)
(83) FASB Statement No.109 discussed deferred tax asset measurement in the context of the FASB Conceptual Framework.
Required:
Identify the three essential characteristics of an asset and explain how deferred tax assets meet these characteristics.
(Essay)
5.0/5 (82)
(82) Which of the following would not result in a permanent difference between pretax financial income and taxable income?
(Multiple Choice)
4.7/5 (70)
(70) In 2010, Weatherford Corporation reported pretax financial income of $400, 000.Included in that pretax financial income was $150, 000 of nontaxable life insurance proceeds received as a result of the death of an officer; $120, 000 of warranty expenses accrued but unpaid as of December 31, 2010; and $10, 000 of bad debts estimated to be uncollectible (but not written off as of December 31, 2010).Assuming that no income taxes were previously paid during the year and an income tax rate of 30%, the amount of income taxes payable on December 31, 2010, would be
(Multiple Choice)
4.9/5 (69)
(69) During its first year of operations, 2010, the Hico Company reported both a pretax financial and a taxable loss of $200, 000.The income tax rate is 30% for the current and future years.Due to a sufficient backlog of sales orders, Hico did not establish a valuation allowance to reduce the $60, 000 deferred tax asset.However, early in 2011, one major customer, representing 60% of the 2011 year-end sales backlog, went bankrupt.Hico now believes that it is more likely than not that 70% of the deferred tax asset will not be realized.The entry to record the valuation allowance would be
(Multiple Choice)
4.9/5 (70)
(70) At the end of its first year of operations on December 31, 2010, the Belton Company reported taxable income of $100, 000 and had a pretax financial loss of $60, 000.Differences between taxable income and pretax financial income included interest revenue received from municipal obligations of $20, 000 and warranty expense accruals of $180, 000.Warranty expenses of $90, 000 are expected to be paid in 2011 and $110, 000 in 2012.The enacted income tax rates for 2010, 2011, and 2012 are 30%, 35%, and 40%, respectively.The journal entry to record income tax expense on December 31, 2010, would be
(Multiple Choice)
5.0/5 (76)
(76) Differences between pretax financial income and taxable income in an accounting period that will not reverse in a later accounting period are called
(Multiple Choice)
4.9/5 (75)
(75) The Clear Lake Corporation reported the following differences between its taxable income and pretax financial income for the year ended December 31, 2010: $30, 000 of additional depreciation for tax purposes, $40, 000 of rent collected in advance (taxable when received), and $38, 000 of tax-exempt municipal interest revenue.Assuming an income tax rate of 30% for all years and a taxable income of $190, 000 for the year ended December 31, 2010, income tax expense for 2010 would be
(Multiple Choice)
4.9/5 (84)
(84) Which one of the following would require interperiod tax allocation?
(Multiple Choice)
4.9/5 (81)
(81) All of the following involve a temporary difference for purposes of income tax allocation except
(Multiple Choice)
4.9/5 (83)
(83) Life insurance proceeds payable to a corporation upon the death of an insured employee are an example of
(Multiple Choice)
4.8/5 (75)
(75) The acceptable balance sheet classifications for deferred tax assets and deferred tax liabilities under GAAP and IFRS are 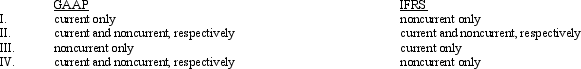
(Multiple Choice)
4.8/5 (68)
(68) Interperiod income tax allocation is based on the assumption that
(Multiple Choice)
4.7/5 (80)
(80) In 2010, its first year of operations, Bandera Corporation reported pretax financial income of $80, 000 for the year ended December 31.Bandera depreciates its fixed assets using an accelerated cost recovery method for tax purposes and straight-line depreciation for financial reporting.On assets acquired in 2010, the following are differences between depreciation on the tax return and accounting income during the asset's five-year life: Tax Depreciation in Excess Enacted of Book- Denreciation Tax Rata 2010 \ 18,000 30\% 2011 10,000 30\% 2012 2,000 35\% 2013 (13,000) 35\% 2014 (17,000) 40\%
Assuming no other temporary or permanent differences, Bandera's December 31, 2010 balance sheet should include
Noncurent Deferred Income Taxes Income Tax Liability Payable I. \ 5,400 \ 18,600 II. \ 7,650 \ 18,600 III. \ 7,650 \ 79,400 IV. \ 5,400 \ 74,000
(Multiple Choice)
4.7/5 (72)
(72) All of the following involve a temporary difference for purposes of income tax allocation except
(Multiple Choice)
4.9/5 (83)
(83) Boerne Company received rent in advance of $9, 000 on December 31, 2010, which was taxable when received for income tax purposes.The company's effective tax rate was 30%, and this was the only temporary difference.Which of the following should be reported on the December 31, 2010 balance sheet?
(Multiple Choice)
4.8/5 (88)
(88) In 2010, its first year of operations, Wichita Falls Company reported pretax accounting income of $60, 000.Included in the $60, 000 was an expense for accrued, unpaid warranty costs of $8, 000, which are not deductible until paid for income tax purposes.Wichita Falls' income tax rate was 20%.The entry to record the income tax expense would include a
(Multiple Choice)
4.8/5 (71)
(71) Which of the following statements regarding the allocation of income taxes is not true?
(Multiple Choice)
4.9/5 (91)
(91) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)