



 Chat with AI
Exam 20: Accounting for Postemployment Benefits

Exam 1: The Environment of Financial Reporting41 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System87 Questions
Exam 4: The Balance Sheet and the Statement of Changes in Stockholders Equity78 Questions
Exam 5: The Income Statement and the Statement of Cash Flows104 Questions
Exam 6: Additional Aspects of Financial Reporting and Financial Analysis95 Questions
Exam 7: Cash and Receivables99 Questions
Exam 8: Inventories: Cost Measurement and Flow Assumptions89 Questions
Exam 9: Inventories: Special Valuation Issues109 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Disposal88 Questions
Exam 11: Depreciation and Depletion103 Questions
Exam 12: Intangibles84 Questions
Exam 13: Current Liabilities and Contingencies99 Questions
Exam 14: Long-Term Liabilities and Receivables140 Questions
Exam 15: Investments101 Questions
Exam 16: Contributed Capital121 Questions
Exam 17: Earnings Per Share and Retained Earnings86 Questions
Exam 18: Income Recognition and Measurement of Net Assets71 Questions
Exam 19: Accounting for Income Taxes74 Questions
Exam 20: Accounting for Postemployment Benefits68 Questions
Exam 21: Accounting for Leases114 Questions
Exam 22: The Statement of Cash Flows62 Questions
Exam 23: Accounting for Changes and Errors86 Questions
Exam 24: Time Value of Money Module72 Questions
Select questions type


If a pension plan amendment is adopted and retroactive benefits are granted to employees, the amount of the prior service cost at the date of grant is accounted for

Free
(Multiple Choice)
4.9/5  (64)
(64) Correct Answer: Verified
D
Given the following information 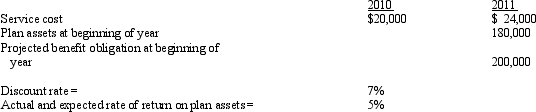 What is pension expense for 2011?
Free
(Multiple Choice)
4.8/5 (89)
(89) Correct Answer:Verified
VerifiedB
A list of terms (a-i)and a list of descriptive phrases (1-9)related to pension accounting are provided below:
a. actuary
b. expectedretum on plan assets
c. defined benefit plan
d. noncontribut ory plan
e. prior service cost
f. service cost
g. accumulated benefits approach
h. pension expense
i.Pension Reform Act of 1974 (ERISA)
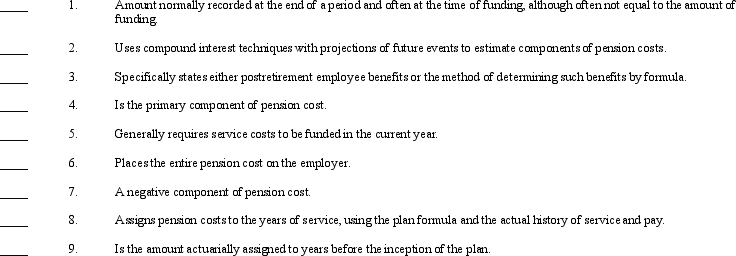 Required:
Match each item to its descriptive phrase by placing the appropriate letter in the space provided.
Required:
Match each item to its descriptive phrase by placing the appropriate letter in the space provided.Free
(Essay)
4.8/5 (82)
(82) Correct Answer:Verified
Verified
Disclosures for a defined benefit pension plan should include which of the following? I. number of beneficiaries II. reconciliation of the encling value of the projected benefit obligation: III. reconciliation of the ending fair value of the plan assets IV. the composition of plan assets V. the discount rate used VI. expectedlong term rate of return on plan assets
(Multiple Choice)
4.9/5 (87)
(87) Mandy Co.has a defined benefit pension plan for its employees.The plan was amended at the beginning of 2010 which increased benefits based on services rendered by certain employees in prior periods.The actuary has reported that unrecognized prior service cost resulting from the amendment is $385, 000.Five employees expect to receive the increased benefits.Shown below is a schedule of the employees and their expected years of future service:
Expected Years of Employee No. Future Service 1 5 2 6 3 7 4 8 5 9
Required:
Using the straight-line method:
a. Compute the average remaining service life.
b. Determine the amount of unrecopnized prior service cost to be included in the 2010 persion expense calculation.
(Essay)
4.8/5 (86)
(86) Exhibit 20-2 Minnie Co.has an unfunded prepaid/accrued pension cost of $2, 000 (debit balance)at December 31, 2010.The following information pertains to 2011:
Pension expense \ 320,000 Projected benefit obligation, December 31, 2011 840,000 Contributions 330,000 Plan assets (fair value), December 31, 2011 810,000
- Refer to Exhibit 20-2.The December 31, 2011, adjusting entry should be
(Multiple Choice)
4.9/5 (79)
(79) Current GAAP defines the required calculations for all of the following items except
(Multiple Choice)
4.8/5 (86)
(86) Tina Company had the following information related to its pension plan:
Beginning of 2010 2011 2012 Projected benefit obligation \ 6,000 \ 7,990 \ 9,200 Plan assets 8,400 8,700 8,800 Urrecognized net lossreported by actuary 990
The average remaining service life = 3 years
An additional unrecognized net loss of $990 was reported as of January 1, 2011 (see table).This amount has been included in the January 1, 2011.projected benefit obligation balance.
Required:
Compute the amount of unrecognized loss that should be included in pension expense in:
a. 2011
b. 2012
(Essay)
4.9/5 (72)
(72) GAAP for pension plans requires companies with defined benefit pension plans to
(Multiple Choice)
4.8/5 (83)
(83) Which of the following statements regarding postretirement benefits other than pensions is true?
(Multiple Choice)
4.8/5 (65)
(65) Current GAAP regarding employers' accounting for defined benefit pension plans defines an underfunded pension at the end of the period when the
(Multiple Choice)
5.0/5 (80)
(80) Exhibit 20-1 Given the following information:
2010 2011 2012 Projected benefit obligation \ 600 \ 700 \ 1,200 Plan asset value 400 800 1,100 Average remaining service life = 5 years
An unrecognized net loss existed at the beginning of 2010 in the amount of $100.An additional unrecognized net loss of $20 is reported by actuaries as of the end of 2011.
-
Refer to Exhibit 20-1.What amount of loss should be added to pension expense in 2010?
(Multiple Choice)
4.9/5 (61)
(61) Current GAAP requires that the net gain or loss from a settlement or curtailment be included in the
(Multiple Choice)
4.8/5 (89)
(89) Unrecognized prior service cost would be reported on the balance sheet and affect the amount(s)reported for
(Multiple Choice)
4.9/5 (75)
(75) Which of the following is not a component of the net periodic pension expense to be reported on a company's income statement?
(Multiple Choice)
4.8/5 (88)
(88) Exhibit 20-3 The Grace Company adopted a defined benefit pension plan on January 1, 2010, and prior service credit was granted to employees.The present value of those benefits was calculated to be $1, 351, 800 at that date.The service cost is funded in full at the end of each year, plus an additional amount of $220, 000 is funded each year-end.The unrecognized prior service cost is being amortized by the straight-line method over the remaining 10-year service life of the company's active employees.Additional information relating to the company's pension plan is presented below:
2010 2011 Service cost (annual) \ 95,000 \ 105,000 Unrecogrized prior service cost amortization 135,180 135,180 Interest cost 10\% 10\% Expected (and actual) return on plan assets 10\% 10\%
-Refer to Exhibit 20-3.What is the pension expense for 2011?
(Multiple Choice)
5.0/5 (75)
(75) Exhibit 20-3 The Grace Company adopted a defined benefit pension plan on January 1, 2010, and prior service credit was granted to employees.The present value of those benefits was calculated to be $1, 351, 800 at that date.The service cost is funded in full at the end of each year, plus an additional amount of $220, 000 is funded each year-end.The unrecognized prior service cost is being amortized by the straight-line method over the remaining 10-year service life of the company's active employees.Additional information relating to the company's pension plan is presented below:
2010 2011 Service cost (annual) \ 95,000 \ 105,000 Unrecogrized prior service cost amortization 135,180 135,180 Interest cost 10\% 10\% Expected (and actual) return on plan assets 10\% 10\%
- Refer to Exhibit 20-3.What is the correct amount of the projected benefit obligation as of December 31, 2011?
(Multiple Choice)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)