



 Chat with AI
Exam 20: Accounting for Postemployment Benefits

Exam 1: The Environment of Financial Reporting41 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System87 Questions
Exam 4: The Balance Sheet and the Statement of Changes in Stockholders Equity78 Questions
Exam 5: The Income Statement and the Statement of Cash Flows104 Questions
Exam 6: Additional Aspects of Financial Reporting and Financial Analysis95 Questions
Exam 7: Cash and Receivables99 Questions
Exam 8: Inventories: Cost Measurement and Flow Assumptions89 Questions
Exam 9: Inventories: Special Valuation Issues109 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Disposal88 Questions
Exam 11: Depreciation and Depletion103 Questions
Exam 12: Intangibles84 Questions
Exam 13: Current Liabilities and Contingencies99 Questions
Exam 14: Long-Term Liabilities and Receivables140 Questions
Exam 15: Investments101 Questions
Exam 16: Contributed Capital121 Questions
Exam 17: Earnings Per Share and Retained Earnings86 Questions
Exam 18: Income Recognition and Measurement of Net Assets71 Questions
Exam 19: Accounting for Income Taxes74 Questions
Exam 20: Accounting for Postemployment Benefits68 Questions
Exam 21: Accounting for Leases114 Questions
Exam 22: The Statement of Cash Flows62 Questions
Exam 23: Accounting for Changes and Errors86 Questions
Exam 24: Time Value of Money Module72 Questions
Select questions type


On January 1, 2010, a company had $84, 000 of unrecognized prior service cost.The years-of-future-service method of amortization is used.The company has seven employees, as indicated below: Expected Years of Employee Future Service 3 5 5 6 6 8 9
What amount of prior service cost should be included in pension expense for 2010?
(Multiple Choice)
4.9/5  (74)
(74) Betsy Company estimated that at the end of seven years, it will be necessary to have $90, 000 available in a pension fund.The correct interest rate was 9%.Actuarial information for seven periods at 9% follows:
Future amount of 1 1.8280 Future amount of ordinary annuity of 1 9.2004 Present value of 1 0.5470 Present value of ordinary annuity of 1 5.0330
Required:
Compute the amount that the company must deposit at the end of each year in order to have the necessary funds available at the end of the seventh year.
(Short Answer)
4.8/5 (80)
(80) According to current GAAP, termination benefits paid to an employee should be
(Multiple Choice)
4.8/5 (82)
(82) Which of the following statements is true regarding a defined benefit pension plan?
(Multiple Choice)
4.8/5 (77)
(77) Current GAAP requires that the financial statements issued by a funding agency for a company's pension plan include all of the following except
(Multiple Choice)
4.8/5 (73)
(73) A company's net periodic pension cost (expense)includes all of the following items except
(Multiple Choice)
4.8/5 (77)
(77) In 2011, the Marsha Company closed a manufacturing plant.The resulting actuarial loss should be
(Multiple Choice)
4.9/5 (78)
(78) Matilda, Inc.amended its defined benefit pension plan as of January 1, 2010.Matilda received a report from its actuary stating that at the beginning of 2010 unrecognized prior service cost resulting from the amendment amounted to $144, 000.The company's work force was composed of twelve people.Four were expected to retire at the end of 2012.Two were expected to retire at the end of 2014, two more at the end of 2016, and four at the end of 2018.
Required:
Using the years-of-future-service method, compute the amount of prior service cost to be amortized in the first year.
(Essay)
4.8/5 (82)
(82) Benefits for which the employee's right to receive a present or future pension benefit is no longer contingent on remaining in the service of the employer are called
(Multiple Choice)
4.8/5 (90)
(90) O'Brien began a defined benefit pension plan on January 1, 2010.During 2010, the service cost was $450, 000.O'Brien contributed $450, 000 to the pension plan for 2010.The actuary said the projected benefit obligation at December 31, 2010 was $450, 000.As of December 31, 2010, what statements can O'Brien make about the pension plan? 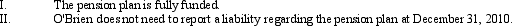
(Multiple Choice)
4.9/5 (74)
(74) Match each item to its descriptive phrase by placing the appropriate letter in the space provided.
Correct Answer: Verified
Premises:
Responses:
(Matching)
4.8/5 (77)
(77) According to GAAP, the net periodic pension cost or, for simplicity, pension expense for a defined benefit pension plan consists of five components.
Required:
List and briefly describe each of the five components of net periodic pension cost that a company must recognize.
(Essay)
4.9/5 (72)
(72) The cost of retroactive benefits granted in a plan amendment or at the initial adoption of a pension plan is called
(Multiple Choice)
5.0/5 (75)
(75) An Internal Revenue Code rule that impacts the design of pension plans is
(Multiple Choice)
4.9/5 (73)
(73) One type of post-retirement benefit other than pensions is healthcare benefits.
Required:
Discuss the major differences between postretirement healthcare benefits and pensions.
(Essay)
4.8/5 (84)
(84) Because of significant government funding of benefits to retirees, it is likely that total pension costs are
(Multiple Choice)
4.9/5 (84)
(84) Exhibit 20-3 The Grace Company adopted a defined benefit pension plan on January 1, 2010, and prior service credit was granted to employees.The present value of those benefits was calculated to be $1, 351, 800 at that date.The service cost is funded in full at the end of each year, plus an additional amount of $220, 000 is funded each year-end.The unrecognized prior service cost is being amortized by the straight-line method over the remaining 10-year service life of the company's active employees.Additional information relating to the company's pension plan is presented below:
2010 2011 Service cost (annual) \ 95,000 \ 105,000 Unrecogrized prior service cost amortization 135,180 135,180 Interest cost 10\% 10\% Expected (and actual) return on plan assets 10\% 10\%
- Refer to Exhibit 20-3.What is the pension expense for 2010?
(Multiple Choice)
4.8/5 (82)
(82) A list of descriptive phrases related to pension plan accounting is shown below:
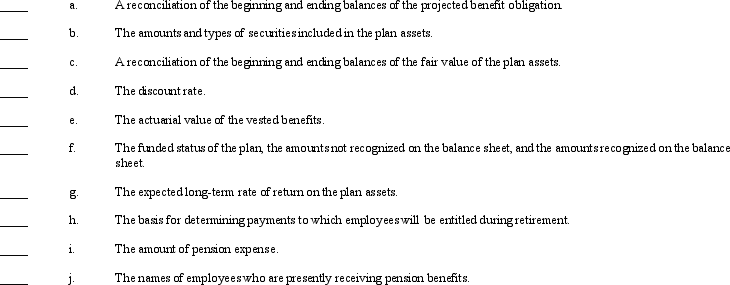 Required:
In the space preceding each phrase, indicate whether the item described must be disclosed per the requirements of current GAAP regarding an employer's disclosures about pensions and other postemployment benefits.Use "Y" if the item is a required disclosure and "N" if it is not a required disclosure.
Required:
In the space preceding each phrase, indicate whether the item described must be disclosed per the requirements of current GAAP regarding an employer's disclosures about pensions and other postemployment benefits.Use "Y" if the item is a required disclosure and "N" if it is not a required disclosure. (Essay)
4.7/5 (75)
(75) Which of the following items attributable to a defined benefit pension plan would be recognized on a company's balance sheet? ProjectedBenefit Pension Plan Prepaid Pension: Obligation Assets Costs I. Yes Yes Yes II. Yes Yes No III. Yes No No IV. No No Yes
(Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)